

 Calculate Revenue
 Research Markets
 Find For Sale Properties
 Compare My Listing
 STR Revenue Calculator
 Custom Comp Sets
 Submarket Insights
 Custom Search Filters
 Rate Recommendations
 Performance Benchmarking
 Competitor Comparison
 Owner Contact Details
 Property-level performance data
 Tourism Insights
 Real Estate Investment Analytics
 About Us
 Sales
 Support
 Press
Europe Market Review: Strong April Brings Demand Growth, and Supply Catches Up Outside of Cities | AirDNA
Published: May 23, 2023
Last updated: October 14, 2024
Scott Sage
Easter holidays and fairer weather brought good news for both the economy and European short-term rental (STR) hosts in April 2023, as demand nights stayed grew 16.6% from the same month last year, giving hosts greater pricing power to push average daily rates (ADRs) up 11.1% year over year (YOY). Remaining above 2019 levels (+4.6%) in April, the supply of available listings in Europe increased 13.1% YOY, lagging behind demand growth and pushing occupancy rates up 0.4%. In another strong month for short-term rental hosts in Europe, revenue per available rental (RevPAR) also increased 11.6% YOY.
At a Glance: Key European STR Performance Metrics for April 2023:
- Revenue increased 29.6% YOY and 55.4% vs. 2019
- Available listings were above 2019 levels (+4.6%) and up 13.1% YOY
- Total demand (nights) rose 16.6% YOY and 14.5% from 2019
- Occupancy was up 0.4% vs. 2022 and down 1.5 vs. 2019
- Average daily rates (ADRs) rose 11.1 % YOY and 35.7% vs 2019
- RevPAR grew 11.6% YOY and 33.7% vs. 2019
While Eurozone GDP grew just 0.1% in the first quarter, this is a relief as the continent narrowly avoided recession. It was widely expected that Europe would be in recession in the first half of 2023. However, inflation is still frustratingly high, with April headline inflation up 7%, causing strain on individuals’ spending power. The outlook for the rest of the year, according to Oxford Economics, calls for the European economy to continue to expand over the next year, with GDP forecasted to increase 0.8% in 2023 and an additional 1.0% in 2024, driven by further growth in consumer spending—which should be positive for short-term rentals.
European Supply Recovery Slow but Steady
European short-term rentals have been slower to recover to pre-pandemic levels compared to other continents. In North and South America, where demand and supply have seen the quickest recovery, demand returned to pre-pandemic levels in March 2022 for North America and June 2022 for South America. Supply quickly followed, with available listings returning to pre-pandemic levels in July 2022 for both continents.
Meanwhile in Europe, demand, measured on a trailing 12-month basis, finally returned to pre-pandemic levels this past month while supply has yet to fully recover.
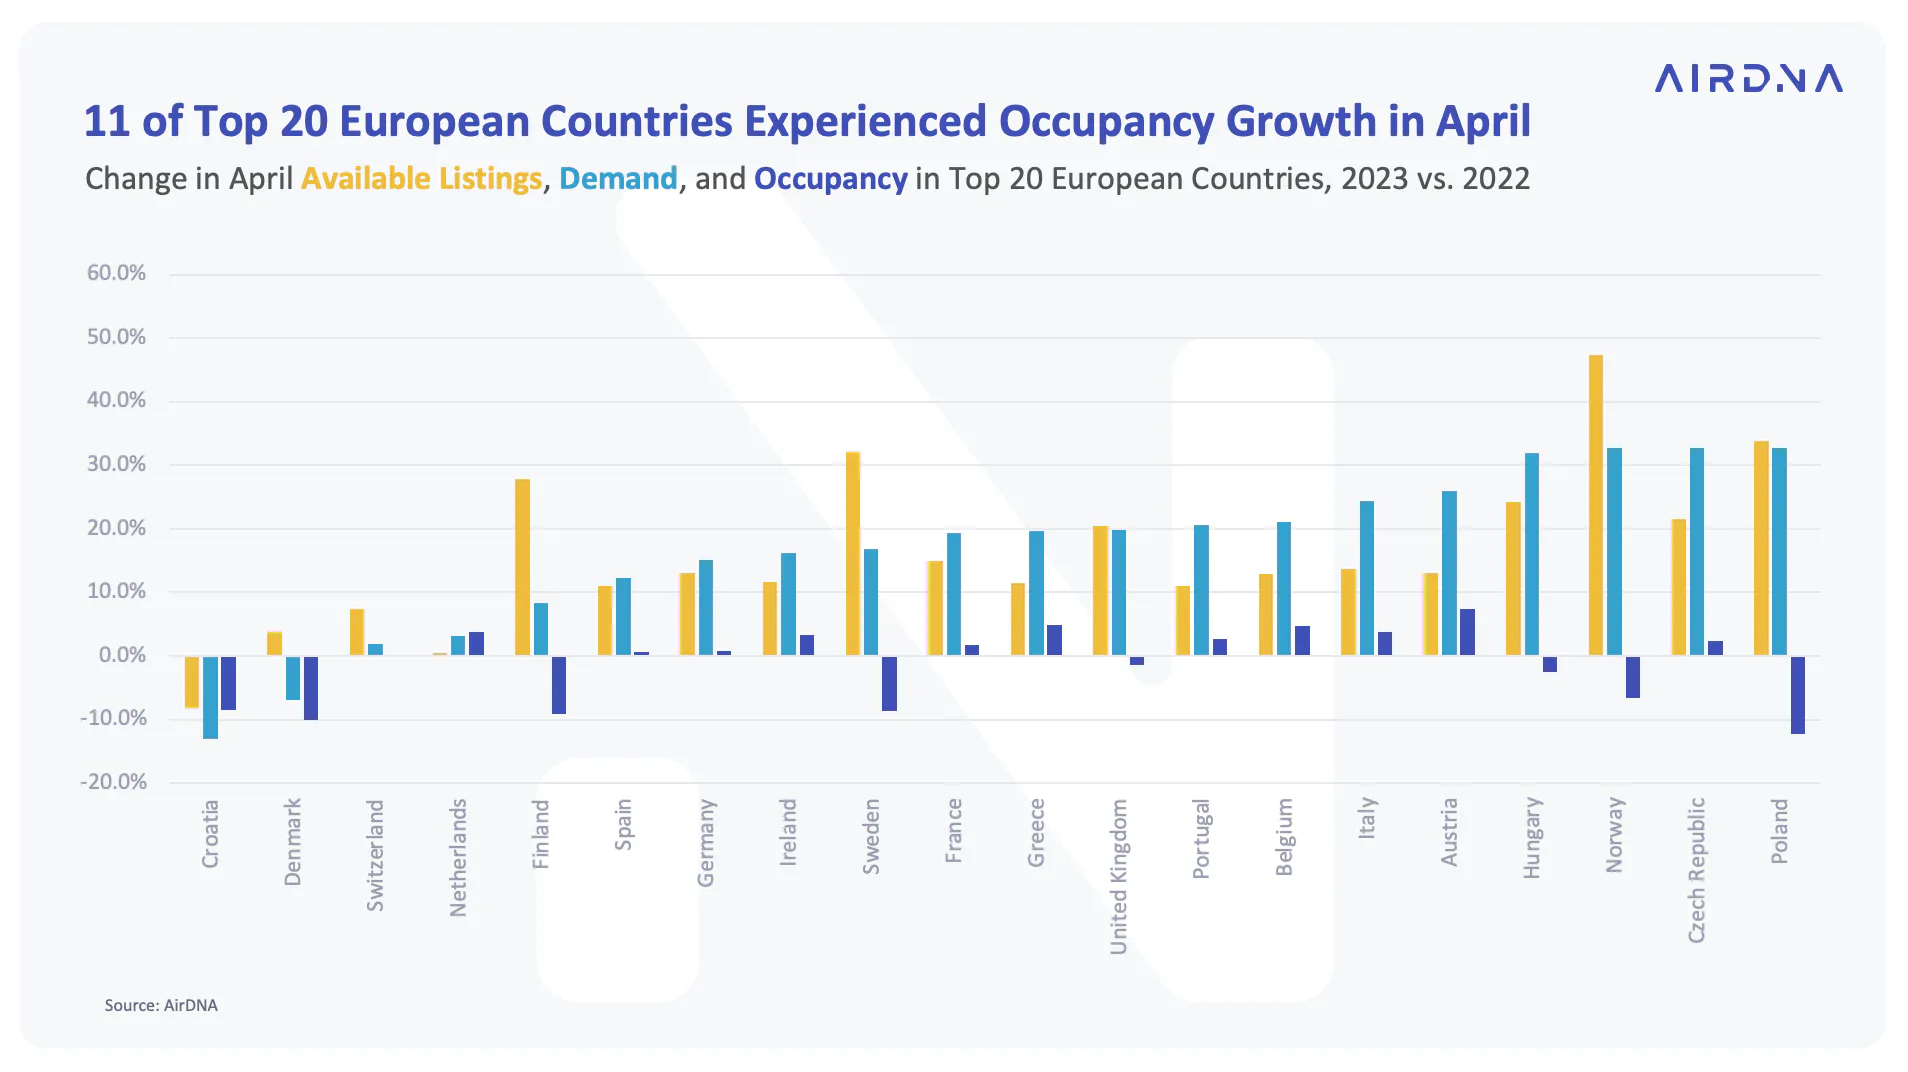
Across our top 20 European countries, supply has returned to varying degrees. Croatia saw negative YOY supply growth last month (-8.2% YOY), and the Netherlands saw minimal supply growth (+0.4% YOY). The Nordic region saw the strongest supply growth, with supply growth exceeding 25% in Finland (+27.9%), Sweden (+32%), and Norway (+47.3%). Unluckily for operators, supply growth in these three countries exceeded demand growth, causing occupancy declines.
Occupancy grew during April in 11 of the 20 largest European countries, as supply lagged behind demand. Greece and Austria are seeing great gaps between YOY supply and demand growth and, consequently, the highest growth in occupancy.
In Greece, demand grew 19.7% YOY, and supply grew 11.6%, pushing occupancy up 4.8 YOY, while in Austria, demand grew 26%, and supply grew 13%, causing occupancy to grow 7.5% YOY.
Demand Recovery Stronger in Rural Areas than Urban
Following a trend that began during the pandemic, demand for short-term rentals in more rural areas continues to outperform the continent’s largest cities. Where demand returned to pre-pandemic levels in October of 2021 for listings outside of the top 50 European cities, in those top 50 European cities, we have yet to see demand return in full. In April 2023, demand within European cities was still 15% below demand in 2019, and supply was 23% below 2019.
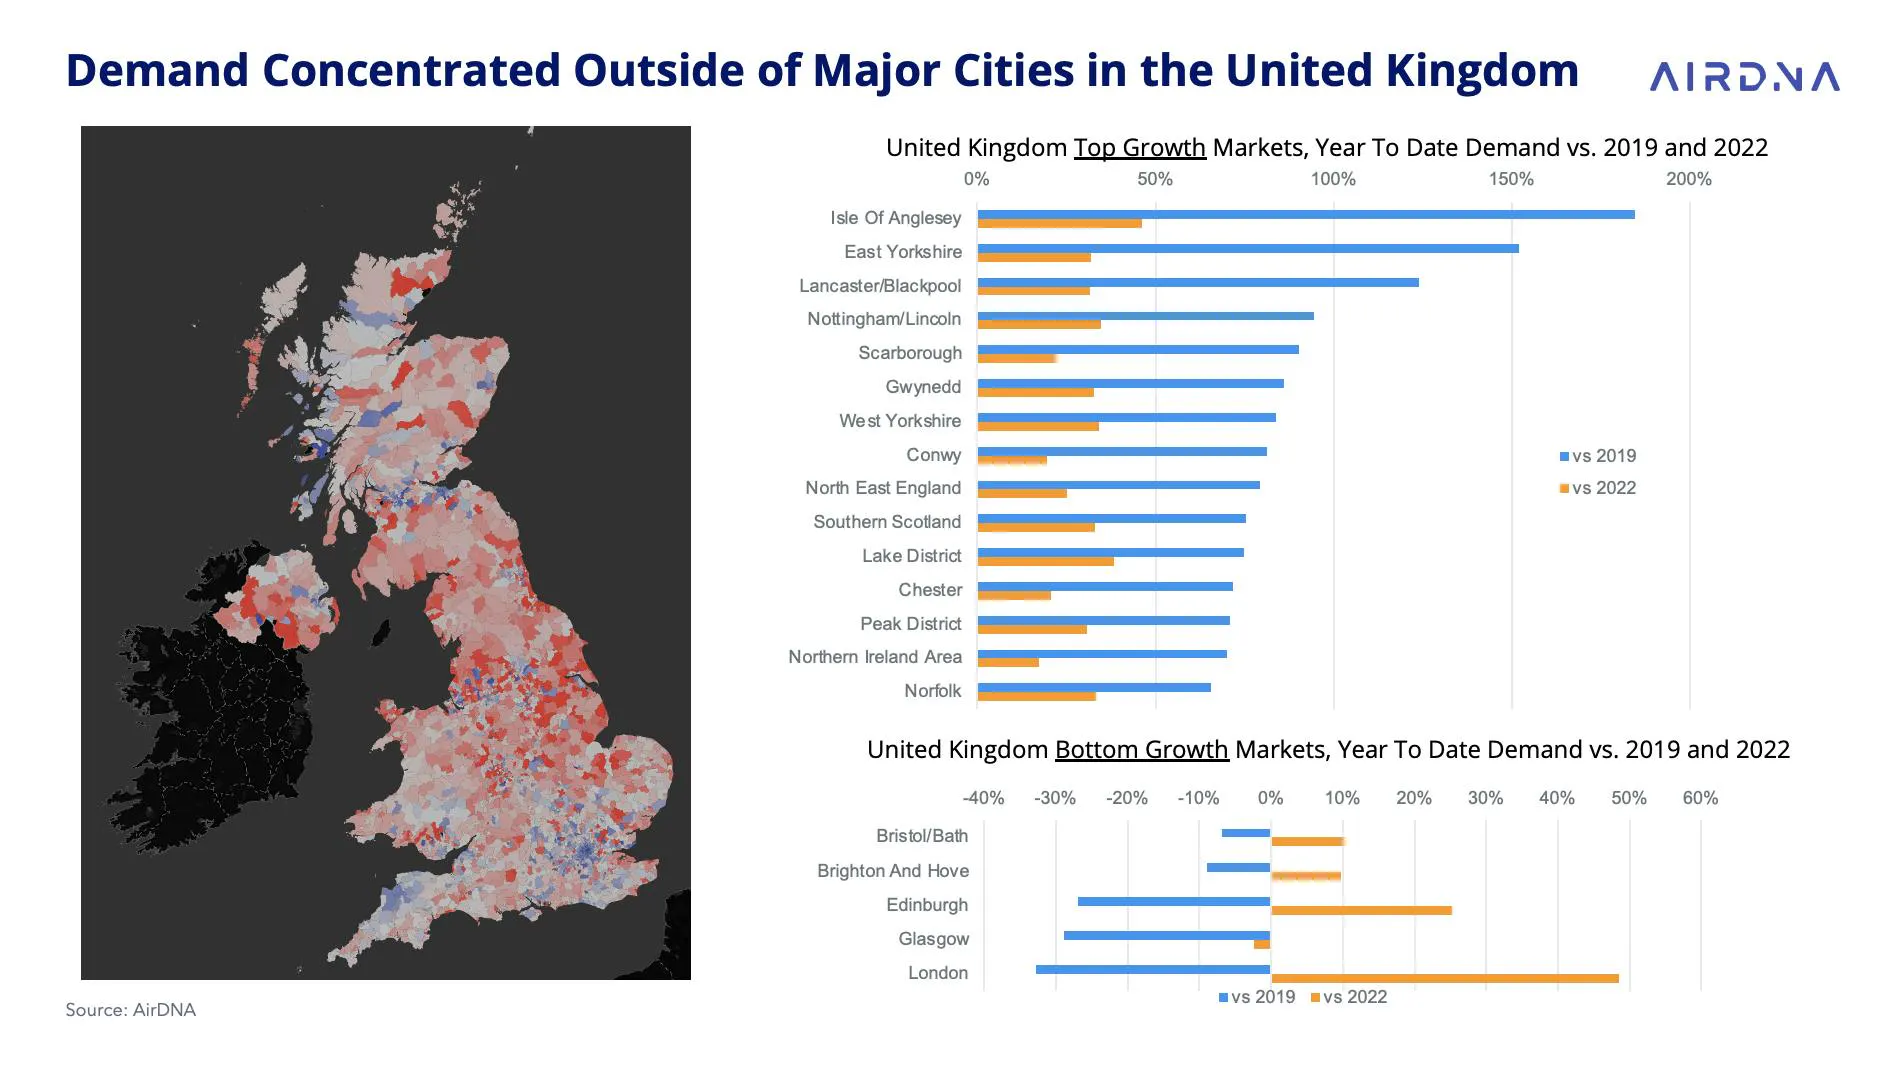
Analysing trends in the United Kingdom, we see growth in demand has been concentrated outside of cities in the last two years, particularly in coastal and rural destinations. Exponential demand for seaside destinations such as the Isle of Anglesey, East Yorkshire, and Lancaster/Blackpool has given way to outstanding growth rates of 185%, 152%, and 124% compared to 2019. Other rural destinations such as Gwynedd, West Yorkshire, and Conwy have also fared well, with demand exceeding 2019 levels by more than 80% for all three destinations. Growth among the top 15 UK markets continues to show strength, with demand averaging 31% higher than last year.
On the other end of the spectrum, large cities have seen the lowest demand growth in the United Kingdom. London has seen the slowest demand recovery in the country, with demand for short-term rentals still 33% lower than in 2019.
Demand in cities may not have returned to pre-pandemic levels yet, but travel interest in cities is reviving and will likely lead to faster growth in urban demand and supply in the next year. In the bottom demand growth markets of the United Kingdom, we see that YOY growth in demand for these large cities has been trending upward, particularly in London, where YOY growth was 48%.
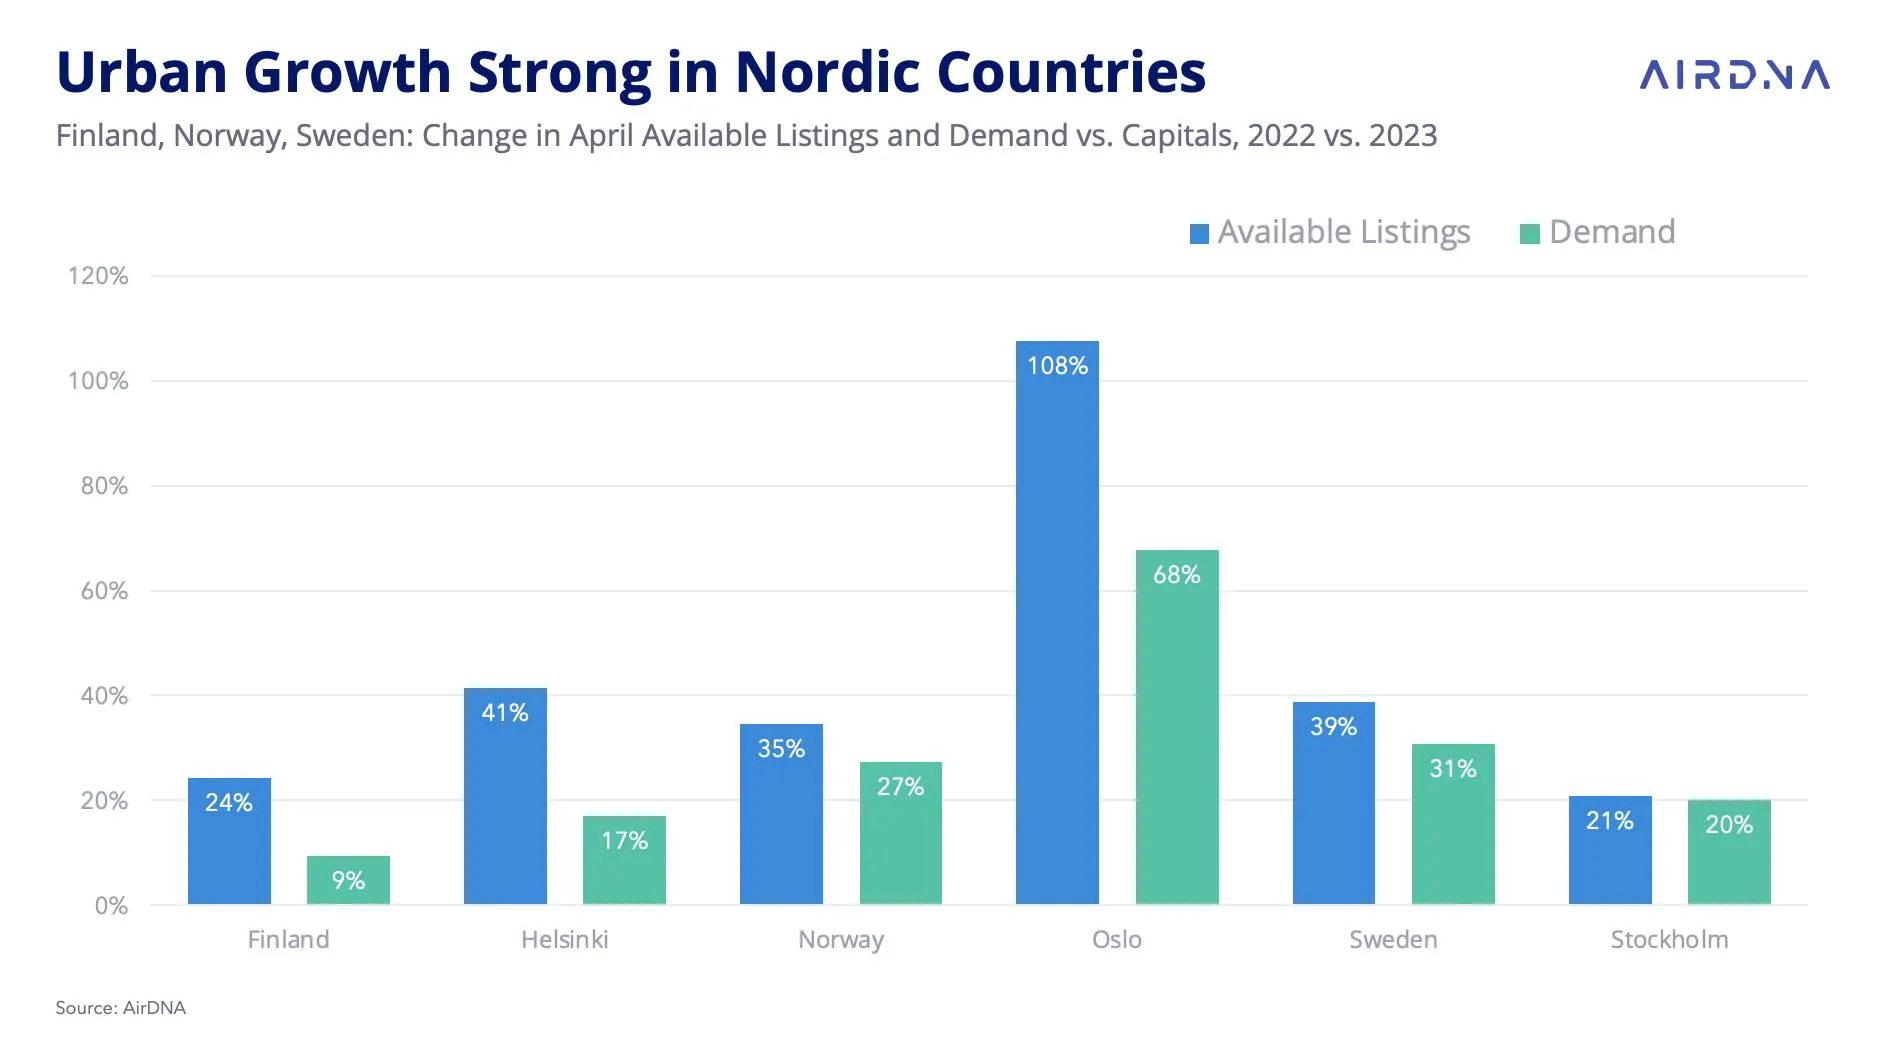
Recovering travel interest in cities can also be seen in some of Europe’s fastest-growing short-term rental markets. Supply growth is often a lagging indicator of where demand has been the greatest. In Finland, Norway, and Sweden, where supply growth has exceeded demand growth YOY, we see greater supply growth in the capital cities of Finland and Norway than we do outside of them. Available listings grew 41% YOY in Helsinki compared to 24% in the rest of Finland, while demand grew 17% YOY compared to 9% for the rest of the country. In Oslo, available listings grew 108% YOY compared to 35% in the rest of Norway, and demand grew 68% YOY compared to 27% for the country. In Sweden, the capital Stockholm did not outperform the rest of the country but still saw 20% YOY growth in supply and demand.
Demand Pacing Strong Through Summer and Autumn
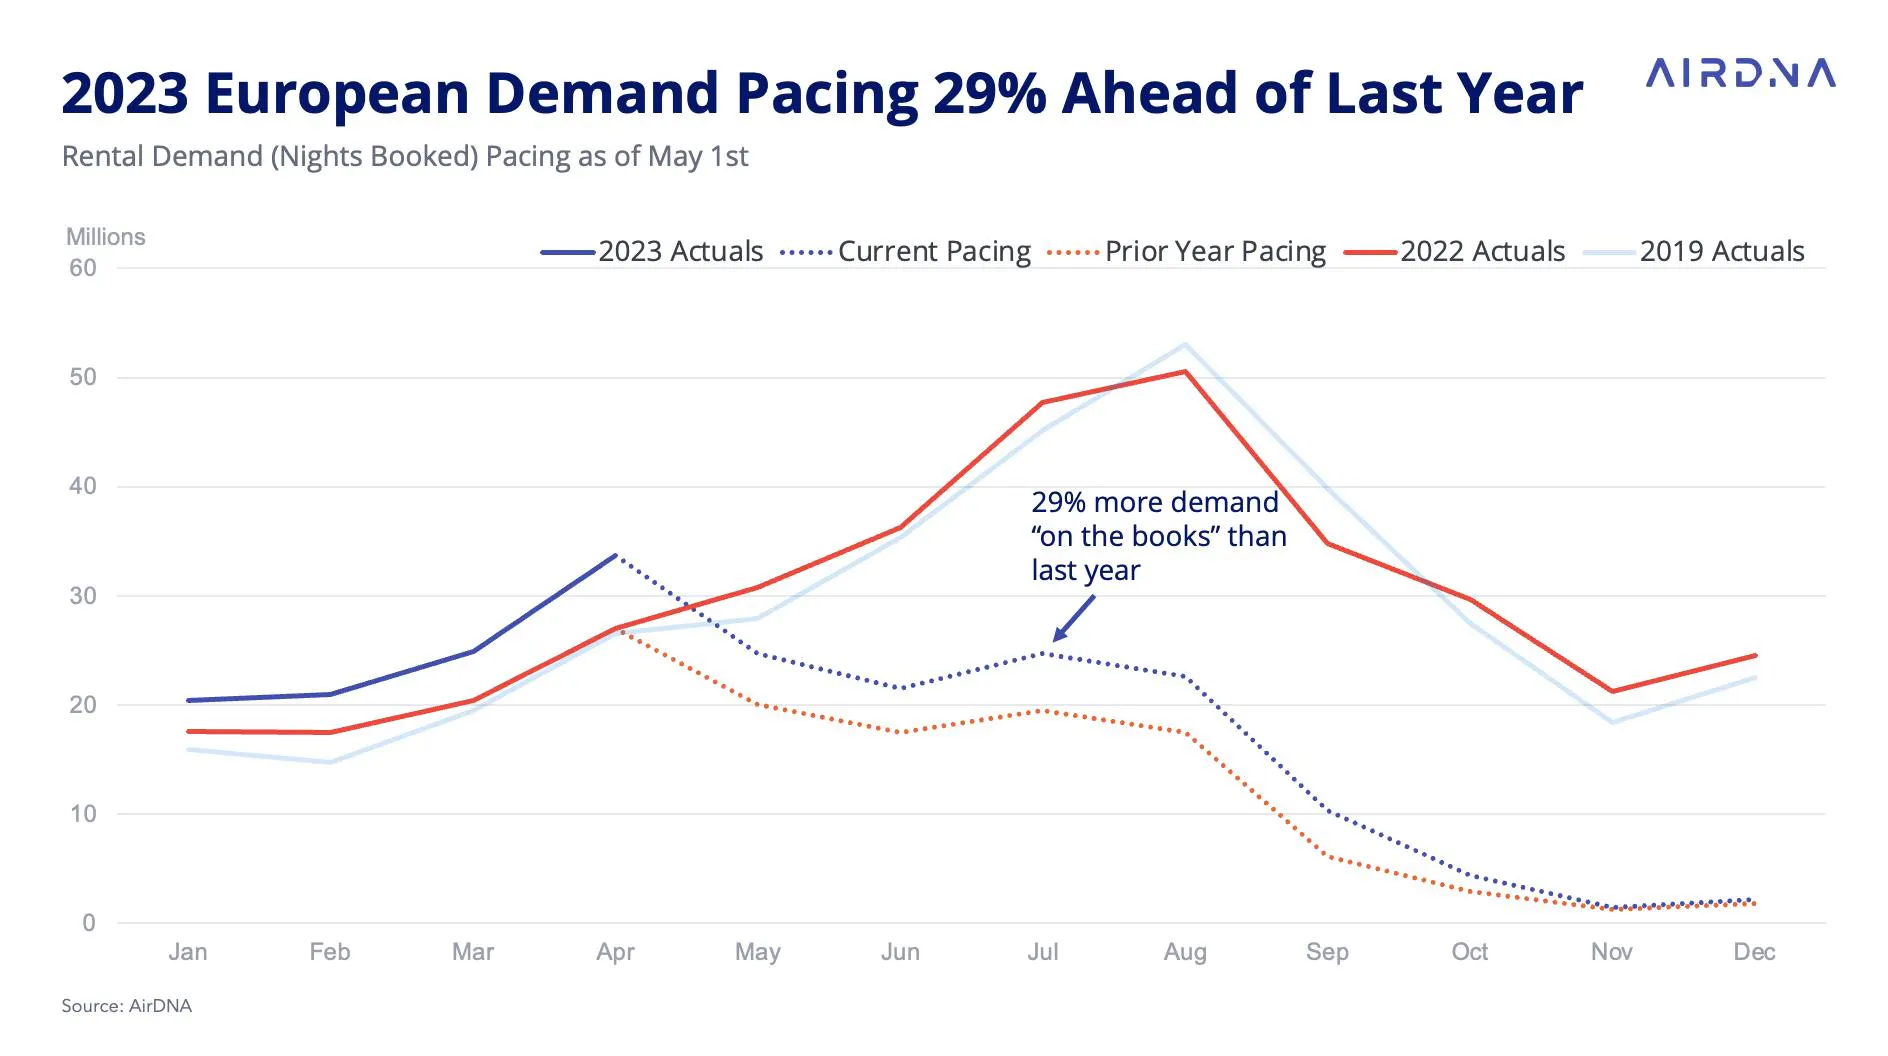
As of May 1, demand nights on the books were pacing 29% higher than at the same time in 2022. Booking activity continues to have great momentum through the summer and autumn as demand for travel in Europe accelerates. For the summer months of June, July, and August, demand was up 23%, 26%, and 30% YOY, respectively. September and October pacing sees the most standout gains, with booked nights exceeding last year by 70% for September and by 49% for October. Guests are looking to travel beyond the summer peak season, and Europe is on track to reach record-breaking levels of nights stayed this autumn.
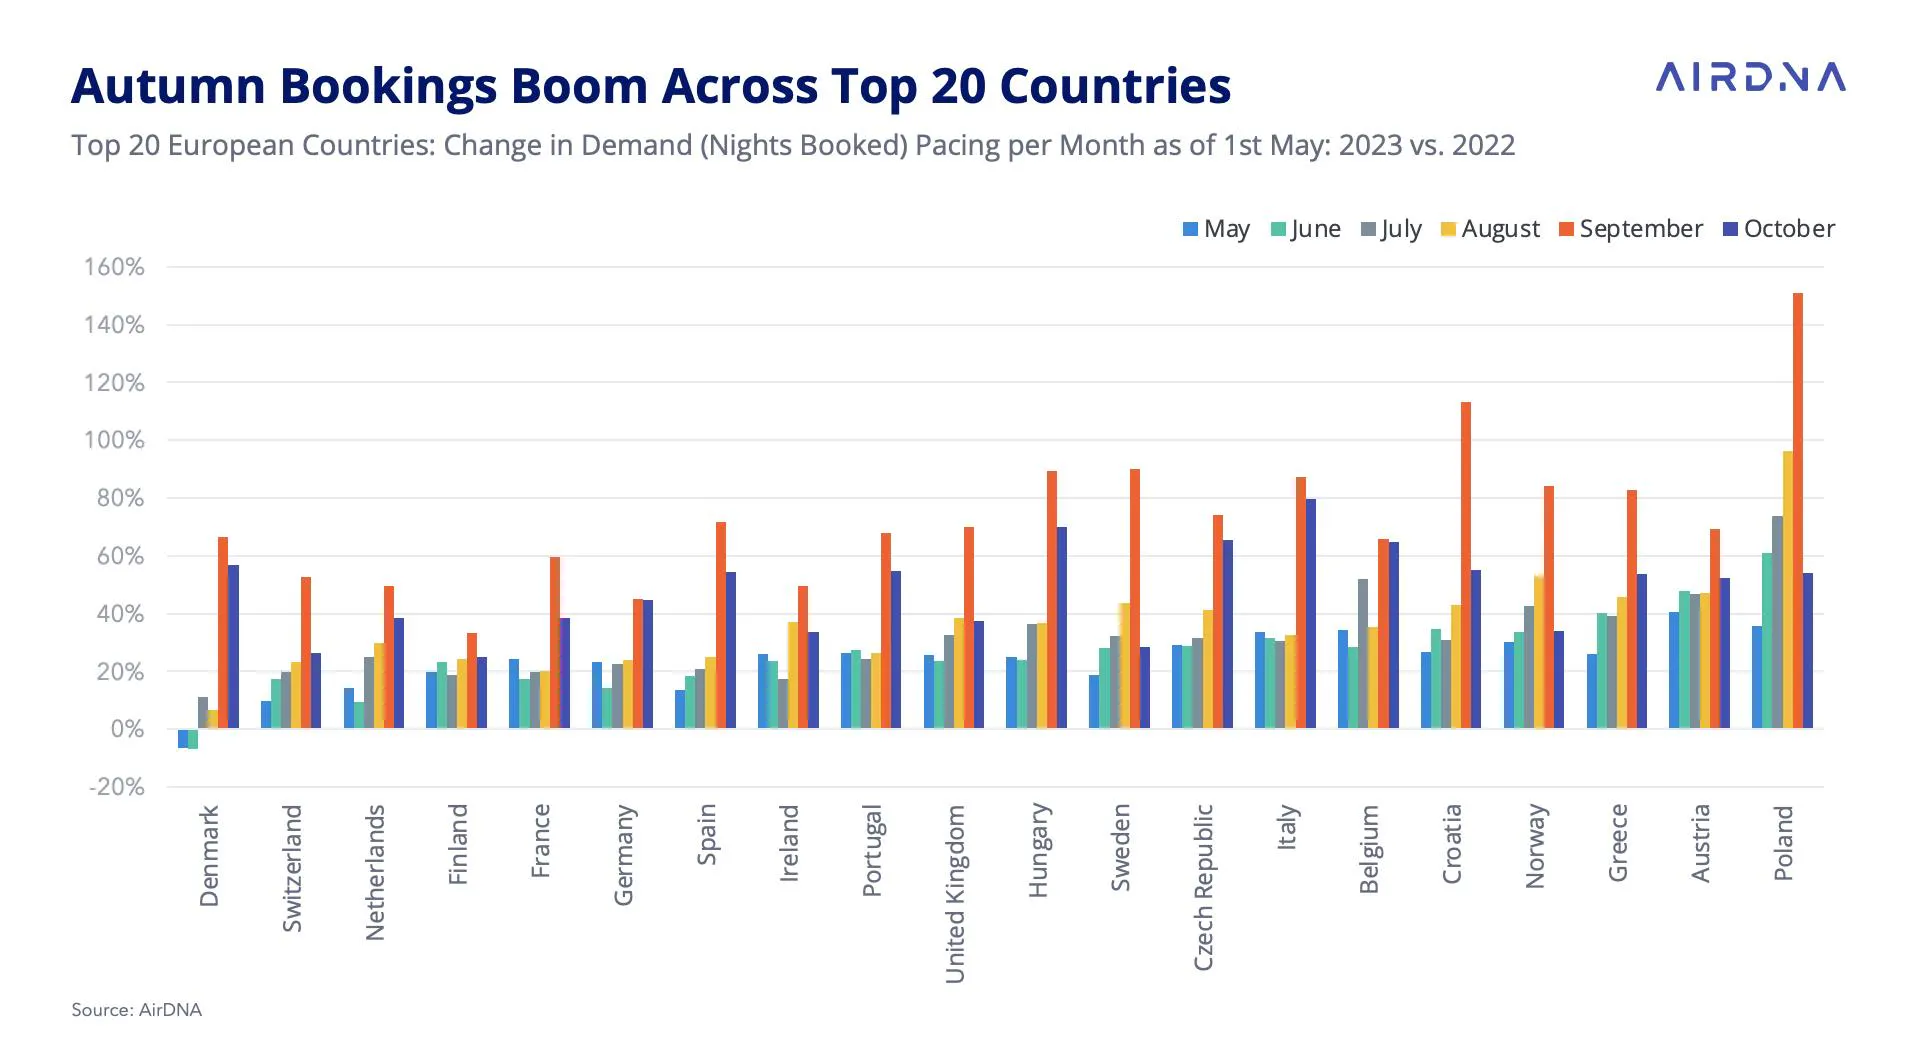
Looking closer at demand pacing among our top 20 European countries, Poland, Austria, and Greece led the way in growth for nights booked between May and October, with 63%, 48%, and 42% growth compared to last year. September pacing growth was more than 50% YOY for 16 of the top 20 European countries, with Poland and Croatia experiencing triple-digit growth of 151% and 113% YOY, respectively. October pacing growth was more than 50% for 11 of the top 20 European countries, with Italy, Hungary, and Czech Republic leading the way with 80%, 70%, and 65% YOY growth.
As part of our ongoing commitment to accuracy, we continuously implement data methodology improvements, leading to updates to some of the information in this report as of December 21, 2023. For further questions, please contact us.
ARTICLE SUMMARY
Easter holidays and fairer weather brought good news for both the economy and European short-term rental (STR) hosts in April 2023, as demand nights stayed grew 16.6% from the same month last year, giving hosts greater pricing power to push average daily rates (ADRs) up 11.1% year over year (YOY).
Scott Sage
Senior Vice President, Marketing & Customer Experience
Scott is an Airbnb Superhost and industry pro, having founded Home Base BnBs—a short term rental management company that scaled to 200+ units. Scott combines his experience and passion for hosting to empower AirDNA customers' success. When he's not thinking about STRs, he is hiking, playing basketball, or playing pickleball.
