

 Calculate Revenue
 Research Markets
 Find For Sale Properties
 Compare My Listing
 STR Revenue Calculator
 Custom Comp Sets
 Submarket Insights
 Custom Search Filters
 Rate Recommendations
 Performance Benchmarking
 Competitor Comparison
 Owner Contact Details
 Property-level performance data
 Tourism Insights
 Real Estate Investment Analytics
 About Us
 Sales
 Support
 Press
European Market Review: Strong RevPAR Keeps STR Investment and Demand Strong | AirDNA
Published: December 21, 2023
Last updated: May 5, 2026
Scott Sage
The European short-term rental (STR) market saw significant growth and resilience in November, with strong supply growth and stable demand growth reducing occupancy’s gap with last year. The increase in listings, particularly from new additions rather than old listings returning to the market, suggests strong investor confidence despite high interest rates. Nordic countries experienced occupancy dips due to supply outpacing demand, while countries like Croatia, Greece, Spain, and Czechia saw occupancy growth.
At a Glance: November STR Performance in Europe
- Available listings were up 19.6% year-over-year (YOY) and 16.4% above 2019
- Demand was up 9.1% YOY, 18.1% vs. 2019
- Average daily rates (ADRs) were up 10.7% YOY and 44% vs. 2019
- Revenue was up 20.8% YOY and 70.1% from 2019
- Occupancy was down 1.7% YOY and up 14.3% vs. 2019
- Revenue per available rental (RevPAR) grew 8.9% YOY and was up 64.6% from 2019
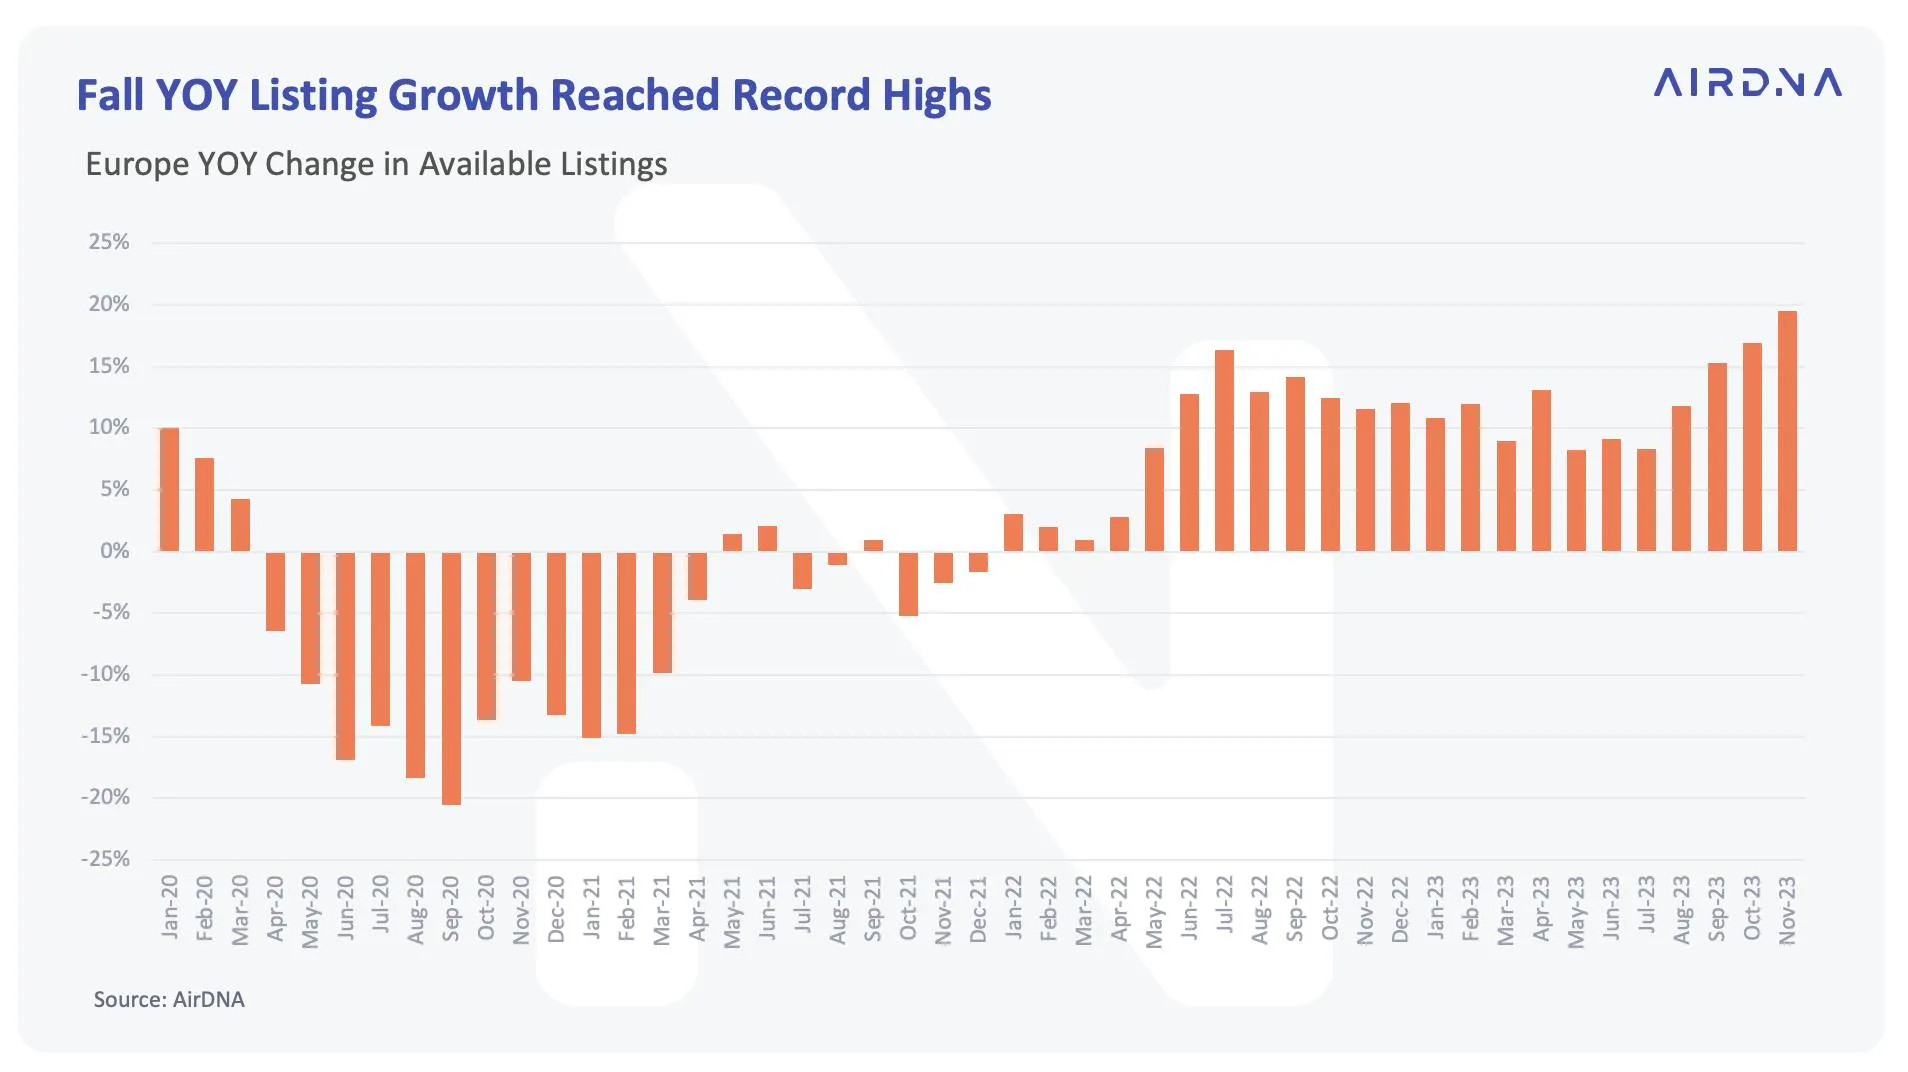
2023 has been a remarkable year for listing growth, but November set a new record with available listings up 19.6% YOY, the highest YOY growth we’ve seen for a given month since the pandemic.
November’s record supply growth was the culmination of three consecutive months of record-breaking YOY supply growth since the pandemic. YOY listing growth for September, October, and November averaged 17.1%. In contrast, average listing growth this summer (June-August) was 9.7% YOY, and this past winter (December-February) was 11.6% YOY.
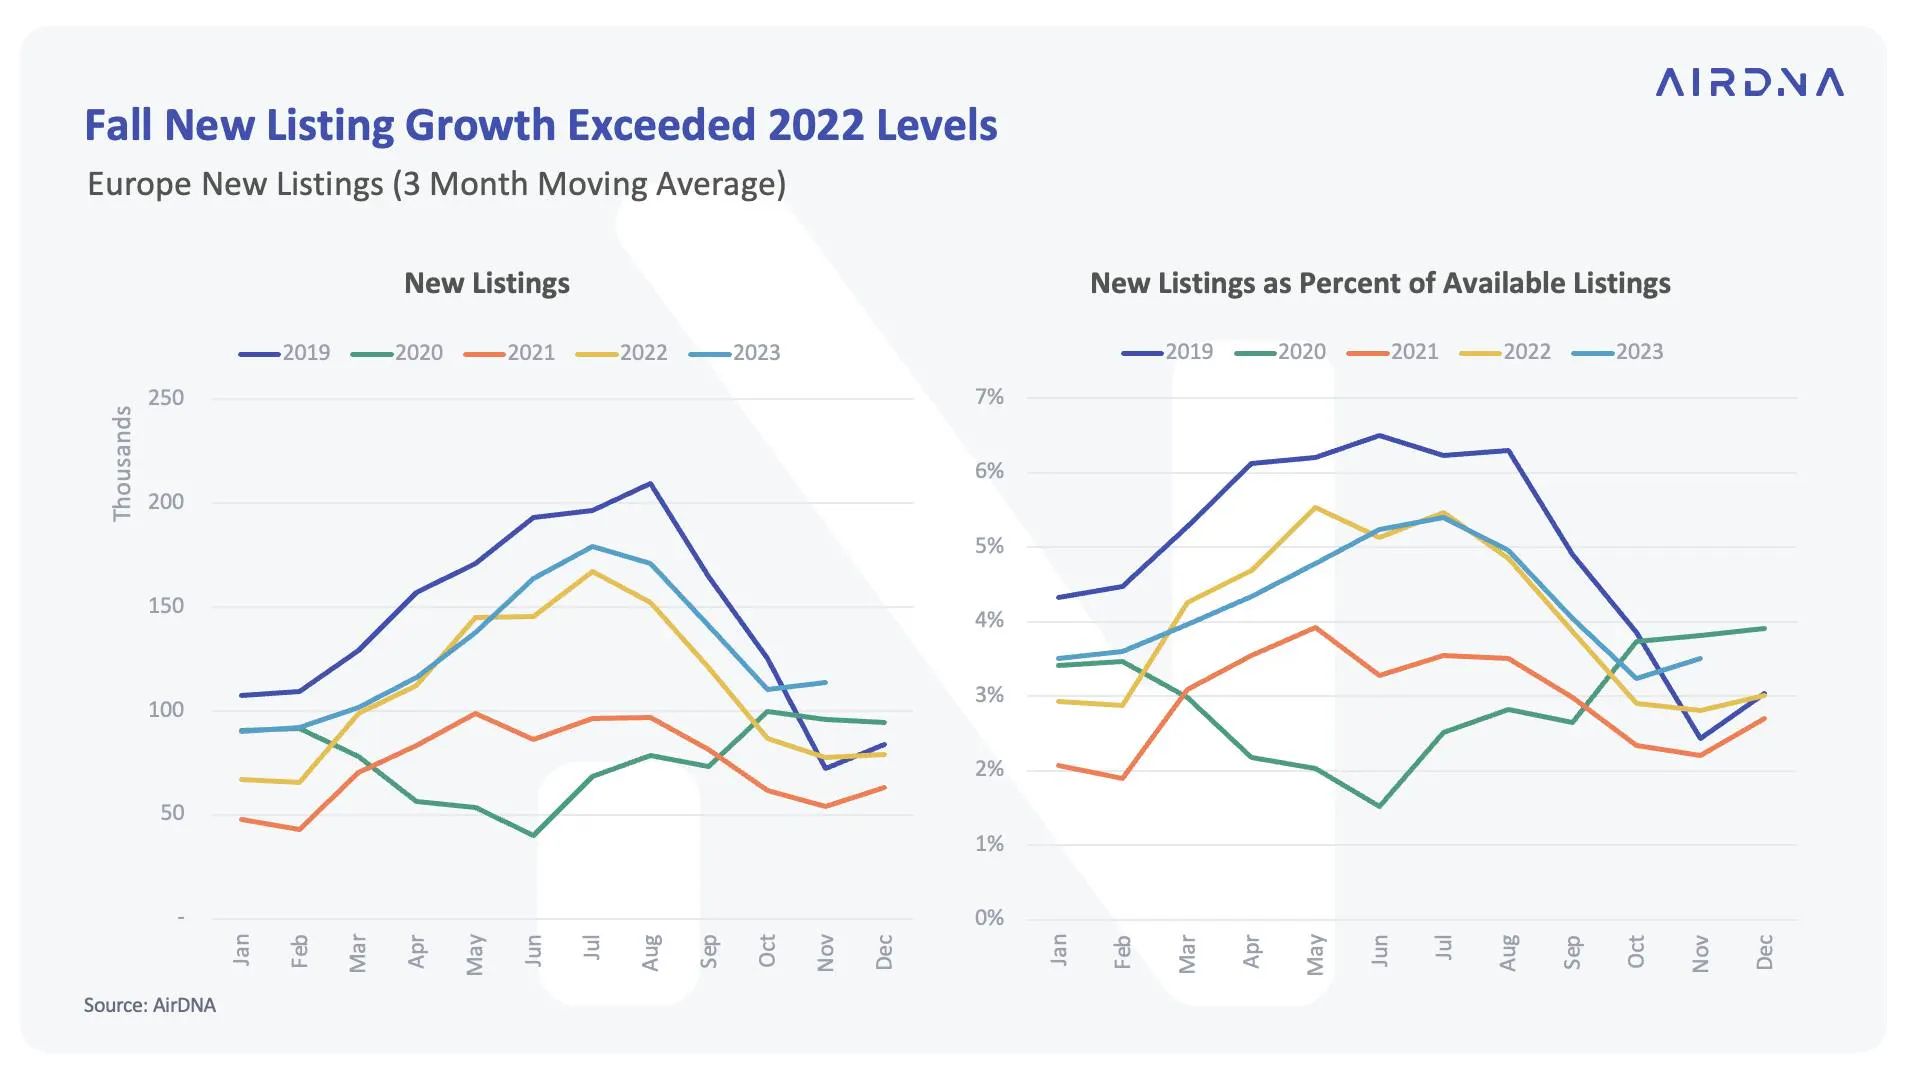
New listings joining the market have played a large role in available listing growth. On average, more than 130K new listings have been added in each month this year, up from 110K on average last year. Last month, new listings reached a record high. Hosts and investors added more than 140K new listings, the highest number of new listings we’ve ever seen in November. New listings this fall have also made up a larger percentage of total available listings than last year. In the last three months, new listings made up 3.5% of total available listings, a 25% increase from last fall when new listings made up 2.8% of available listings.
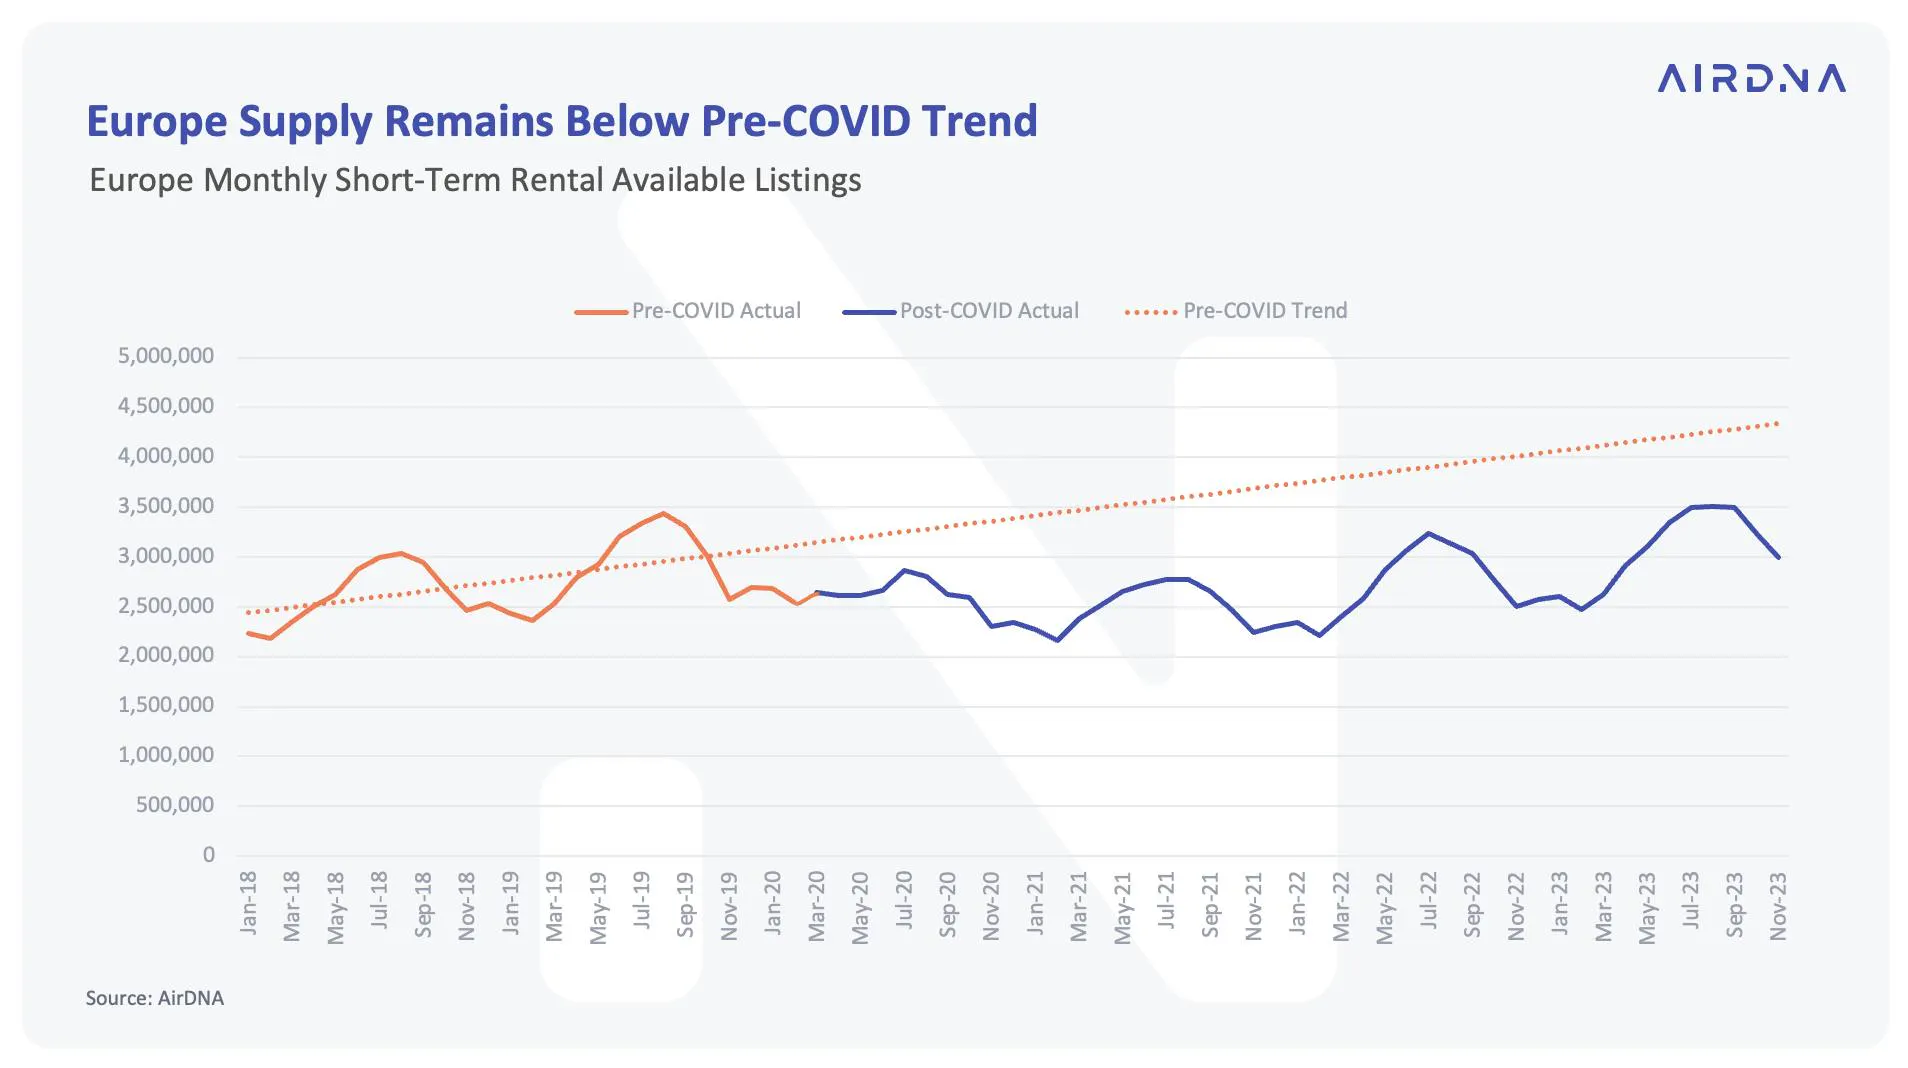
Despite the momentum we’ve seen in supply growth this year, available listings in Europe remain well below where they might have been had there not been a pandemic. The pandemic caused 13 consecutive months of YOY decline in available listings before recovery began in the summer of 2021. The return of international demand and the lifting of COVID travel restrictions paved the way for significant supply growth in 2022 (+9% YOY), but listings remained below 2019 levels. At the beginning of this year, available listings finally returned to 2019 levels, and monthly available listings have averaged 3.3 million in the last six months, a record high for the European continent. But compared to pre-COVID trends, monthly available listings are averaging more than 900,000 below what they could have been.
Despite a record season for listing growth, occupancy demonstrated incredible strength, declining just over 1% (-1.2% YOY) compared to 3.4% this summer. Occupancy strength was largely driven by unprecedented off-season demand. Demand this fall was up 13.4% YOY, more than double the 5.7% YOY demand growth we saw this summer. Travel outside of the high season to avoid the crowds, higher prices, and extreme heat of the summer is a key trend which looks set to stay.
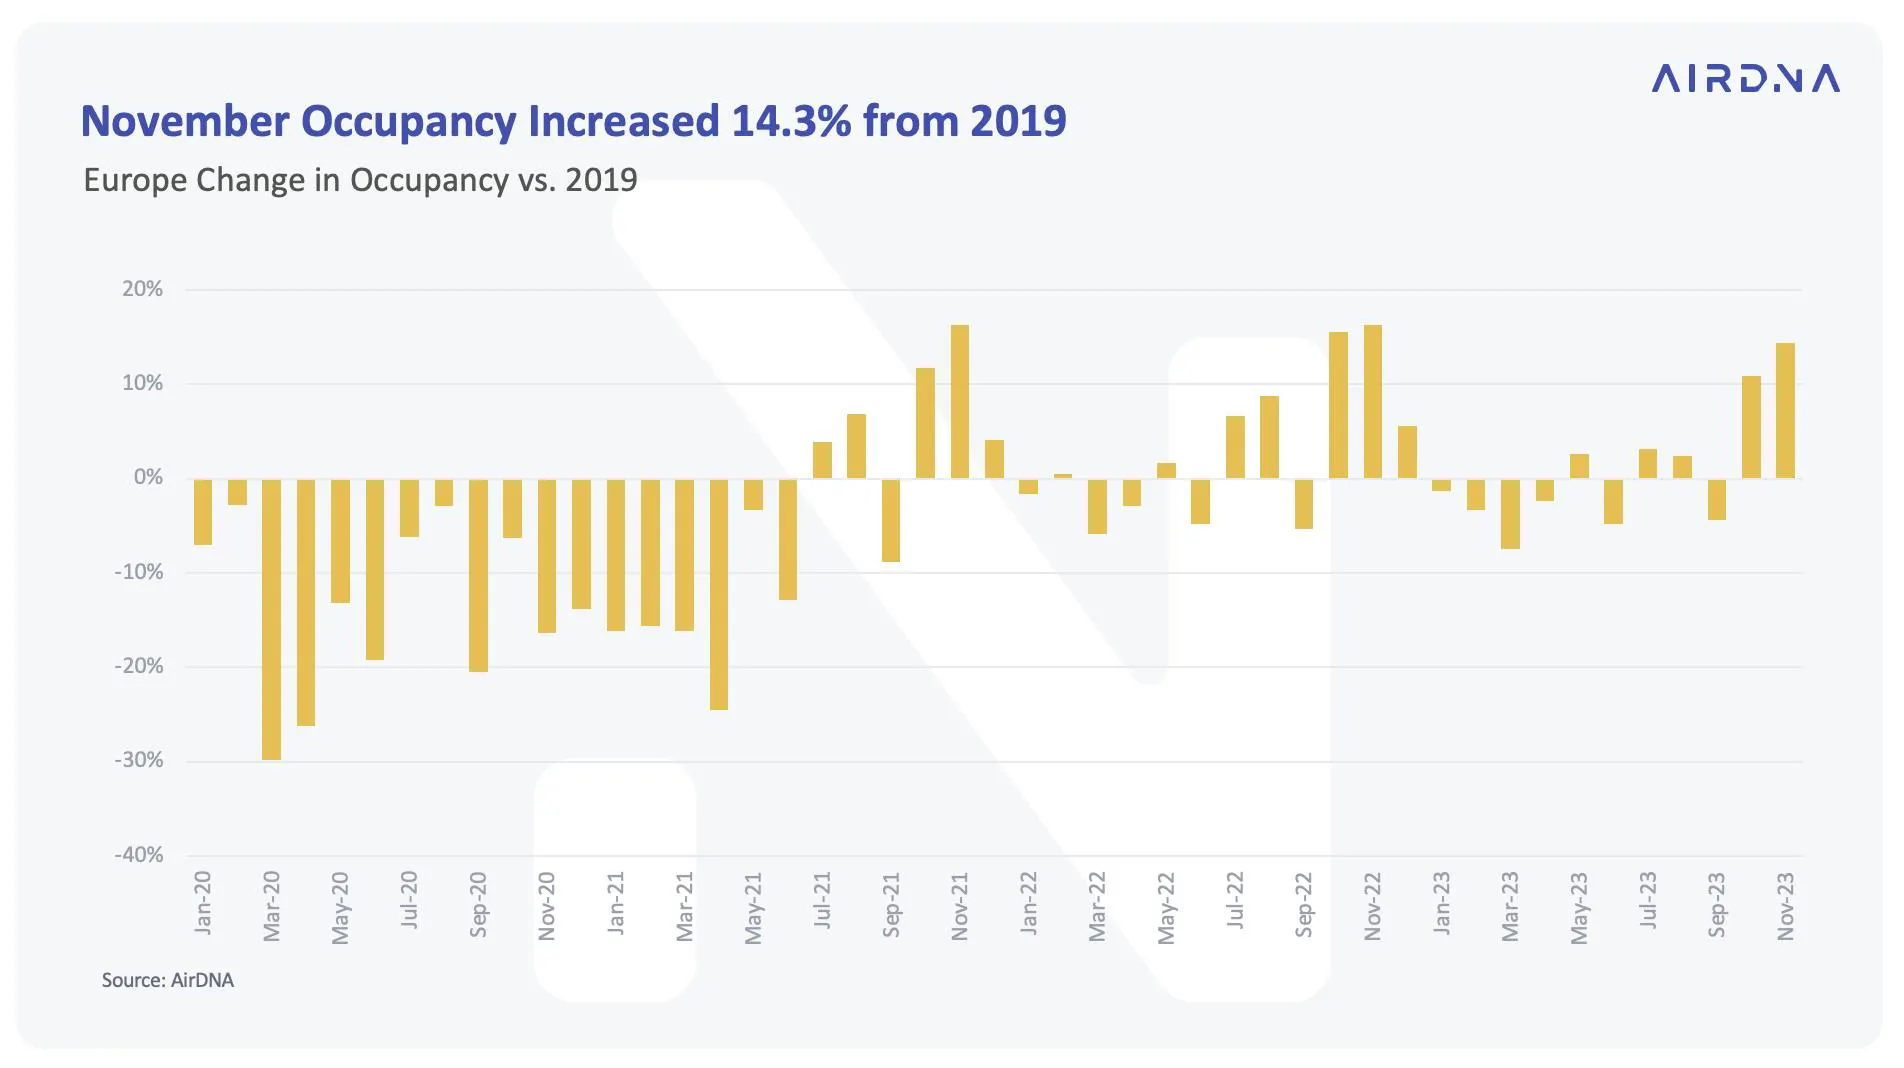
Looking at fall occupancy compared to 2019 further highlights the growth of off-season travel demand since the pandemic. September occupancy was below 2019 levels (-4.3%), but October and November set new records for occupancy, with October occupancy up 10.9% compared to 2019 and November occupancy up 14.3% versus 2019. Last year, October and November had also seen significant occupancy growth compared to 2019.
RevPAR Growth is Fueling STR Investment
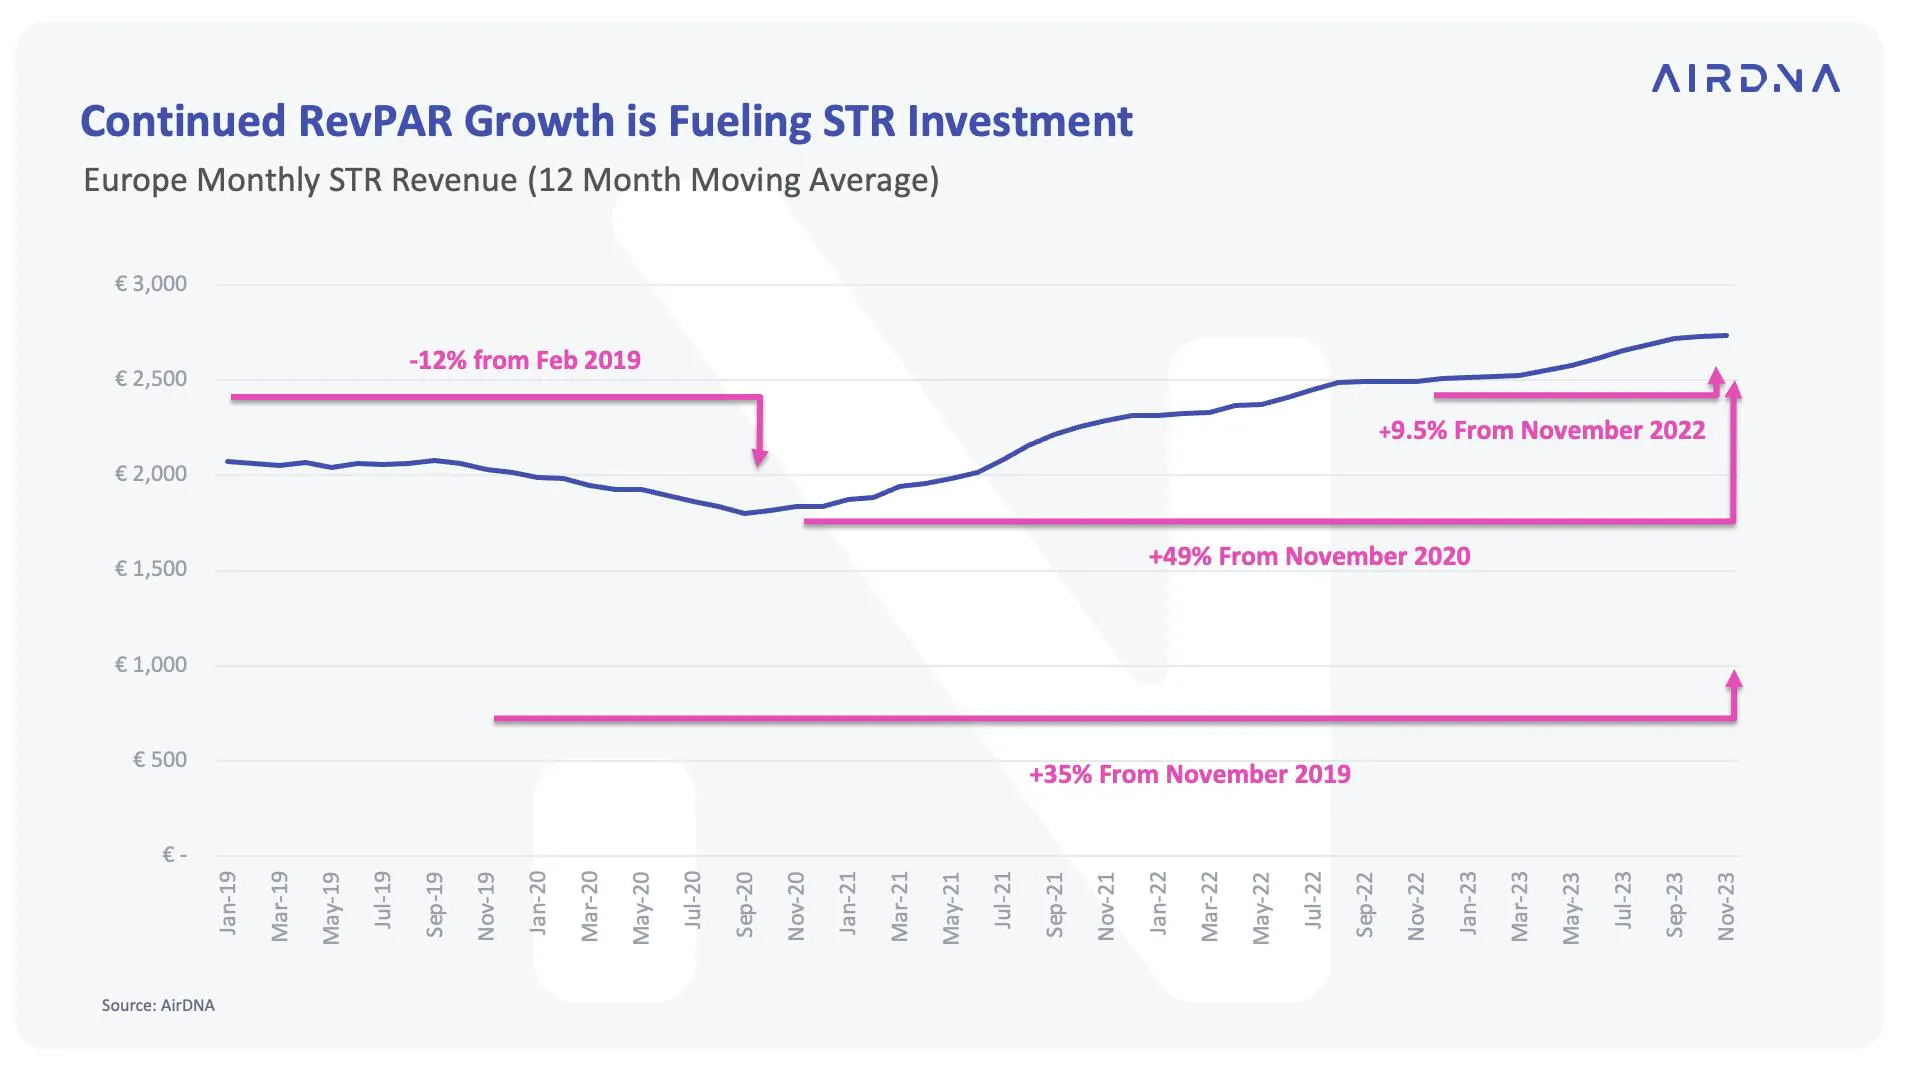
In the U.S., we’ve seen how high interest rates and declining RevPARs are slowing investment in short-term rentals. Meanwhile, in Europe, strong occupancy levels and ADR growth are fueling RevPAR growth and making high interest rates less of a deterrent.
At their lowest point during the pandemic, monthly STR revenues in Europe had fallen 12% from pre-pandemic highs. After returning to pre-pandemic levels in the summer of 2021, monthly STR revenues in Europe have been on a consistent growth trajectory. The greatest acceleration in growth was seen between the summer of 2021 and the fall of 2022. As demand recovered faster than supply, occupancy reached record heights, and monthly STR revenues shot up 10-25% YOY. These high revenues tempted more people into joining the STR market, and so over the last year, supply has caught up to demand, and revenue growth has slowed, but YOY growth in monthly STR revenues has averaged an impressive 8.5% this past year. November 2023 reached a new record for revenue growth since 2019, as monthly STR revenues reached 2,733 €, a 35% increase from November 2019, when monthly STR revenues were hovering around 2000 €, and a 9.5% increase from last November, when monthly STR revenues were nearer 2500 €.
Listing growth this fall has shown that STR investors are eagerly entering the STR market despite an unfavorable lending environment. Interest rates set by the European Central Bank (ECB) remain elevated at 4%, and it remains to be seen how long the ECB will continue to hold interest rates where they are at. But it’s clear that as long as RevPARs continue their upward growth, STR investors are seizing the opportunity to meet demand.
Fall Occupancy Exceeds 2019 Levels, but Falls Short YOY
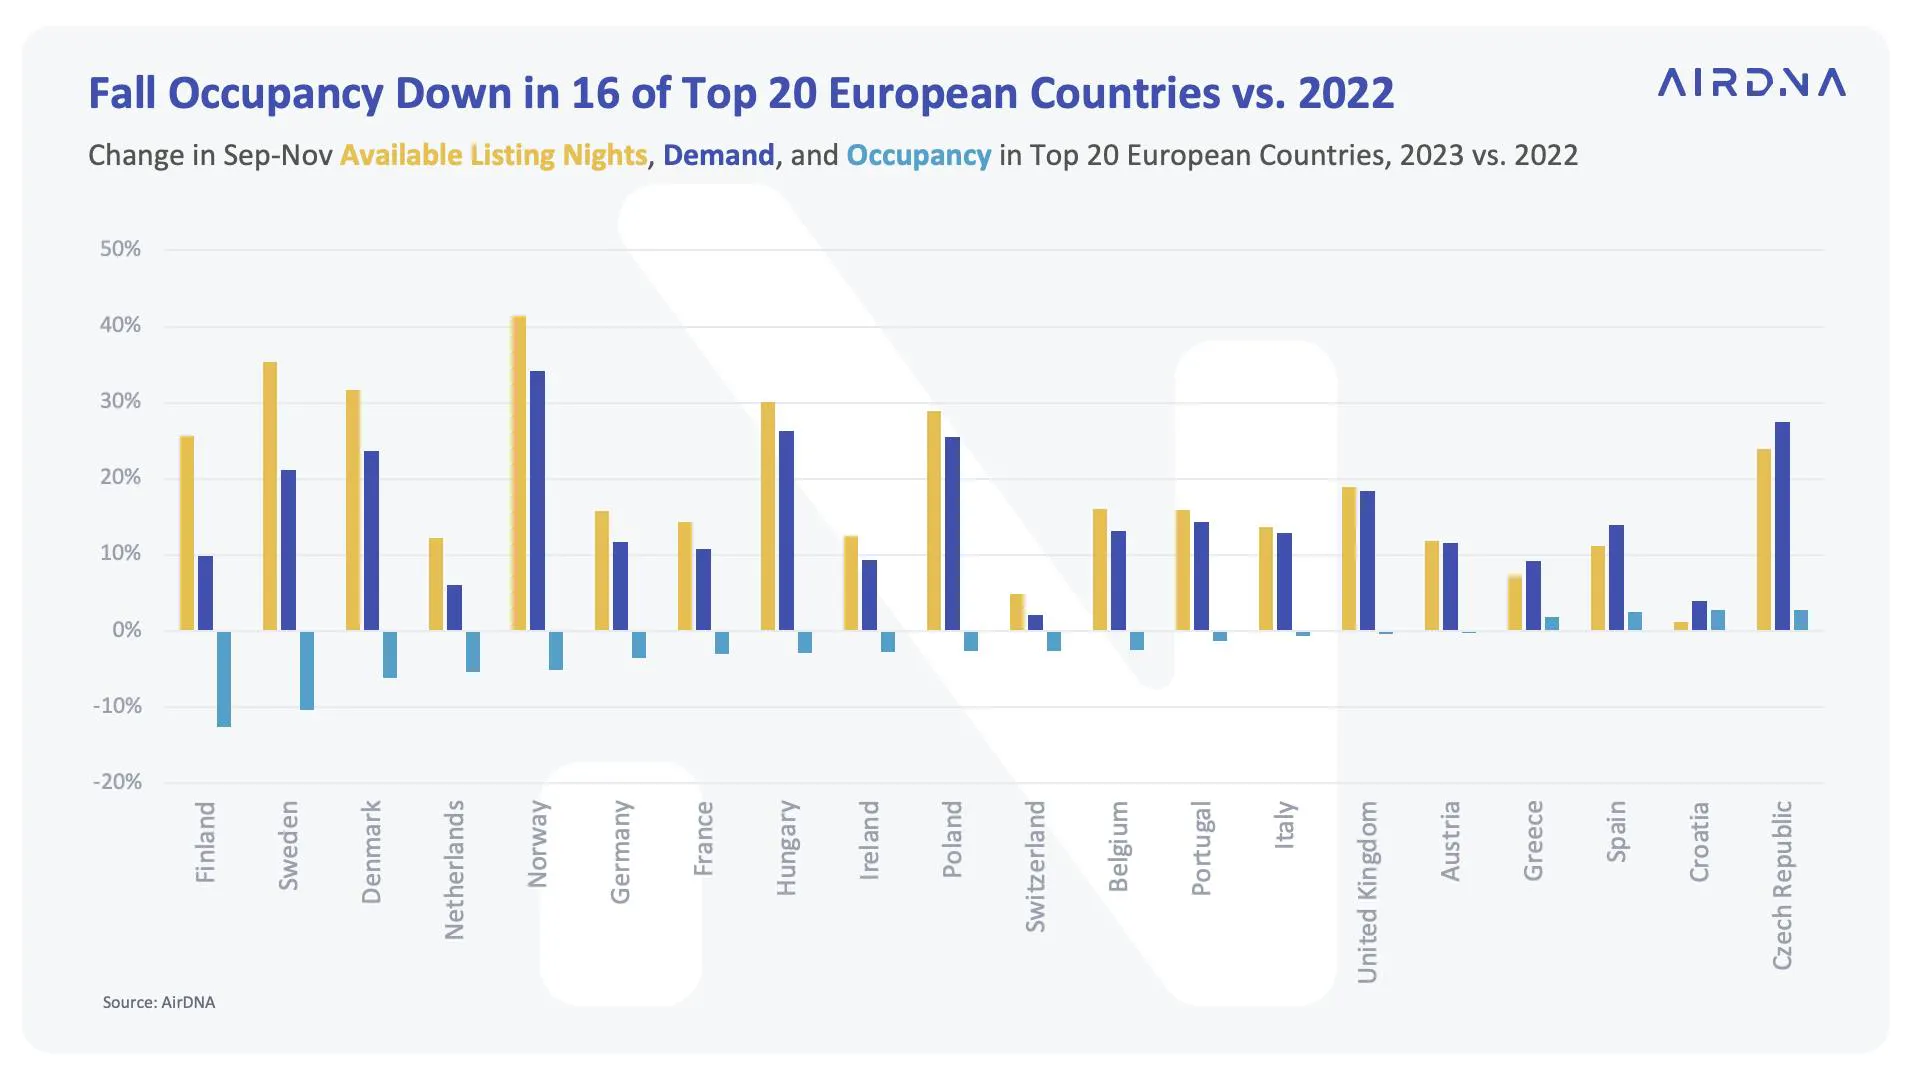
Among the top 20 European countries, occupancy was down YOY in 16 countries this fall. Nordic countries saw the largest occupancy dips, with occupancy down more than 10% in Sweden (-10.5%) and Finland (-12.6%) and declining more than 5% YOY in Norway (-5.1%) and Denmark (-6.2%). In all four countries, supply growth continues to significantly outpace demand growth. Outside of the Nordic countries, the Netherlands (-5.4%) was also in the bottom five countries for fall occupancy performance.
A strong November set the the four countries that did see overall occupancy growth this fall apart from their peers. Croatia saw an impressive 10.9% increase in occupancy in November as available listing nights fell 10.2% compared to a 0.3% decline in demand nights. Greece also saw available listing nights dip (-2.1% YOY), but demand nights grew 6.4% YOY, enabling occupancy to jump 8.7% in November. Spain saw November YOY demand growth of 14.6% nearly double the 8.3% growth in available listing nights, driving occupancy up 5.8% YOY. In Czechia, YOY demand growth of 23.9% exceeded supply growth of 21.6%, leading to 2% YOY occupancy growth in November. For Greece, Croatia, and Spain, November was the strongest performing month in terms of YOY occupancy growth this year.
Demand Pacing Is Up 15% for the First Half of 2024
Europe is poised to start the new year strong, as current demand on the books for the first half of next year is pacing 15% higher than last year.
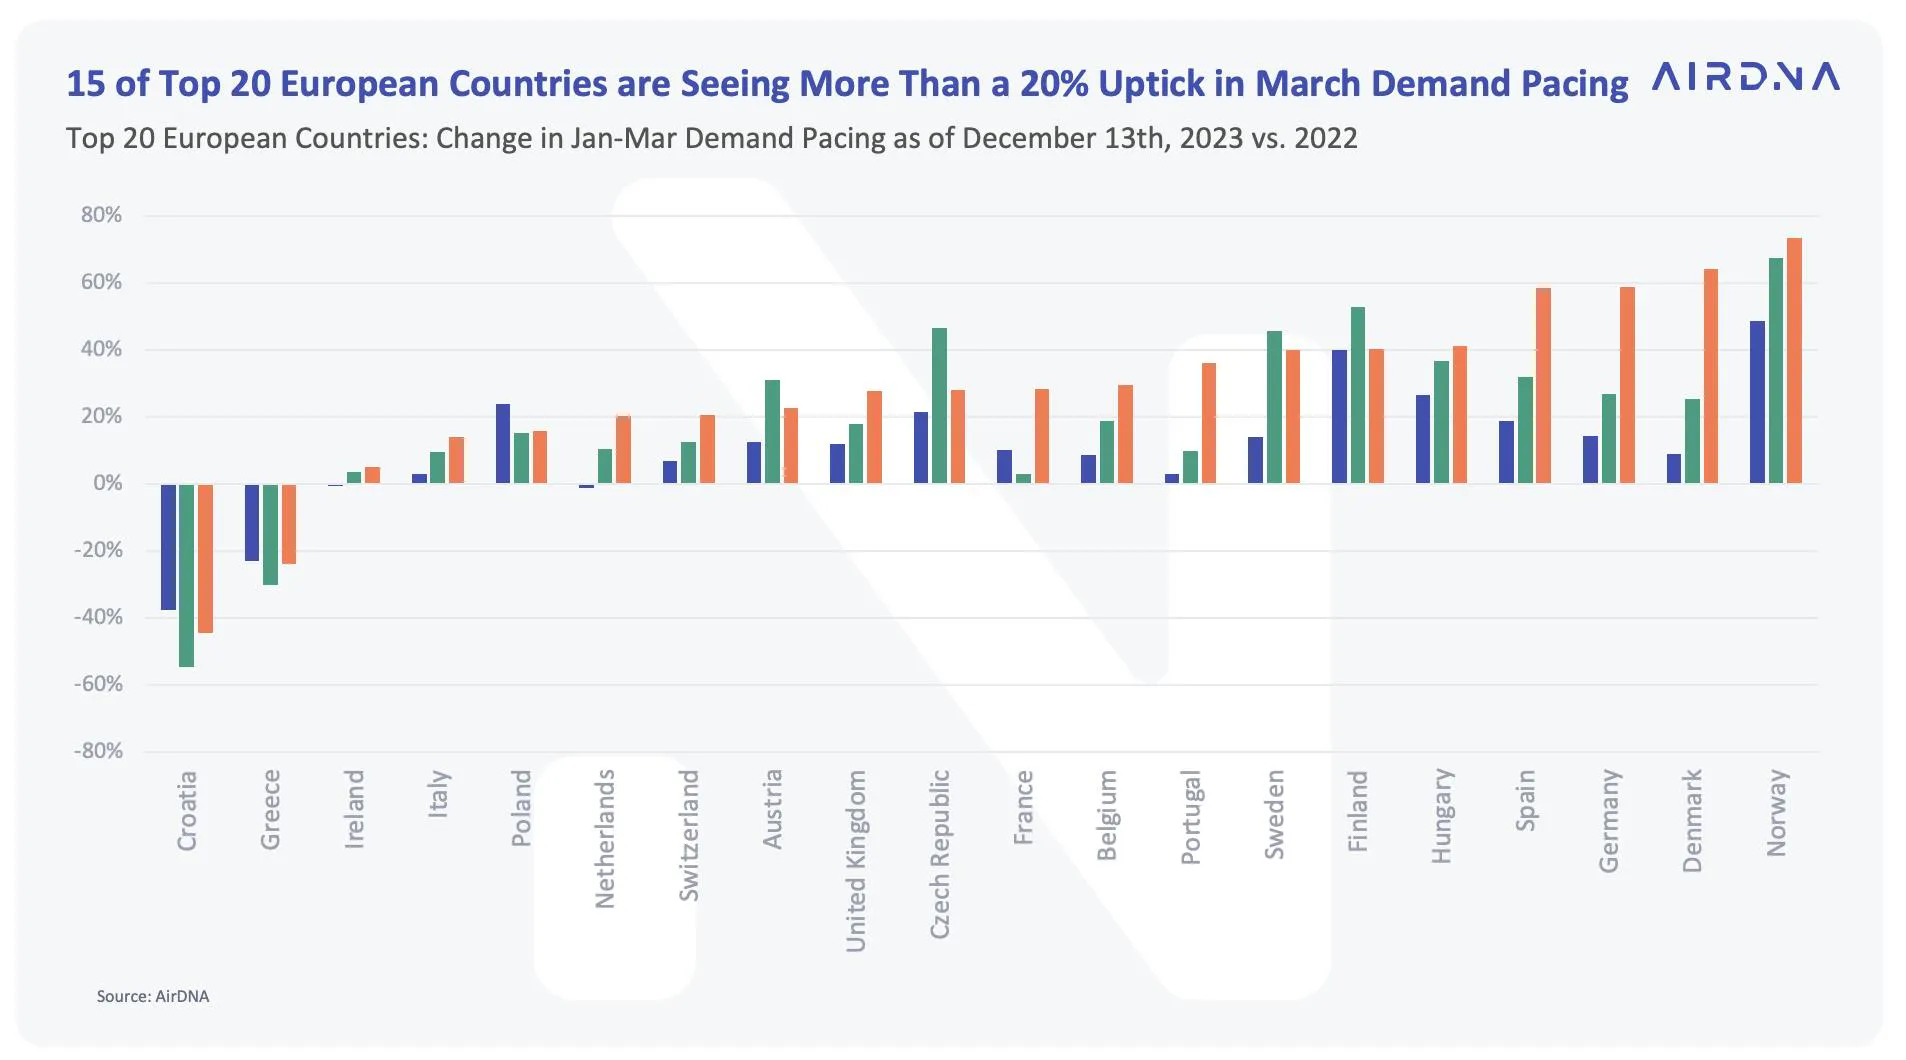
Of the top 20 European countries, Finland and Norway are leading demand pacing for January to March, with demand up 44% YOY in Finland and 61% YOY in Norway. Lagging in demand growth are Croatia and Greece, with YOY demand pacing down 43% in Croatia and 25% in Greece. With the Easter holidays landing in March this year rather than April (as in 2023), we’re seeing a significant jump in demand pacing for March, with 15 of our top 20 European countries seeing more than 20% YOY growth.
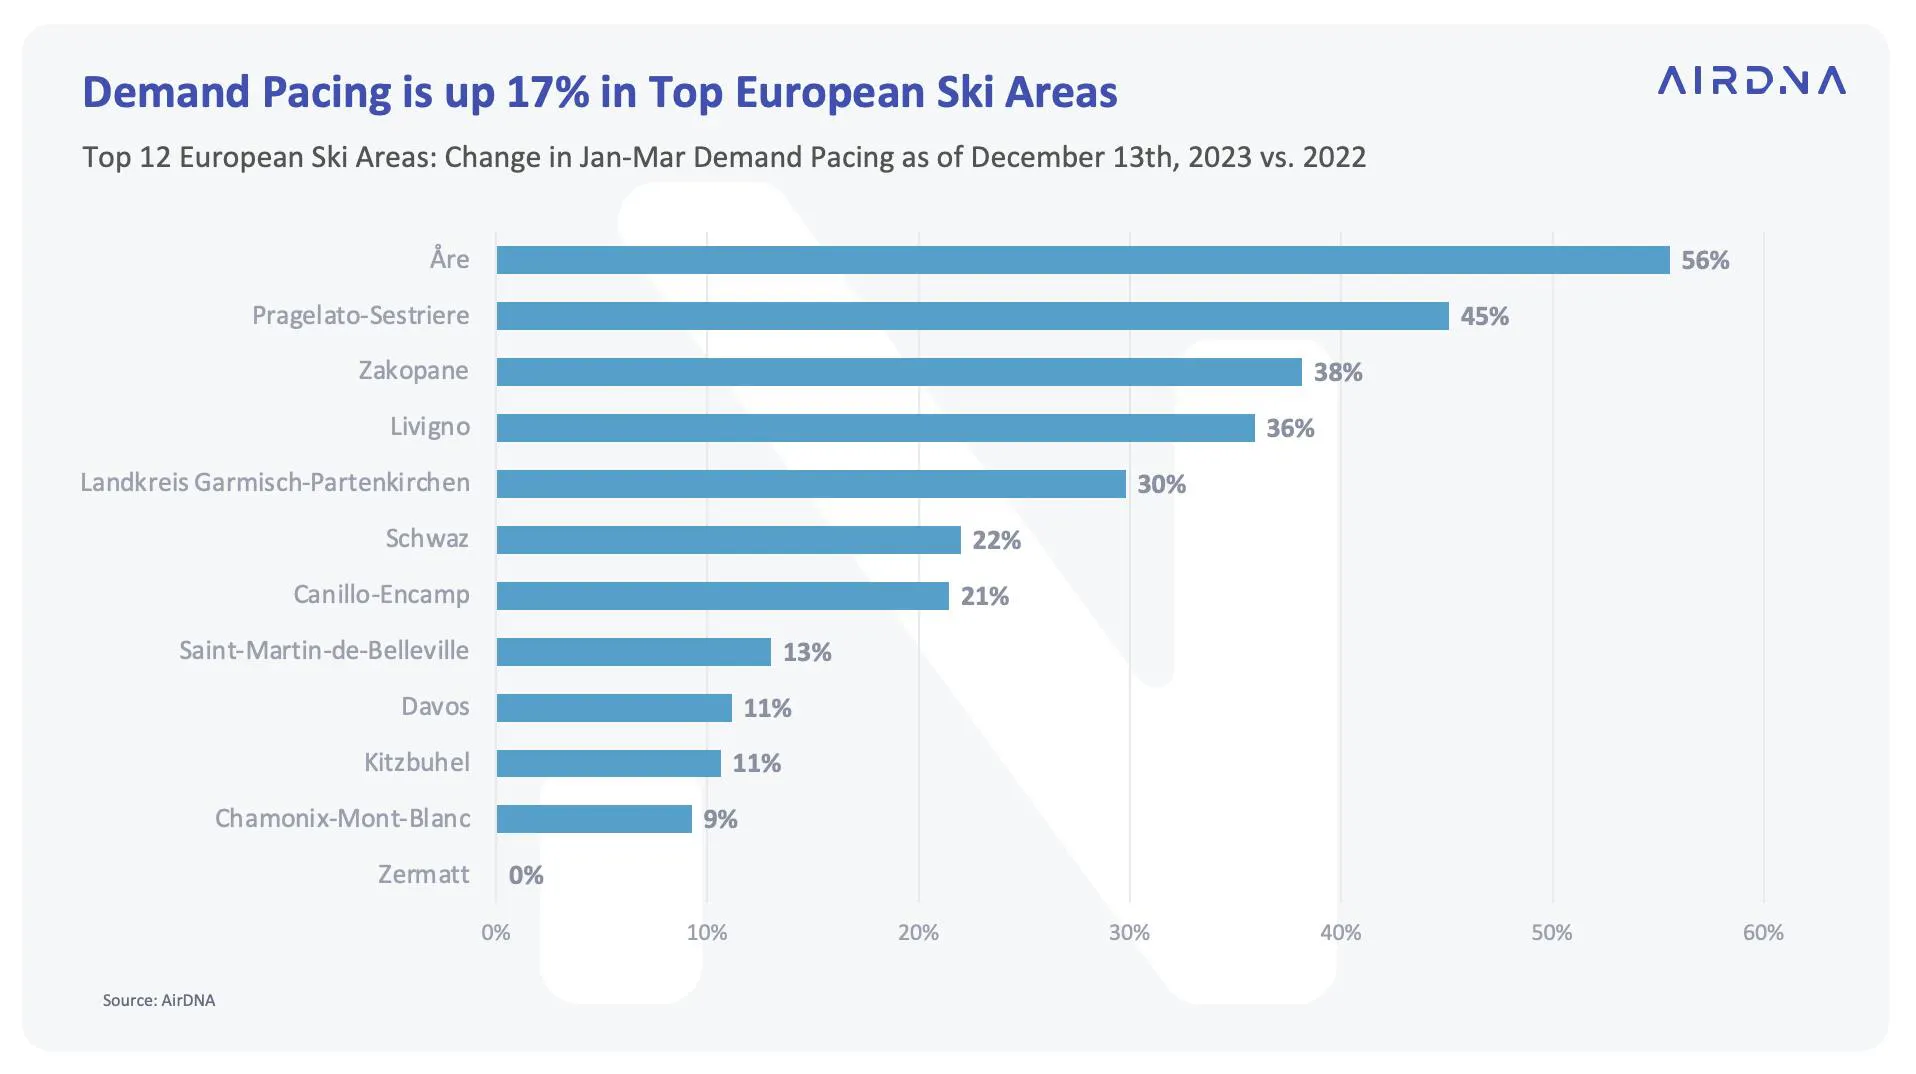
Ski season is upon us and current demand on the books for next year is showing promise. Last winter, warm temperatures and a lack of snowfall led popular ski resorts across Europe to shut down or limit operations during peak ski months. Demand across popular European ski areas still saw YOY growth, but warm temperatures limited growth potential. This year, an El Niño winter is expected to bring generous snowfall and cold temperatures to Europe, and current demand on the books is showing that skiers are ready to hit the slopes.
Among our top 12 European ski areas, Åre in the Scandinavian Mountains (+56% YOY), Pragelato-Sestriere in the Italian Dolomites (+45% YOY), and Zakopane in the Tatras Mountains (+38% YOY) are seeing the greatest YOY growth in demand pacing for January-March. Zermatt and Chamonix in the Swiss and French Alps are seeing the lowest growth in YOY demand. In both ski areas, listings have dipped in the last year, and the decline in available listing nights may be inhibiting demand growth.
Find the best places to invest with AirDNA
Rank markets based on your criteria, see the top competition, and get revenue projections for any address in the world with AirDNA
ARTICLE SUMMARY
The European short-term rental (STR) market saw significant growth and resilience in November, with strong supply growth and stable demand growth reducing occupancy’s gap with last year. The increase in listings, particularly from new additions rather than old listings returning to the market, suggests strong investor confidence despite high interest rates.
Scott Sage
Senior Vice President, Marketing & Customer Experience
Scott is an Airbnb Superhost and industry pro, having founded Home Base BnBs—a short term rental management company that scaled to 200+ units. Scott combines his experience and passion for hosting to empower AirDNA customers' success. When he's not thinking about STRs, he is hiking, playing basketball, or playing pickleball.
