Short-Term Rental Material Participation Playbook for 2025
Published: August 28, 2025
Last updated: September 25, 2026
Bram Gallagher
Key Takeaways
- You’ll need to pass the material participation test to claim those juicy 2025 tax breaks from the OBBA, like 100% bonus depreciation and the QBI deduction,
- Short-term rental material participation means you’re actively involved in managing the property on a regular, continuous, and substantial basis.
- You must pass one of seven material participation tests to qualify, but you’ll need to back up your claim with documentation.
You’ve probably heard the buzz. 2025 is shaping up to be a big year for short-term rental (STR) taxes.
The One Big Beautiful Bill Act brought back full bonus depreciation and locked in the qualified business income (QBI) deduction for good. That means hosts have a real chance to write off major expenses and keep more of what they earn.
However, there's one thing standing between you and those big tax savings: whether the IRS sees your rental as a business or just an investment.
The key to tipping that scale? Material participation.
If you’re not actively involved in running your rental (or can’t prove that you are), you could miss out on the very deductions that make STRs so attractive right now.
In this guide, we’ll walk through what material participation means for short-term rental owners, how the IRS defines it, and how to track your involvement so you’re set up for success this tax year.
What Is Short-term Rental Material Participation?
Short-term rental material participation is the IRS's way of determining if you’re actively involved in managing your rental property or simply collecting passive income. Whether you meet the IRS’s material participation rules determines if your STR qualifies for the most valuable tax benefits available.
To qualify, your involvement must be regular, continuous, and substantial. The IRS outlines seven specific tests to define this participation, including things like spending over 500 hours per year or handling most of the work yourself.
Material participation is especially important for STR owners because it’s one of two requirements for using the short-term rental tax loophole, a carveout that allows certain STR income to qualify for business-level tax treatment:
- Short stays: Your average guest stay must be seven days or fewer.
- Material participation: You must be actively involved in managing the property, as defined by one of the IRS’s seven tests.
Meet both and your short-term rental activity may be treated as a trade or business, not just passive rental real estate. In the wake of the Big Beautiful Bill, that distinction matters more than ever to unlock enhanced deductions like 100% bonus depreciation and the QBI deduction.
The 7 Short-Term Rental Material Participation Tests
You don’t need to meet all the IRS tests for material participation to qualify your short-term rental income as nonpassive: just one.
That’s right. Passing any one of the seven tests is enough to treat your activity as a trade or business activity for tax purposes. The key is to choose the one that best matches how you operate your property and to track your hours and involvement carefully.
Here are the IRS’s seven tests for material participation in rental property activities:
1. You participated more than 500 hours during the tax year.
This is the most straightforward test for hands-on operators. All time counts: booking management, cleaning, maintenance, guest messaging, and more.
2. Your participation constituted substantially all of the participation in the activity.
If you're doing nearly everything yourself (and using little to no outside help), this test might be for you—even if you didn’t hit 500 hours.
3. You participated more than 100 hours, and no one else participated more than you.
This is often the most accessible test for STR owners who use some help but still do most of the heavy lifting.
4. You participated more than 100 hours across multiple significant rental activities.
This test allows you to combine similar rental real estate activities (like multiple properties) if each one on its own wouldn’t qualify, but together, they add up.
5. You materially participated in five of the last 10 tax years.
This “experience-based” test rewards consistency. If you’ve been actively managing rentals for years, this can be your path.
6. You materially participated in any three prior years for personal service activities.
Less commonly used by STR owners, but useful if your work history includes real property trade or service businesses.
7. Based on all the facts and circumstances, you participated in the activity on a regular, continuous, and substantial basis.
This one’s tricky. It requires thorough documentation and is often harder to defend in an audit. Best used with guidance from a tax pro.
Each of these tests has different implications depending on how many properties you own, how much you outsource, and how much time you log annually. However, they all point to the same outcome: proving you’re more than a passive investor.
If you’re a material participant, you’re considered to be actively managing your short-term rental like a business, and that’s what qualifies you for the biggest tax advantages.
How to Choose the Best Material Participation Test for Your STR
You only need to pass one of the IRS’s seven tests to qualify as a material participant, but choosing the one that actually matches how you operate your STR is key. Use the guide below to find your best fit.
If you manage your STR like a full-time job
Choose Test #1: You participated more than 500 hours. Ideal for year-round hosts who regularly handle guest messaging, maintenance, cleanings, and pricing.
Example: You log time almost daily and consistently spend 10+ hours a week on operations.
If you do almost everything yourself
Choose Test #2: You did substantially all the work. Even without 500 hours, this test works if you personally manage the bulk of activity—without much outside help.
Example: You clean the unit, respond to guests, and fix issues without using a co-host or property manager.
If you use help but still do more than anyone else
Choose Test #3: You participated over 100 hours and more than any other person. A practical fit for hosts who delegate tasks but remain the primary operator.
Example: You outsource cleaning but handle bookings, guest messaging, and vendor coordination yourself.
If you manage multiple properties but split your time
Choose Test #4: You spent over 100 hours across significant combined activities. This test lets you combine time across properties to show significant participation activity overall.
Example: You spend 40 hours on one STR, 35 on another, and 30 on a third.
If you used to be heavily involved, but not recently
Choose Test #5: You materially participated in 5 of the last 10 years. A good fit for seasoned hosts who’ve stepped back but have a strong history of participation.
Example: You managed every aspect for five years, then hired help more recently.
If your past work was in a real estate or service field
Choose Test #6: You materially participated in any 3 prior years of personal service. Best for those who previously worked in a real property trade or business.
Example: You were a contractor, leasing agent, or interior designer before hosting STRs.
If your involvement is meaningful but harder to quantify
Choose Test #7: Based on facts and circumstances. Requires proof that your involvement is regular, continuous, and substantial. Use only if the others don’t apply.
Example: You manage a seasonal STR with intense hands-on work during peak months but lower hours overall.
Choosing the right test and keeping clear records is what helps the IRS view your short-term rental as a business.
Common mistakes when choosing a material participation test
Choosing the right material participation test isn’t just about what sounds right. It’s about what you can prove. Many STR owners get tripped up by the same few missteps:
- Guessing your hours instead of tracking them. The IRS needs documentation, not estimates.
- Choosing a test that’s tough to justify. Some tests rely on subjective standards like “substantially all”—hard to defend if others pitch in.
- Overlooking simpler, time-based options. Tests #1 and #3 are more concrete and often easier to substantiate.
- Assuming one test fits everyone. Your property setup, service level, and involvement all matter—what works for a DIY host won’t fit someone with a co-host or cleaner.
- Forgetting to combine hours with a spouse. Joint filers can pool time, which may shift which test you qualify for.
How to Document Your Material Participation
To claim non-passive treatment (and actually keep it), your records have to do more than exist. They need to tell a clear, consistent story of how you operate your short-term rental as a business.
Records to keep
Think beyond hour counts. The IRS is looking for what you did, how often, and why it mattered. Solid documentation includes:
- Time logs tied to specific, operational activities (not just “admin”)
- Booking platform messages showing direct guest interaction
- Receipts or invoices tied to maintenance or property decisions
- Contracts with cleaners, co-hosts, or vendors (to show your role vs. theirs)
- Notes on pricing strategy, guest experience upgrades, or other business calls
Tools & methods for tracking
Choose tools that fit how you actually work, not just what looks good on paper:
- Use a calendar to pre-schedule and reflect actual tasks
- Track your hours in real time with apps like Toggl, or log your time retroactively with details
- Store files (screenshots, receipts, messages) in a dated cloud folder for each tax year
- Set a recurring reminder to log activities weekly, otherwise accuracy fades fast with time
What to have ready in case of an audit
If the IRS reviews your return, they’ll look beyond your hour totals. Be prepared to show:
- Credibility: Do your reported hours make sense for the type of property and level of involvement?
- Consistency: Are your logs backed up by other records like emails, invoices, or booking activity?
- Classification: Does how you file your Airbnb income (such as Schedule C or E) match the way your rental operates?
What's the Difference Between Active vs. Material Participation?
If you’re researching how to qualify your short-term rental income as nonpassive, you might come across the term active participation in rental real estate. If that’s left you wondering how it’s different from material participation, you’re not alone.
These terms sound similar, but they’re not interchangeable. In fact, they apply to two very different tax situations.
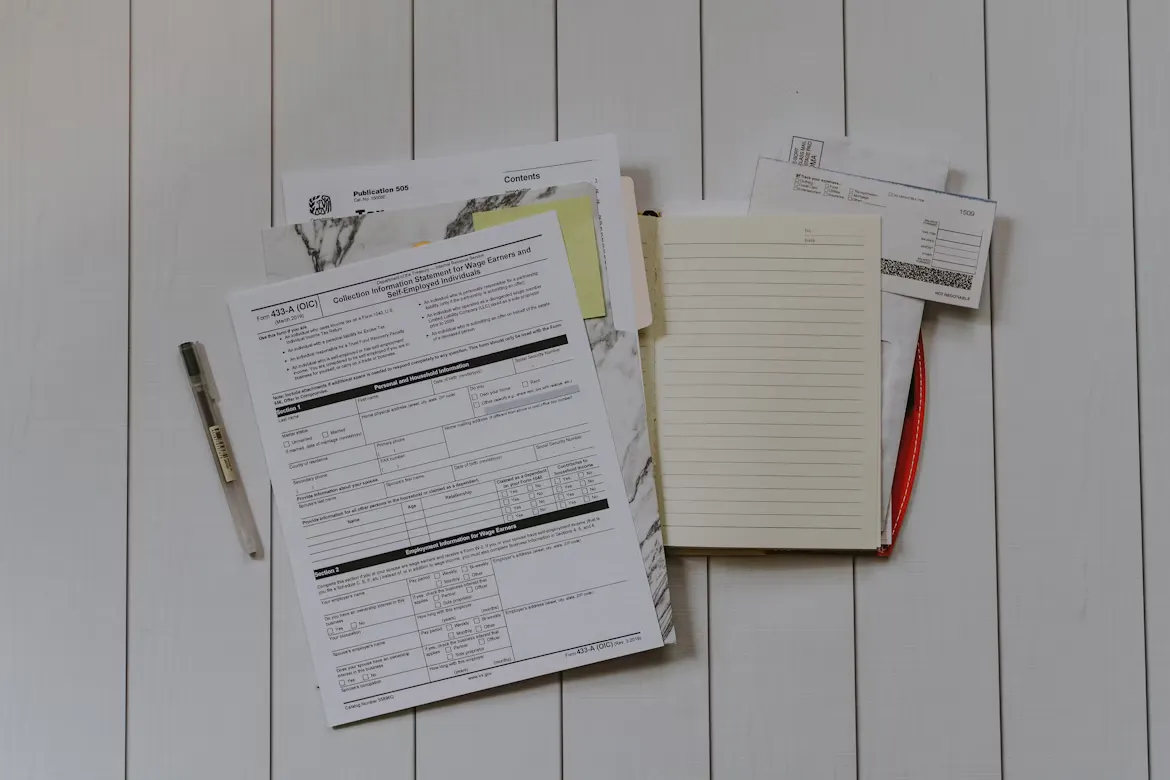
Active participation is a lower bar. It means you're involved in decision-making for your rental, like setting prices, approving guests, or hiring a cleaner. If you meet this standard, the IRS may let you deduct up to $25,000 in passive losses. However, this deduction phases out completely once your income hits $150,000. Your rental activity is also still considered passive, so it doesn't qualify you for bonus depreciation or the QBI deduction.
Material participation, on the other hand, is what actually reclassifies your short-term rental as a trade or business. This is the one that matters if you're trying to access the short-term rental tax loophole and claim business-level deductions. To qualify, you need to meet one of the IRS’s seven material participation tests, such as spending over 500 hours a year managing your property or doing most of the work yourself.
So why do these two terms get mixed up?
Because they both entail “being involved” in your rental. The difference is that material participation is the gateway to treating your STR income as nonpassive and unlocking the biggest tax benefits.
Just remember: active participation rules apply when you're deducting limited passive losses. For business-level tax benefits (like the ones available in 2025), the IRS looks to material participation instead.
Steps to Claim Material Participation
Claiming material participation requires aligning your operations with how the IRS defines a real, ongoing business. Here’s how to document the work you’re putting into your STR business, so that you’re ready if the IRS comes knocking:
1. Calculate your average stay length.
Calculate your average stay length to confirm whether your rental qualifies for the short-term rental tax loophole. This loophole only applies if your average guest stay is seven days or fewer, making your property exempt from the typical passive rental real estate rules. Once that’s established, the next requirement is proving that you materially participate in the operation of this business. Without meeting both conditions, your STR income stays passive and the best tax benefits remain out of reach.
2. Choose the material participation test that reflects your reality.
Are you managing guest communications, coordinating cleanings, and adjusting pricing yourself? Then time-based tests like #1 (500+ hours) or #3 (100 hours and more than anyone else) may fit best. The right test should match both your involvement and your ability to prove it.
3. Log activities that show you're actively managing.
The IRS isn’t looking for vague “management time.” They want to see real, operational decisions: responding to guests, scheduling repairs, handling turnovers. Documenting the nature of your work is just as important as the total hours.
4. Leverage spousal participation, if applicable.
For joint filers, your spouse’s hours count toward the total. Cleaning help, supply runs, even assisting with guest check-ins. If it’s meaningful involvement, it matters.
5. Build documentation with the audit in mind.
Keep your hour logs, receipts, platform messages, and service contracts in one place. Aim to show consistency across your tax filings, your claimed participation level, and the services your listing actually provides.
6. Partner with a CPA who understands STR nuance.
Not all tax professionals are familiar with the distinctions between rental real estate activities, the short-term rental loophole, and material participation. Work with one who is. Ideally, connect with them before tax season starts.
Treating your rental like a business means managing it and proving it with that same level of care. The more deliberately you operate and track your involvement now, the stronger your position will be when it’s time to claim your tax benefits.
FAQs
What does it mean to materially participate in a business?
To materially participate in the operation of a business, the IRS requires that your involvement be regular, continuous, and substantial. For STRs, this means meeting one of seven material participation rules, such as spending over 500 hours managing the property or doing most of the work yourself.
What does materially participate mean for taxes?
If you meet the IRS definition of material participation, your short-term rental income is treated as nonpassive. That opens the door to bigger deductions, like 100% bonus depreciation and the QBI deduction, without income-based limits.
What is passive and nonpassive income?
Passive income comes from investments where you don’t materially participate, like a long-term rental managed by a property manager. Nonpassive income means you’re actively involved in the business, qualifying you for broader deductions. STRs can qualify as nonpassive if they meet the short-stay rule and pass a material participation test.
ARTICLE SUMMARY
Big tax perks are back for short-term rental (STR) owners in 2025, but only if you qualify as a material participant. This guide breaks down what material participation means, how to pass one of the IRS’s seven tests, and what STR hosts need to track to unlock nonpassive income treatment and maximize deductions.
Bram Gallagher
AirDNA Director of Economics and Forecasting
Bram Gallagher is an Economist at AirDNA, specializing in uncovering insights that drive smarter short-term rental decisions. He put his Ph.D. in Economics from the University of Georgia to work researching and forecasting hotel data with CBRE prior to joining AirDNA, as well as teaching economics at a number of universities. In his spare time, Bram enjoys making wooden furniture with hand tools.