

 Calculate Revenue
 Research Markets
 Find For Sale Properties
 Compare My Listing
 STR Revenue Calculator
 Custom Comp Sets
 Submarket Insights
 Custom Search Filters
 Rate Recommendations
 Performance Benchmarking
 Competitor Comparison
 Owner Contact Details
 Property-level performance data
 Tourism Insights
 Real Estate Investment Analytics
 About Us
 Sales
 Support
 Press
Boost Airbnb Returns with the Short-Term Rental Tax Loophole
Published: September 11, 2025
Last updated: September 25, 2026
Bram Gallagher
Key Takeaways
- The short-term rental tax loophole allows non-professional property owners to reduce their taxable income by reclassifying rental income and offsetting it with depreciation and deductible expenses.
- Property owners must meet one of the six IRS exclusions and pass the material participation test to qualify.
- The loophole should be combined with other tax strategies, such as cost segregation analyses, to maximize savings.
Short-term rental investments can be incredibly profitable, but the tax side of things can be daunting. As a property owner, you're probably on the lookout for ways to lighten your tax load and boost your earnings.
That's where the short-term rental tax loophole comes in. This powerful provision in the tax code could let you classify your rental income a little differently, enabling you to offset it with other active income sources.
Let’s break down the short-term rental tax loophole, how you can qualify for it, and why it's a game-changer for property owners like you.
What Is the Short-Term Rental Tax Loophole?
The short-term rental tax loophole is a special provision in the tax code that helps owners of short-term rental (STR) properties save on taxes. It allows STR owners to reduce their taxable income significantly, even if they aren't professional real estate investors. Often referred to as the 'Airbnb tax loophole' or 'STR tax loophole,' this strategy has become increasingly popular among vacation rental owners looking to maximize their investment returns.
Typically, only real estate professionals can offset their rental income with losses from other active income sources like wages or business profits. However, this STR tax loophole permits non-professional property owners with short-term rentals to qualify for similar benefits if they meet certain criteria. This is particularly valuable for Airbnb hosts and other vacation rental owners who might not qualify as full-time real estate professionals.
This reclassification leads to substantial tax savings by enabling deductions for various expenses associated with managing rental properties. Deductible expenses that feed into your net operating income might include:
- Mortgage interest
- Property management fees
- Property taxes
- Maintenance and repairs
- Utilities (electricities, water, internet, etc)
- Insurance premiums
- Advertising and marketing costs
- Supplies, furnishings, and amenities for guests
Additionally, vacation rental owners can benefit from depreciation, spreading the cost of the property over several years to further reduce taxable income.
For more information on how rental income is taxed when you have a mortgage, check out our guide.
How to Qualify for the Short-Term Rental Tax Loophole
Property owners need to meet specific criteria that demonstrate active participation to reclassify their rental income as non-passive. Reclassifying rental income in this way allows property owners to offset vacation rental income with other active income sources, resulting in substantial tax savings.
You must meet any of the six IRS exclusions below and pass the material participation test to qualify for the short-term rental tax loophole. Understanding both components is crucial for properly implementing this tax strategy and withstanding potential IRS scrutiny.
IRS Exclusions for Non-Passive Income
According to the tax code, here are six scenarios where rental property income can be excluded from the passive category:
1. Short stays and the 7-day rule
The average duration of guest stays is seven days or less. This is commonly known as the '7-day rule' and is one of the most frequently used qualifications for the STR tax loophole.
2. Shorter stays with services
The average guest stay is 30 days or less, and substantial personal services, similar to those provided by a hotel, are offered by or on behalf of the property owner. Personal services could include daily housekeeping, meal services, access to a vehicle, or vouchers for local attractions.
3. Extraordinary personal services
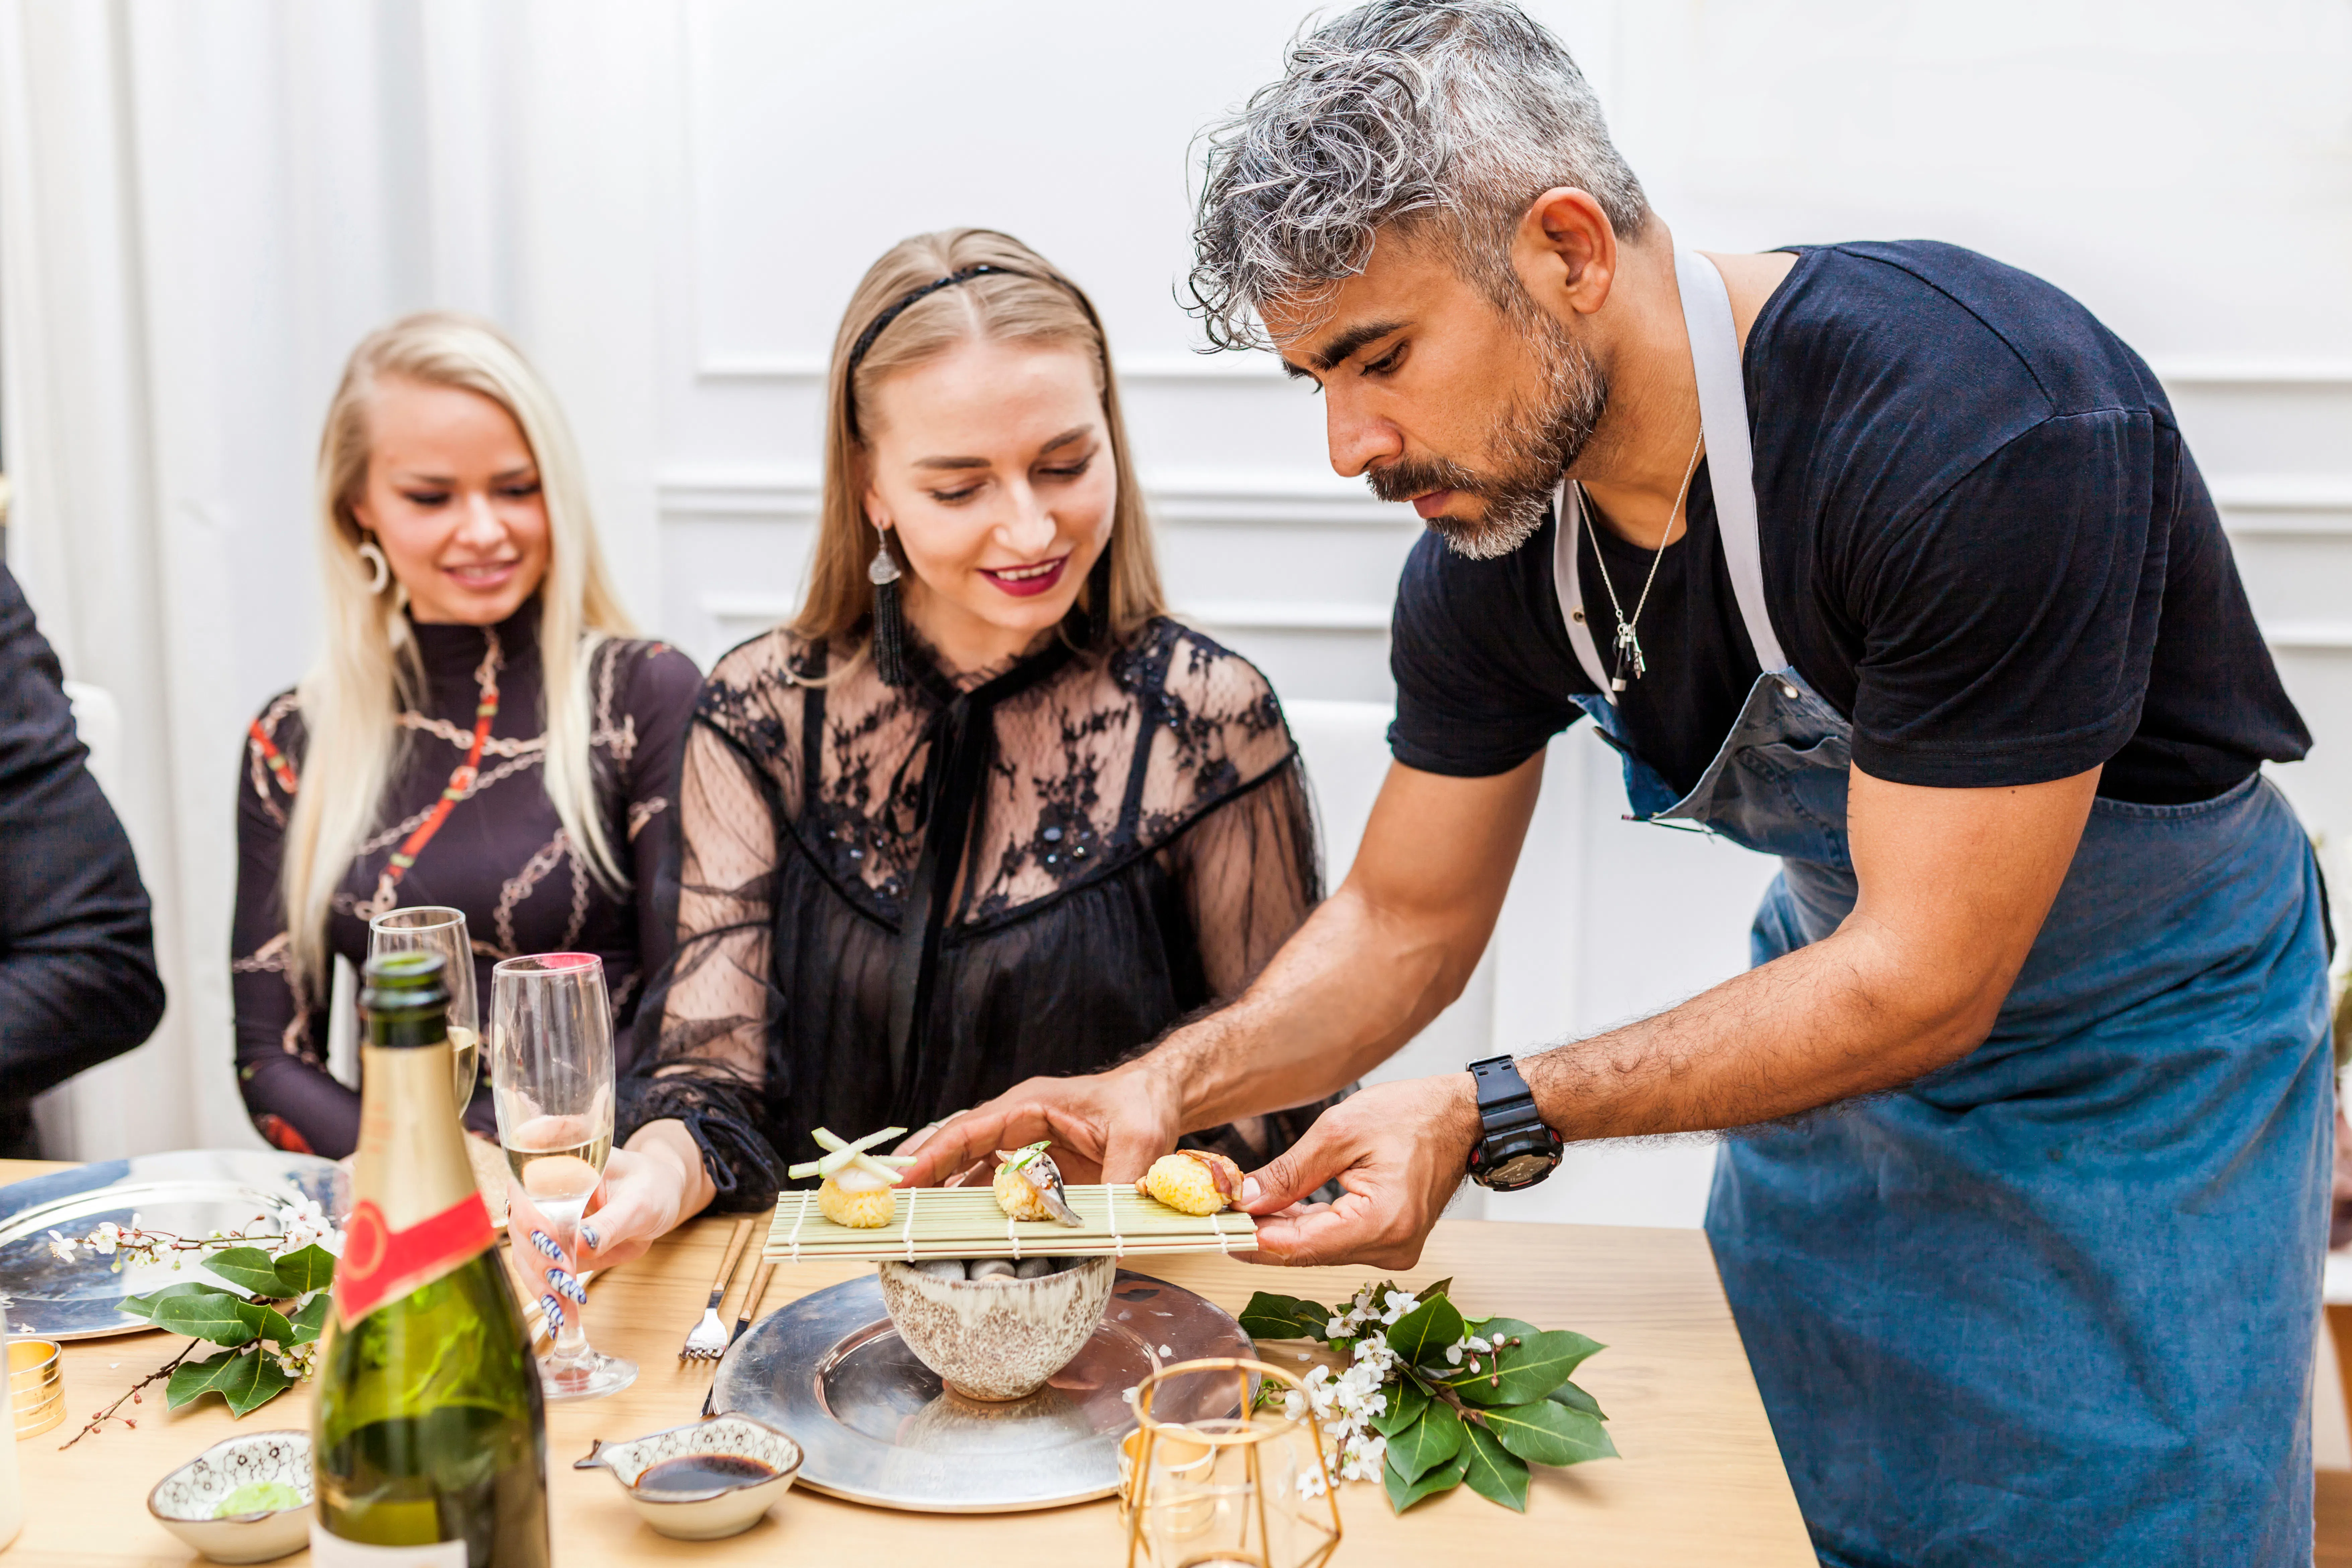
If you provide exceptional personal services in connection with making the property available for use, regardless of the average duration of guest stays, the rental income can be considered non-passive. A good example might be a luxury Airbnb that offers a private chef and private tours.
4. Incidental rentals
The rental of the property is secondary to a non-rental activity conducted by the taxpayer.
Suppose you own a winery that offers wine tasting and tours. Occasionally, you rent out a small guesthouse on the property to visitors. Since the primary business is the winery operations, and the guesthouse rental is secondary or incidental to this primary activity, the income from the rental can be considered non-passive.
5. Business hours
The property is typically available for nonexclusive use by various customers during defined business hours.
Imagine you own a property that has a designated gathering space that can be rented out as a venue during regular business hours. Even if you have short-term renters occupying the other parts of your property, you could still qualify for the short-term rental tax loophole under this scenario because your property isn’t exclusively used by one entity.
6. Partnership or S corporation
The property is used in activities carried out by a partnership, S corporation, or joint venture in which the taxpayer has an ownership interest, and these activities are not classified as rental activities.
Suppose you are a partner in a tech startup that occasionally uses a property you own for company retreats and team-building activities. Since the property use is integral to the business operations of the startup (a non-rental activity), the income can be considered non-passive.
The material participation test
If your rental activity fits any of the above exclusions, the last hoop to jump through to qualify for the loophole is the material participation test. The IRS has established specific criteria to determine whether a taxpayer meets the material participation standard:
- 500-Hour Rule: You participated in the rental activity for more than 500 hours during the tax year.
- Substantially All Participation: Your involvement in the rental activity is almost all the work done for the business, including by non-owners.
- 100-Hour Rule: You participated for more than 100 hours during the tax year, and that participation is not less than any other individual's participation.
- Significant Participation Activities: This criterion looks at your participation across multiple business activities, not just the rental property. You must spend more than 500 hours in total on all significant participation activities you are involved in, including but not limited to the rental property.
- Previous Material Participation: You materially participated in your short-term rental business for any five of the last ten tax years.
- Personal Service Activity: You provided personal services in connection with the rental property, and you did so for at least three of the previous taxable years. Personal services are activities that require advanced skills or education. Examples include legal, health, engineering, accounting, construction, or other professional services.
- Facts and Circumstances: Based on all facts and circumstances, you participated in the activity on a regular, continuous, and substantial basis during the year.
You only need to meet one of the seven criteria to pass the material participation test for the short-term rental tax loophole. Documentation of your participation is essential here. Keep detailed records of hours spent on property management, maintenance, guest communication, and other rental activities to support your claim. For the '100-hour test,' be sure to track not just your own hours but also hours worked by contractors, as this is a common mistake that can jeopardize your qualification.
If you pass, you can classify your rental income as non-passive. This classification is essential for leveraging the STR tax loophole and benefiting from significant tax savings.
Common mistakes when applying the short-term rental tax loophole
While the short-term rental tax loophole can yield substantial savings, many hosts overlook key factors that can nullify their benefits.:
- Exceeding the 7-day threshold: Allowing average guest stays to exceed seven days typically disqualifies rental income from being reclassified as non-passive.
- Poor documentation: Neglecting to log your hours meticulously risks audits and lost deductions, as clear records of material participation are essential.
- Excessive personal use: Extended owner stays or giving friends discounted access may push you over permissible thresholds.
- Misapplying tax strategies: Implementing cost segregation or bonus depreciation without first ensuring your property meets one of the IRS exclusions for non-passive income—essentially putting the cart before the tax-saving horse.
- DIY tax planning - Seeking help from a tax pro with STR experience can minimize mistakes while maximizing your returns.
Schedule C vs. Schedule E: Choosing the Right Tax Filing Approach
Once you've determined whether your STR income qualifies as passive or non-passive based on the IRS exclusions and material participation tests, you'll need to choose the appropriate tax form.
Schedule E is typically used for passive rental income, while Schedule C is for business income. Your classification directly impacts which one you'll use.
If you provide substantial services like daily housekeeping, meals, or concierge assistance, the IRS may view your operation as a business rather than a traditional rental, requiring Schedule C filing. This triggers self-employment tax (an additional 15.3%) but unlocks the valuable 20% Qualified Business Income deduction that can offset this cost.
Meanwhile, Schedule E filers avoid self-employment tax altogether but may have more limited deduction options. Many savvy hosts strategically position their properties to meet the seven-day rule for non-passive income classification while keeping services minimal enough to justify Schedule E filing—essentially getting the best of both worlds.
For occasional hosts, don't overlook the 14-day rule, which allows completely tax-free rental income if you rent your personal residence for 14 or fewer days annually. Given these nuances and their significant tax implications, working with an STR-experienced CPA is less an expense than an investment in maximizing your after-tax profits.
Depreciation and the Short-Term Rental Tax Loophole
Depreciation is a crucial tax strategy that allows property owners to deduct the cost of their property over time, reflecting its gradual loss of value due to wear and tear. For short-term rental (STR) property owners, leveraging depreciation can greatly reduce taxable income, making it a valuable component of the short-term rental tax loophole strategy. When implemented correctly, depreciation can result in thousands of dollars in tax savings annually.
Once rental income is reclassified as non-passive, STR property owners can leverage accelerated depreciation methods, such as:
- Bonus Depreciation: This allows for an immediate deduction of a large percentage of the purchase cost of eligible assets.
- Section 179 Expensing: This enables property owners to deduct the full purchase price of qualifying equipment and/or software purchased or financed during the tax year.
- Cost Segregation: This engineering-based approach identifies components of your property that can be depreciated over a shorter period of time, potentially freeing up thousands in immediate tax savings. More on that later!
The return of 100% bonus depreciation
When the Tax Cuts and Jobs Act (TCJA) was passed in 2017, it allowed real estate investors to take 100% bonus depreciation on eligible property. That benefit wasn’t permanent, however. Under the original law, bonus depreciation began phasing down in 2023 (80%), with a further drop in 2024 (60%), and was scheduled to shrink to 40% in 2025 before eventually disappearing.
That uncertainty is now over. Thanks to the Big Beautiful Bill, 100% bonus depreciation has been reinstated and extended. This means short-term rental investors can once again write off the entire cost of qualifying assets (like furniture, appliances, and property improvements with a recovery period of less than 20 years) in the year they’re placed in service. Here's what that means for Airbnb operators:
- Bigger, faster deductions: Rather than depreciating items over 5, 7, or 15 years, you can deduct the full cost upfront.
- Unlocks tax savings through cost segregation: With a cost segregation study, even parts of your property that would normally be depreciated over 27.5 years can be broken into shorter categories and made bonus-eligible.
- Timing is everything: The deduction is tied to the placed-in-service date. That means the sooner you furnish or improve your property (or close on a new one), the sooner you can claim the deduction.
Let's look at an example. An investor buys a property with a $400,000 depreciable basis and spends $25,000 on furniture and a hot tub. With 100% bonus depreciation in effect, they could deduct the full $25,000 in year one, plus any reclassified assets from a cost segregation study — potentially reducing taxable income by well over $100,000. Check out our comprehensive guide to bonus depreciation in 2025 for more detail.
Other Tax Strategies for Short-Term Rental Properties
Cost segregation for STR properties
A cost segregation study allows property owners to accelerate the depreciation of certain parts of their short-term rentals. This means you can take bigger tax deductions sooner by identifying and reclassifying personal property assets to shorter depreciation periods like 5, 7, or 15 years instead of the usual 27.5 years.
This involves a detailed cost segregation report, which breaks down the property into individual components like plumbing, electrical fixtures, and landscaping. Utilizing this strategy can lead to substantial upfront tax savings. For example, a cost segregation study on a $500,000 property might identify $100,000 in components that can be depreciated over 5-7 years instead of 27.5 years. This potentially results in an additional $15,000-$20,000 in tax deductions in the first year.
Accelerated depreciation benefits
Accelerated depreciation methods, such as bonus depreciation and Section 179 expensing, enable property owners to quickly write off the cost of qualifying assets. Improvements to land, property, and tangible personal property can be depreciated over shorter periods, providing immediate tax benefits.
While both Section 179 and bonus depreciation allow immediate write-offs, they have key differences. Section 179 lets you selectively choose which assets to expense (now up to $2.5 million thanks to the Big Beautiful Bill), but phases out dollar-for-dollar once you exceed $4 million in qualifying purchases. It also requires you to have taxable income to claim the deduction. Bonus depreciation, on the other hand, applies automatically to all eligible assets, has no dollar limit, and can create or increase a loss. This makes it particularly valuable for high-value properties.
Accelerated depreciation methods are especially useful for short-term rental owners who invest in property improvements and furnishings. This tax strategy helps reduce taxable income and improve cash flow early in the ownership period.
Tax deductions and credits
Maximizing tax deductions and credits is essential for lowering your tax burden. Key deductions include mortgage interest, property management fees, maintenance costs, insurance premiums, and utilities. You can also claim significant tax deductions for major repairs and improvements, leading to substantial savings.
Tips for maximizing deductions
- Track expenses: Keep detailed records of all expenses to ensure you capture every eligible deduction.
- Energy-efficient Improvements: Take advantage of tax credits for energy-efficient improvements, which can offset costs associated with making your property more energy-efficient.
- Qualified Business Income (QBI) Deduction: If your rental activity qualifies as a trade or business, you may be eligible for the QBI deduction. This powerful tax break applies to income from pass-through entities like sole proprietorships, partnerships, and S-corporations, allowing you to deduct up to 20% of your qualified business income.
Note that for QBI deductions, high-income earners (over $197,300 for single filers and $394,600 for joint/married filers in 2025) may face limitations based on the type of business, W-2 wages paid, and property basis. Even if you file on Schedule E, you might still qualify for QBI if your rental meets the IRS "safe harbor" requirements. You can meet these requirements by maintaining separate books and records and performing at least 250 hours of rental services annually.
Understanding the nuances of these tax rules can help you optimize your tax strategy and maximize the return on your STR. For anyone with short-term rentals, combining these strategies with the STR tax loophole can reduce your taxable real estate income and improve your overall financial performance.
Frequently Asked Questions
What is the short-term rental tax loophole?
The short-term rental tax loophole is a provision in the tax code that allows owners of short-term rental properties to classify their rental income as non-passive if they meet certain criteria. This reclassification allows them to offset rental income with depreciation and deductible expenses.
How do I qualify for the STR tax loophole?
Property owners must meet specific criteria, including one of the 6 qualifying scenarios related to guest length of stay or extent of services provided. STR operators must also pass the material participation test. Material participation requires you to actively manage the property and meet one of the IRS’s tests, such as spending more than 500 hours a year on the rental activity.
How can I maximize STR tax savings?
Make sure that you meet the material participation criteria to classify your rental income as non-passive. Conduct a cost segregation study to accelerate depreciation, take advantage of any remaining bonus depreciation, and keep detailed track of all deductible expenses related to your rental property. Maintain thorough documentation of your hours spent on the property, including a time log that details dates, activities performed, and duration. For the '100-hour test,' be sure to track contractor hours as well. Consulting with a tax professional who specializes in real estate can also help you navigate the complexities of taxation and choose the best tax strategy.
Are short-term rentals a good tax write off?
They can be extremely valuable for offsetting active income if you meet the criteria outlined by the IRS for short-term rentals. Your property’s losses, including depreciation, may be used to reduce tax owed on wages or business earnings. This is a major perk for high-income earners especially. Many owners generate significant paper losses that minimize their tax liability by logging participation hours, ensuring short guest stays, and tracking all expenses. Be sure to keep meticulous records of personal use to avoid disqualification. Seeking guidance from a tax advisor is crucial for maximizing these benefits.
What is the 7-day rule for short-term rentals?
The 7-day rule stipulates that the average rental period per guest should be no more than seven days to qualify for the short-term rental tax loophole. According to IRS definitions, properties meeting this criterion can often reclassify rental income from passive to non-passive, opening the door to extra tax deductions. This requirement helps align short-term rentals more closely with hotel-like operations, where rapid guest turnover is common. Make sure to calculate your average stays accurately, as going over the limit can negate these benefits. Detailed recordkeeping is essential to prove compliance.
How to maximize short-term rental income?
Beyond strategic tax planning, here's how to maximize your STR profits:
- Optimize pricing: Set competitive nightly rates and continuously adjust them based on seasonal demand patterns.
- Use data-driven tools: Platforms like AirDNA help set optimal prices based on local trends and events.
- Upgrade the guest experience: Provide extra amenities or personalized touches to justify higher nightly rates.
- Maintain property quality: Keep your rental well-maintained and respond promptly to inquiries for better reviews.
- Reinvest strategically: Put earnings back into property improvements to improve both margins and property value.
ARTICLE SUMMARY
You don't need to be a real estate professional to unlock major tax savings on your short-term rental property. Discover how to classify your short-term rental income as active to significantly reduce your taxable income and increase your profits.
Bram Gallagher
AirDNA Director of Economics and Forecasting
Bram Gallagher is an Economist at AirDNA, specializing in uncovering insights that drive smarter short-term rental decisions. He put his Ph.D. in Economics from the University of Georgia to work researching and forecasting hotel data with CBRE prior to joining AirDNA, as well as teaching economics at a number of universities. In his spare time, Bram enjoys making wooden furniture with hand tools.
