European Review July 2025: Lesser-Known Destinations Drive STR Momentum
Published: August 19, 2025
Last updated: September 13, 2025
Linda Rollins
Key Takeaways
- Listings hit a record high of 4.15 million in July, though overall growth slowed to 2.8% year-over-year (YOY).
- Luxury and upscale segments led demand growth, with 14% and 9% YoY increases respectively, especially in emerging markets like Norway and Switzerland.
- Average Daily Rates (ADR) and Revenue per Available Rental (RevPAR) growth was aided by stable inflation and strong occupancy.
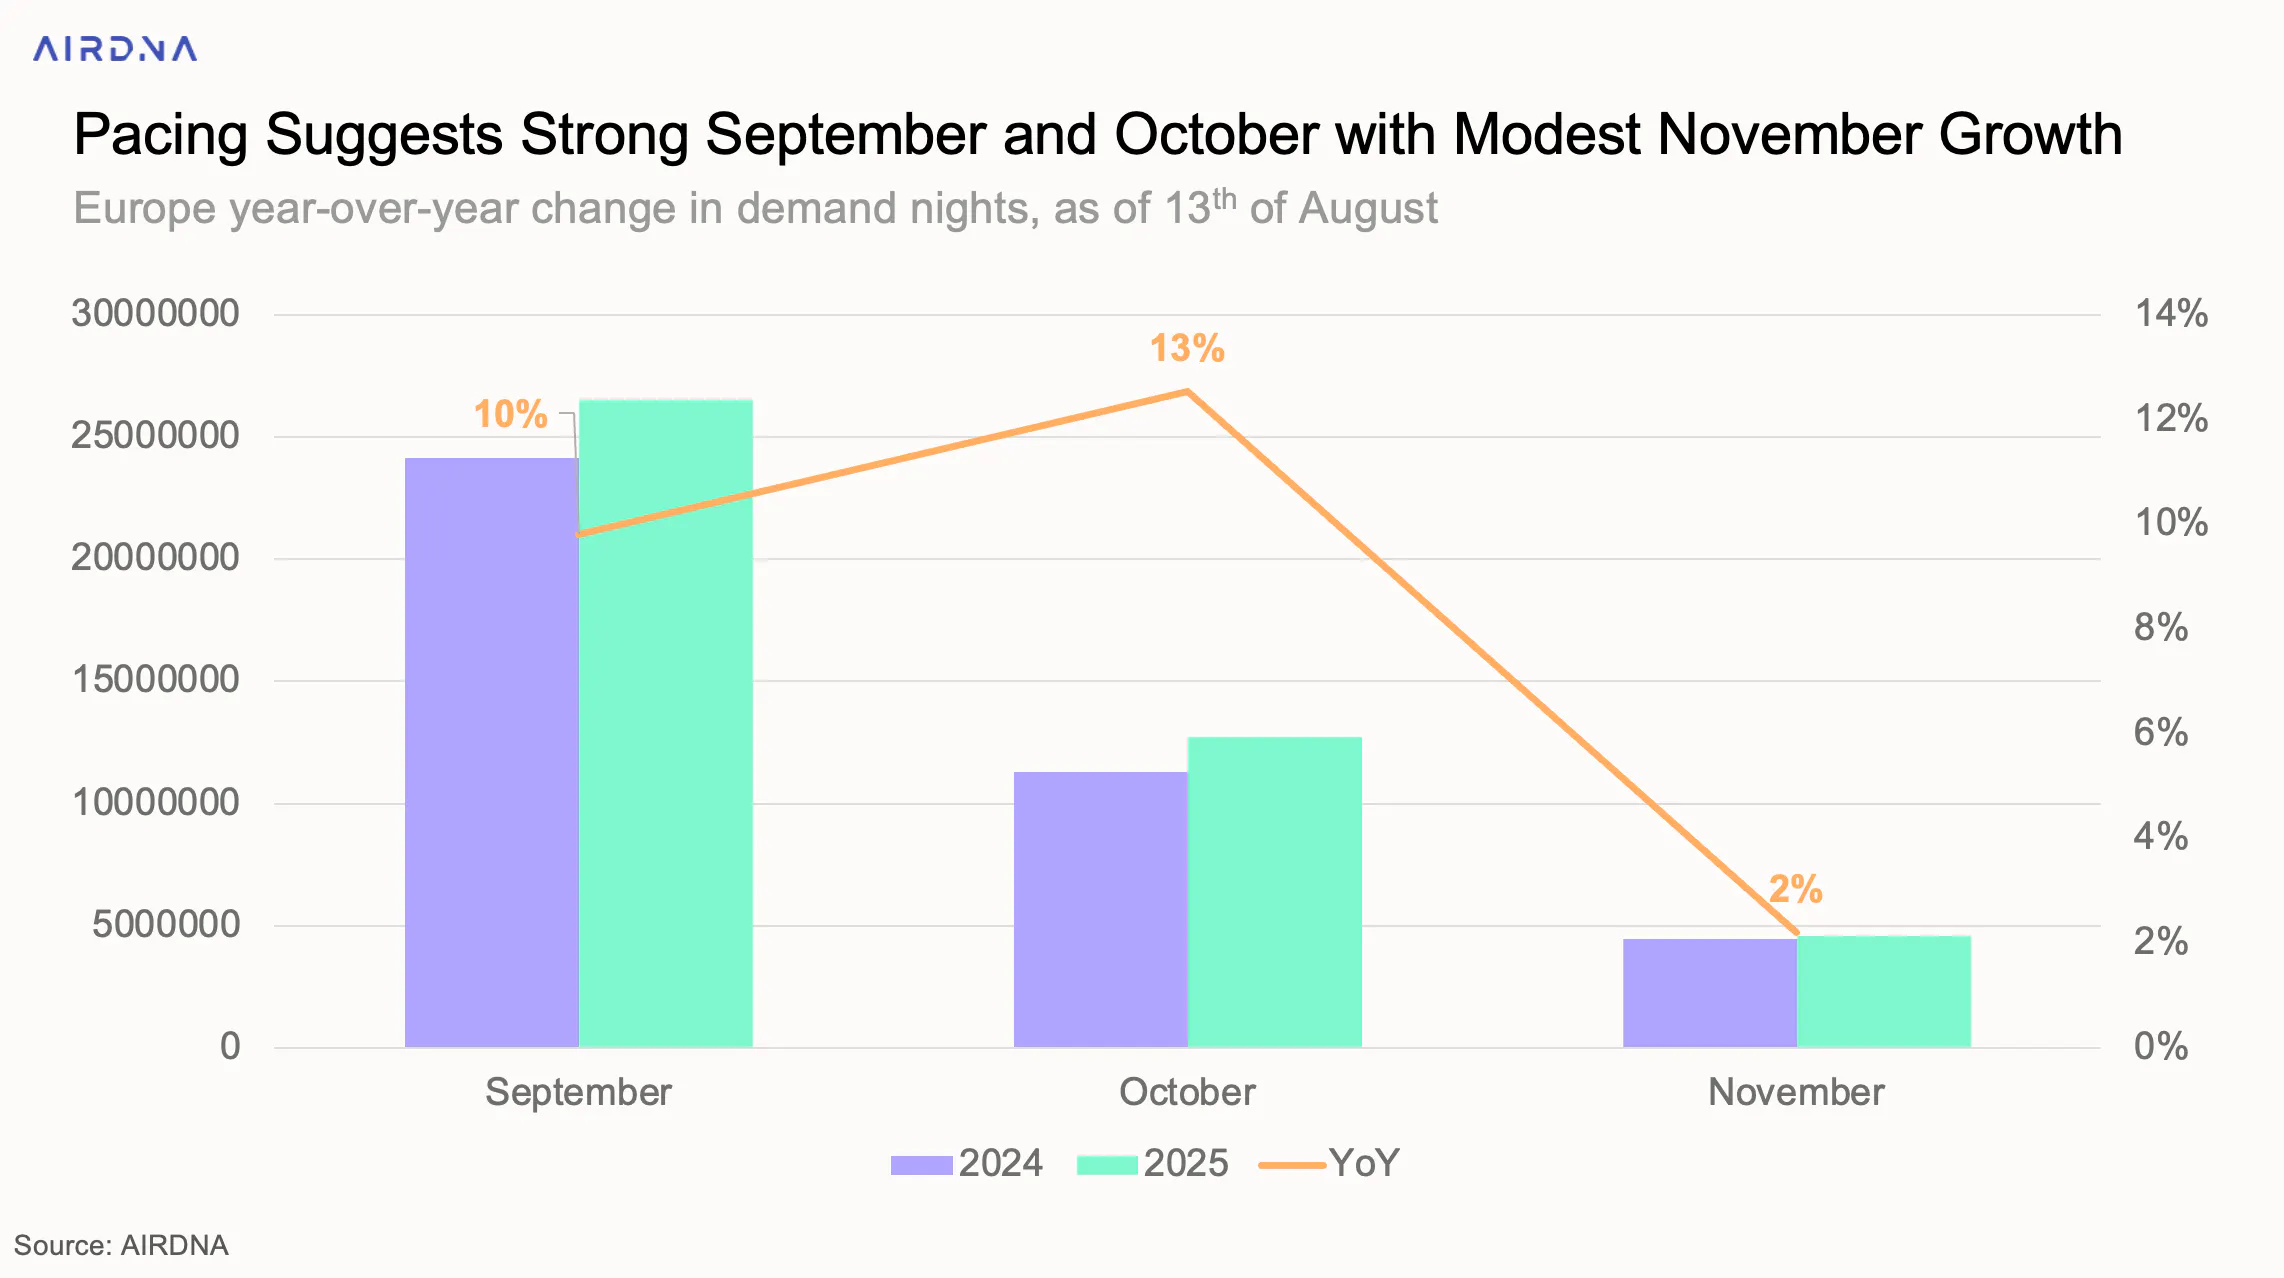
- Autumn pacing looks strong, with bookings up 10% for September and 13% for October.
July marked another record high for available listings in Europe’s short-term rental market, while demand continued its steady growth, even as listing expansion slowed in mature Southern European destinations.
Demand Nights rose 7.7% year-over-year to 61.3 million, while listing growth eased to 2.8%, reaching 4.15 million total listings. This supply-demand dynamic pushed occupancy up by 3%, with France posting the strongest year-over-year gain. Meanwhile, hosts saw average daily rates (ADR) recover slightly, rising 0.6% to €171.87, which lifted revenue per available rental night (RevPAR) to €120.54.
With inflation steady and interest rates low, market conditions remain favorable heading into the second half of the year. Even as listing growth decelerates, demand is expected to stay strong through Q3 and Q4.
At a Glance: July 2025 STR Performance in Europe
- Available listings reached an all-time high of 4.15 million, an increase of 2.8% YOY
- Demand Nights reached 61.3 million, up 7.7% YOY
- Average daily rates (ADR) rose 0.6% YOY to 171.87 €
- Average occupancy rate hit 70%, up 3% YOY
Revenue per Available Rental Night (RevPAR) grew 3.6% YOY to 120.54 €
The State of the European Economy
The European Central Bank held interest rates steady in July, keeping the deposit facility rate at 2%. Inflation also remained stable at 2% for the third consecutive month, bringing the 12-month average to 2.1%, which is well aligned with the ECB’s medium-term target.
Uncertainty over U.S.-EU trade relations eased somewhat following the latest 15% tariff announcement, contributing to improved economic sentiment.
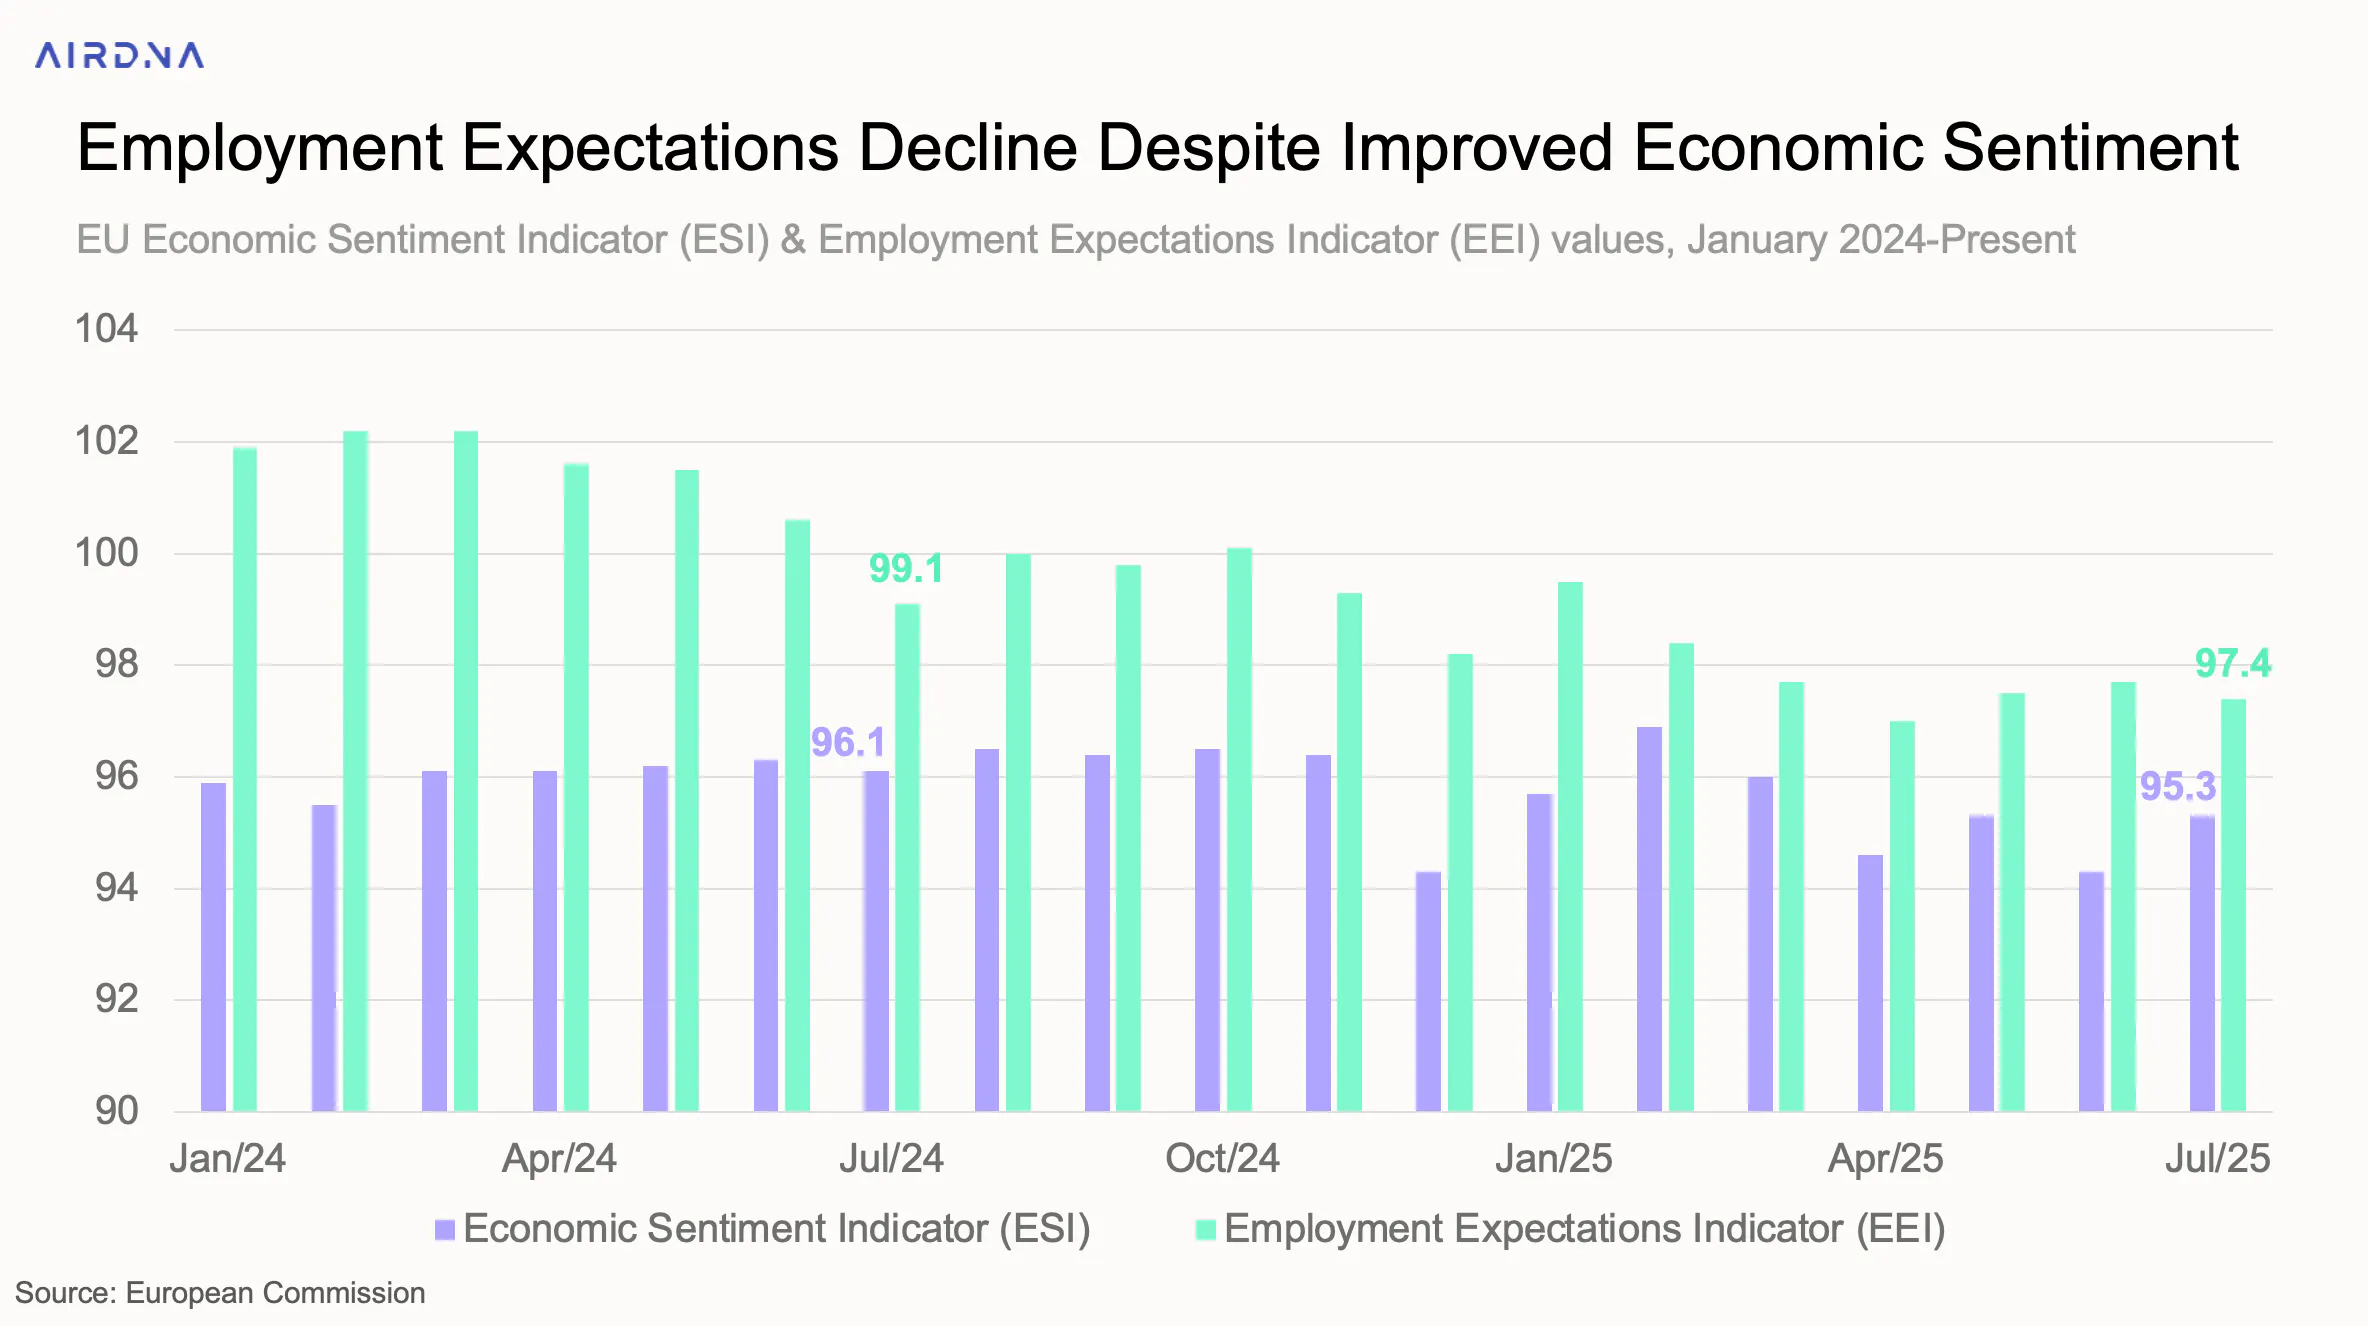
According to the European Commission, the Economic Sentiment Indicator (which reflects confidence across industry, services, retail, construction, and consumers) rose from 94.3 in June to 95.3 in July. However, it’s still unclear whether this upward trend will hold.
Meanwhile, the Employment Expectations Indicator slipped by 0.2 points to 97.4, its lowest level since May and second-lowest since February 2021. That slight decline suggests that, even though overall economic sentiment is improving, businesses may be pulling back slightly on hiring plans, possibly in response to global uncertainty or soft demand in specific sectors.
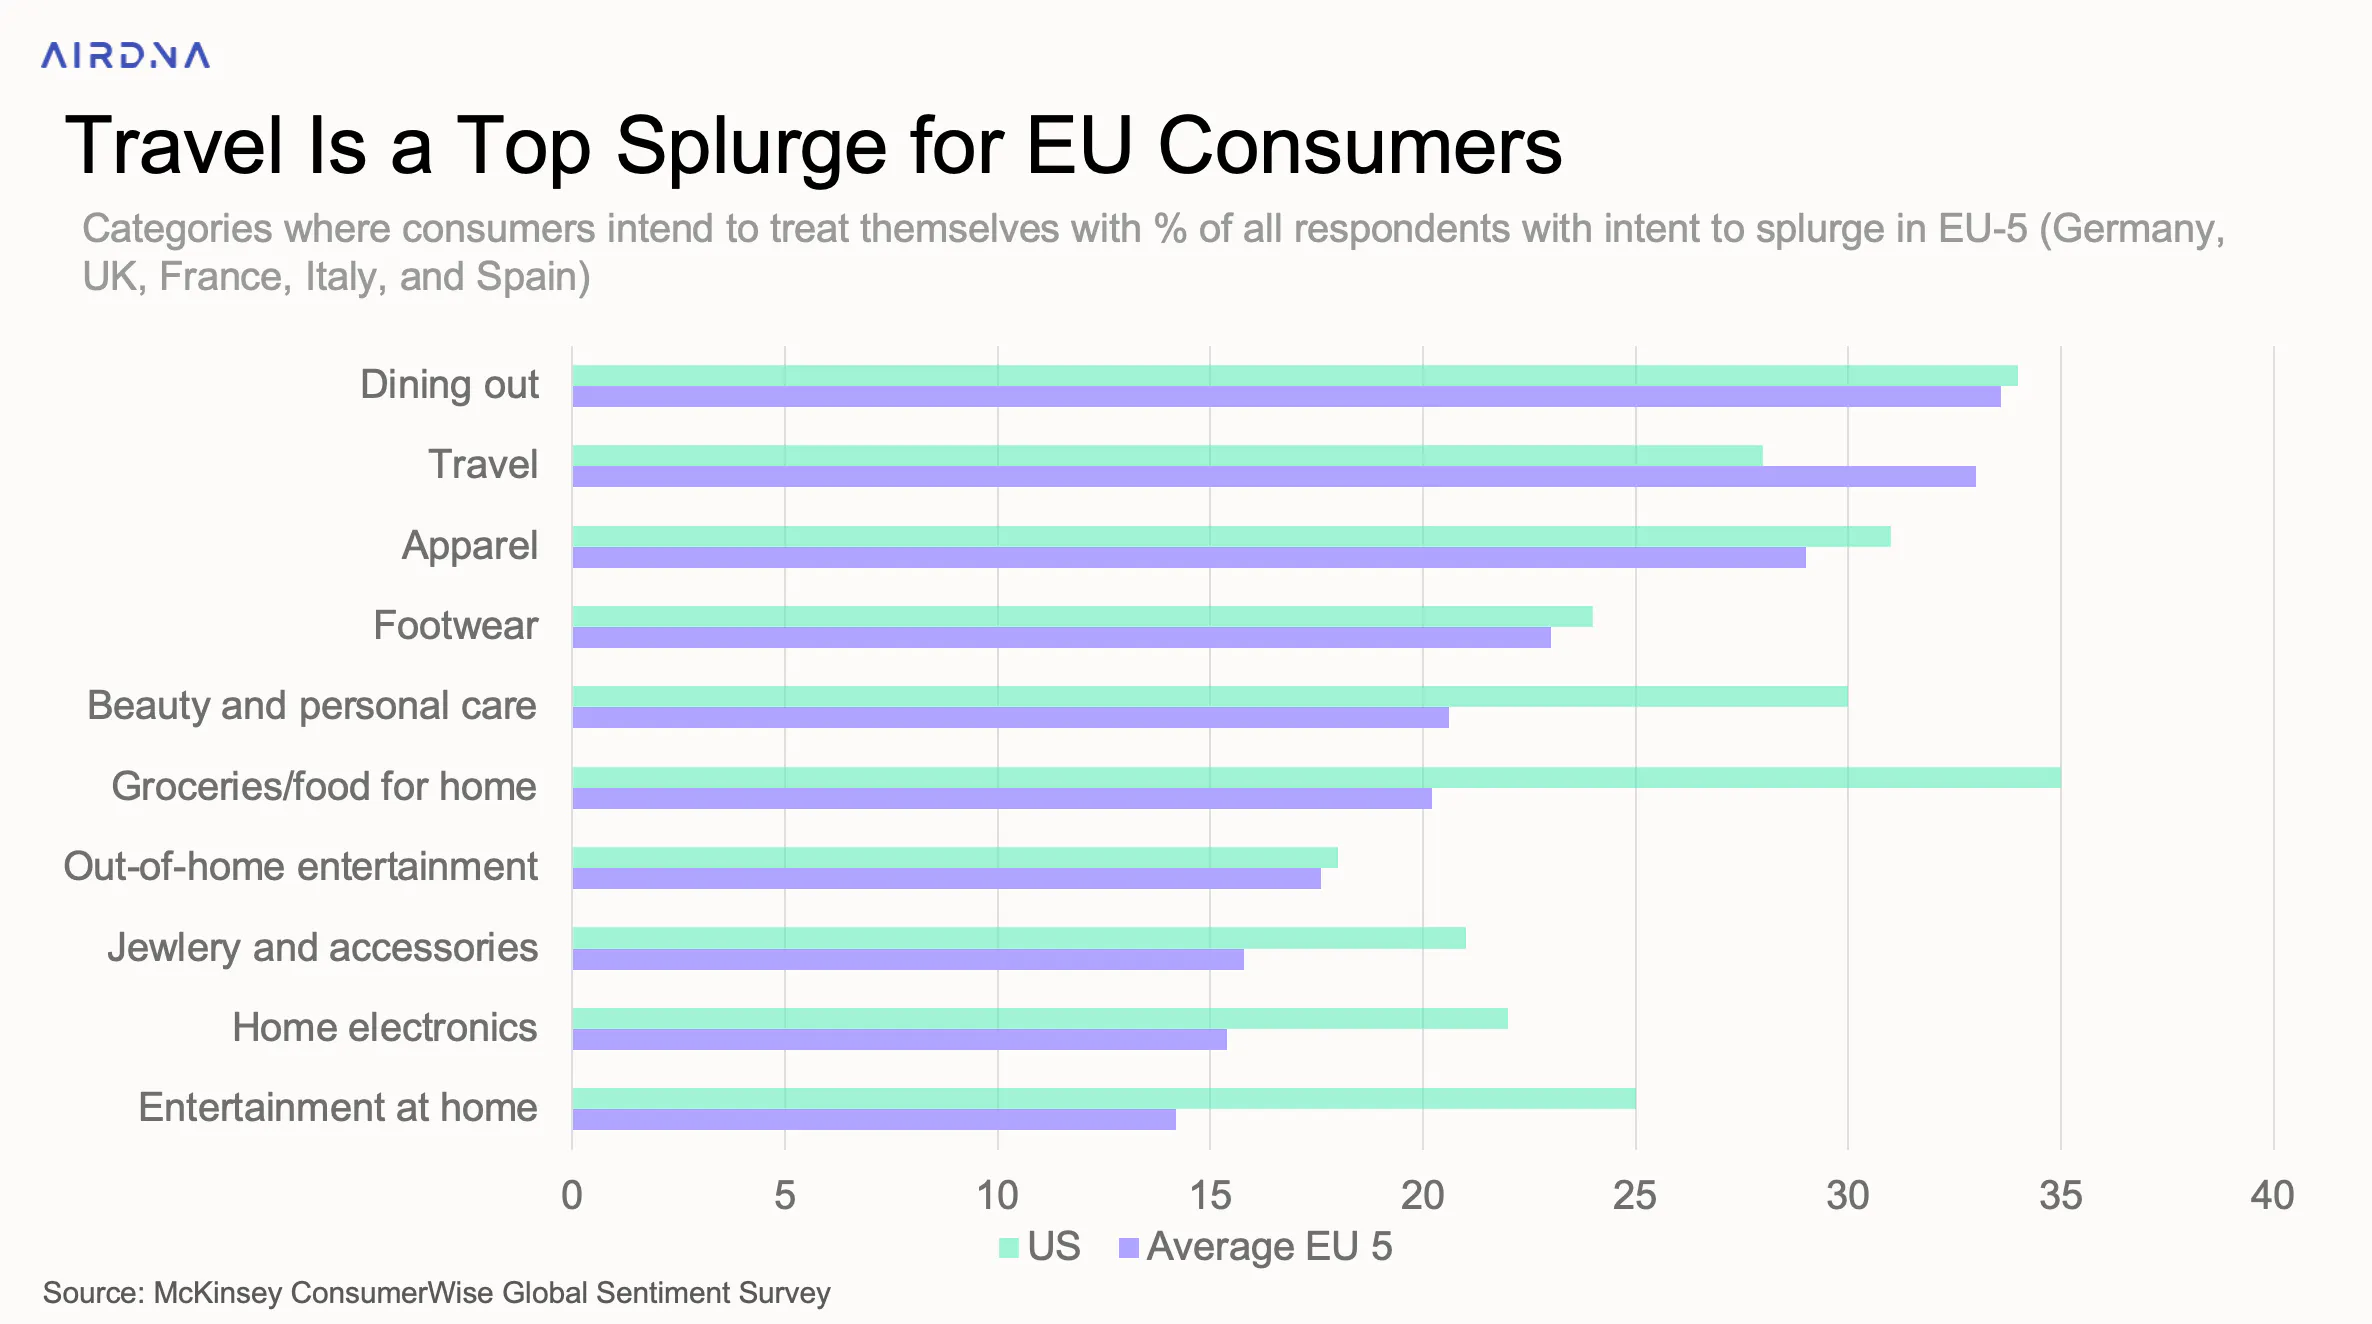
Despite these mixed economic signals, travel remains a top spending priority for European consumers. In the EU-5 (Germany, UK, France, Italy, and Spain), 33% of respondents ranked travel as a top “splurge” category — second only to dining out. It was the top choice for Gen X, Millennials, and Baby Boomers, while Gen Z placed it further down their list.
These preferences point to sustained demand for short-term rentals (STRs) through the second half of the year, particularly as households continue to prioritise experiences over material purchases. Unlike in the U.S., where travel intent is cooling, European demand remains resilient, even in the face of broader uncertainty.
Record Listings in July, Despite Slower Growth in Major Markets
Short-term rental listings in Europe reached a record 4.15 million in July, rising 2.8% year-over-year and 2.5% month-over-month. This marks the second consecutive month of record listings, and the second straight year where July and August have broken back-to-back records.
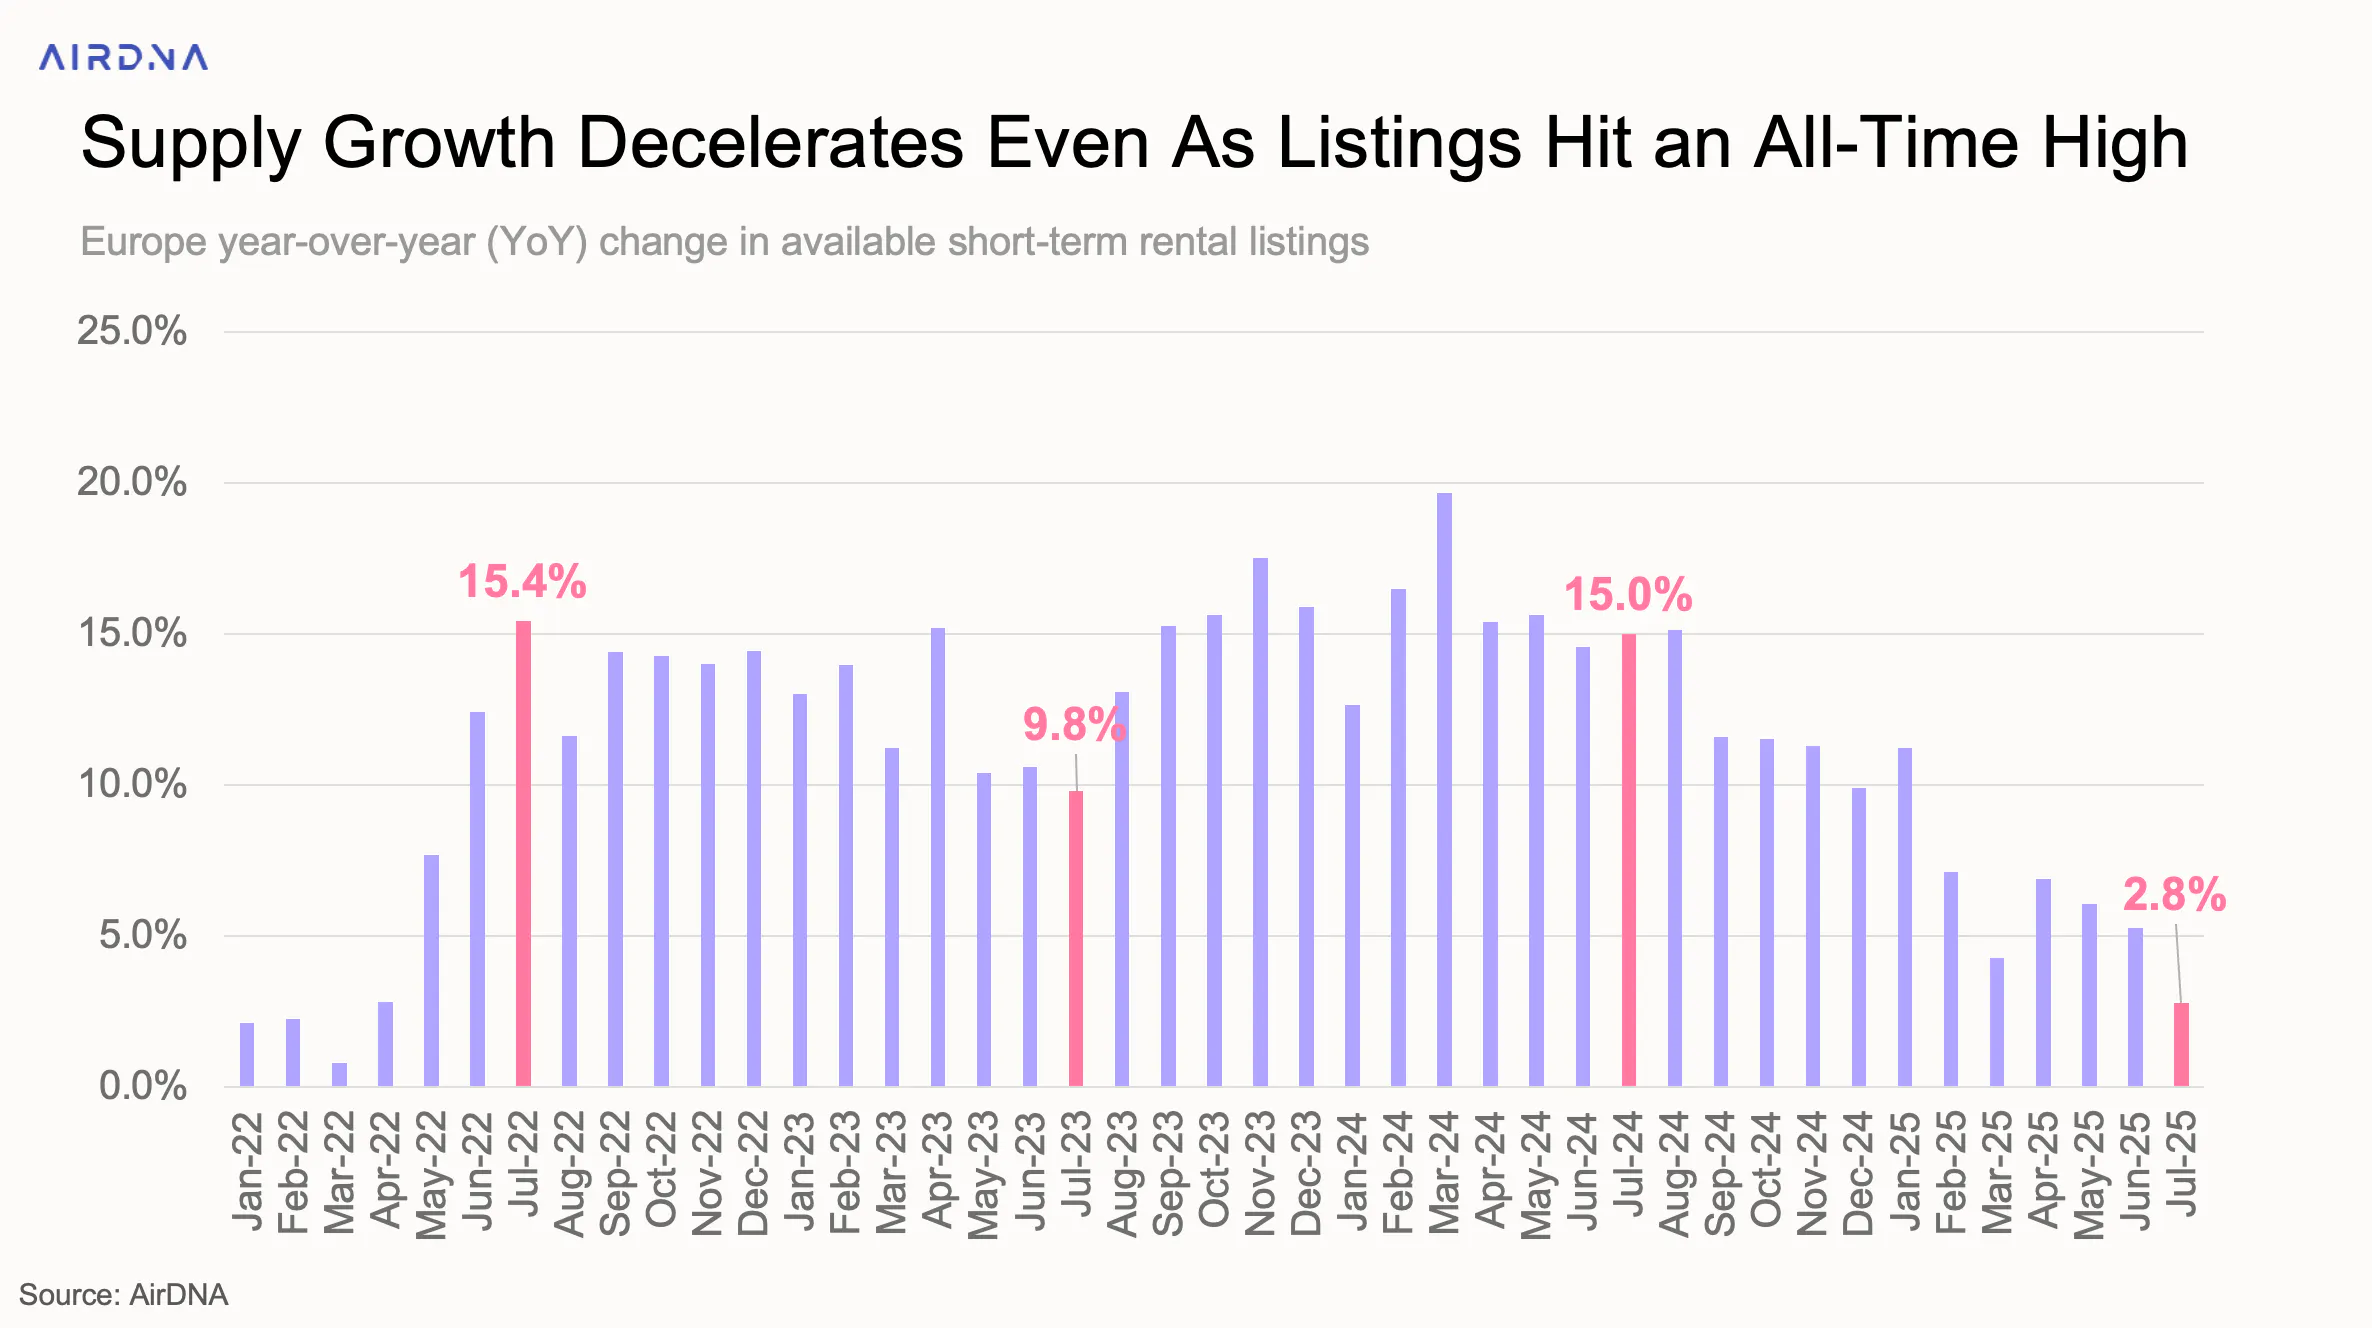
However, as highlighted in last month’s European Review, the pace of growth is clearly slowing. July 2025 saw the lowest year-over-year increase in listings since March 2022 (+2.2%). Still, the top 20 countries recorded an average growth rate of 6.5%, showing continued expansion in key markets.
Some of the largest markets saw slight annual declines, such as Italy (-1.5%), Spain (-1.2%), and France (-1.1%), though France’s dip is largely due to the unusually high supply during last year’s Summer Olympics. Excluding Paris, French listings actually rose 1.1% year-over-year. In contrast, Germany (+9%), the Netherlands (+8.7%), and Switzerland (+8.2%) posted strong gains and maintained upward momentum.
Despite a slowdown in momentum across Europe, several markets, particularly in central and northern regions, are still experiencing notable growth. With inflation remaining steady at the ECB’s 2% medium-term target for the past year and interest rates holding at 2% (the lowest since December 2022), not to mention clarity on tariffs imposed by the United States, supply growth is expected to persist in Q3 and Q4.
Travelers Plan Ahead as Luxury Demand Leads the Way
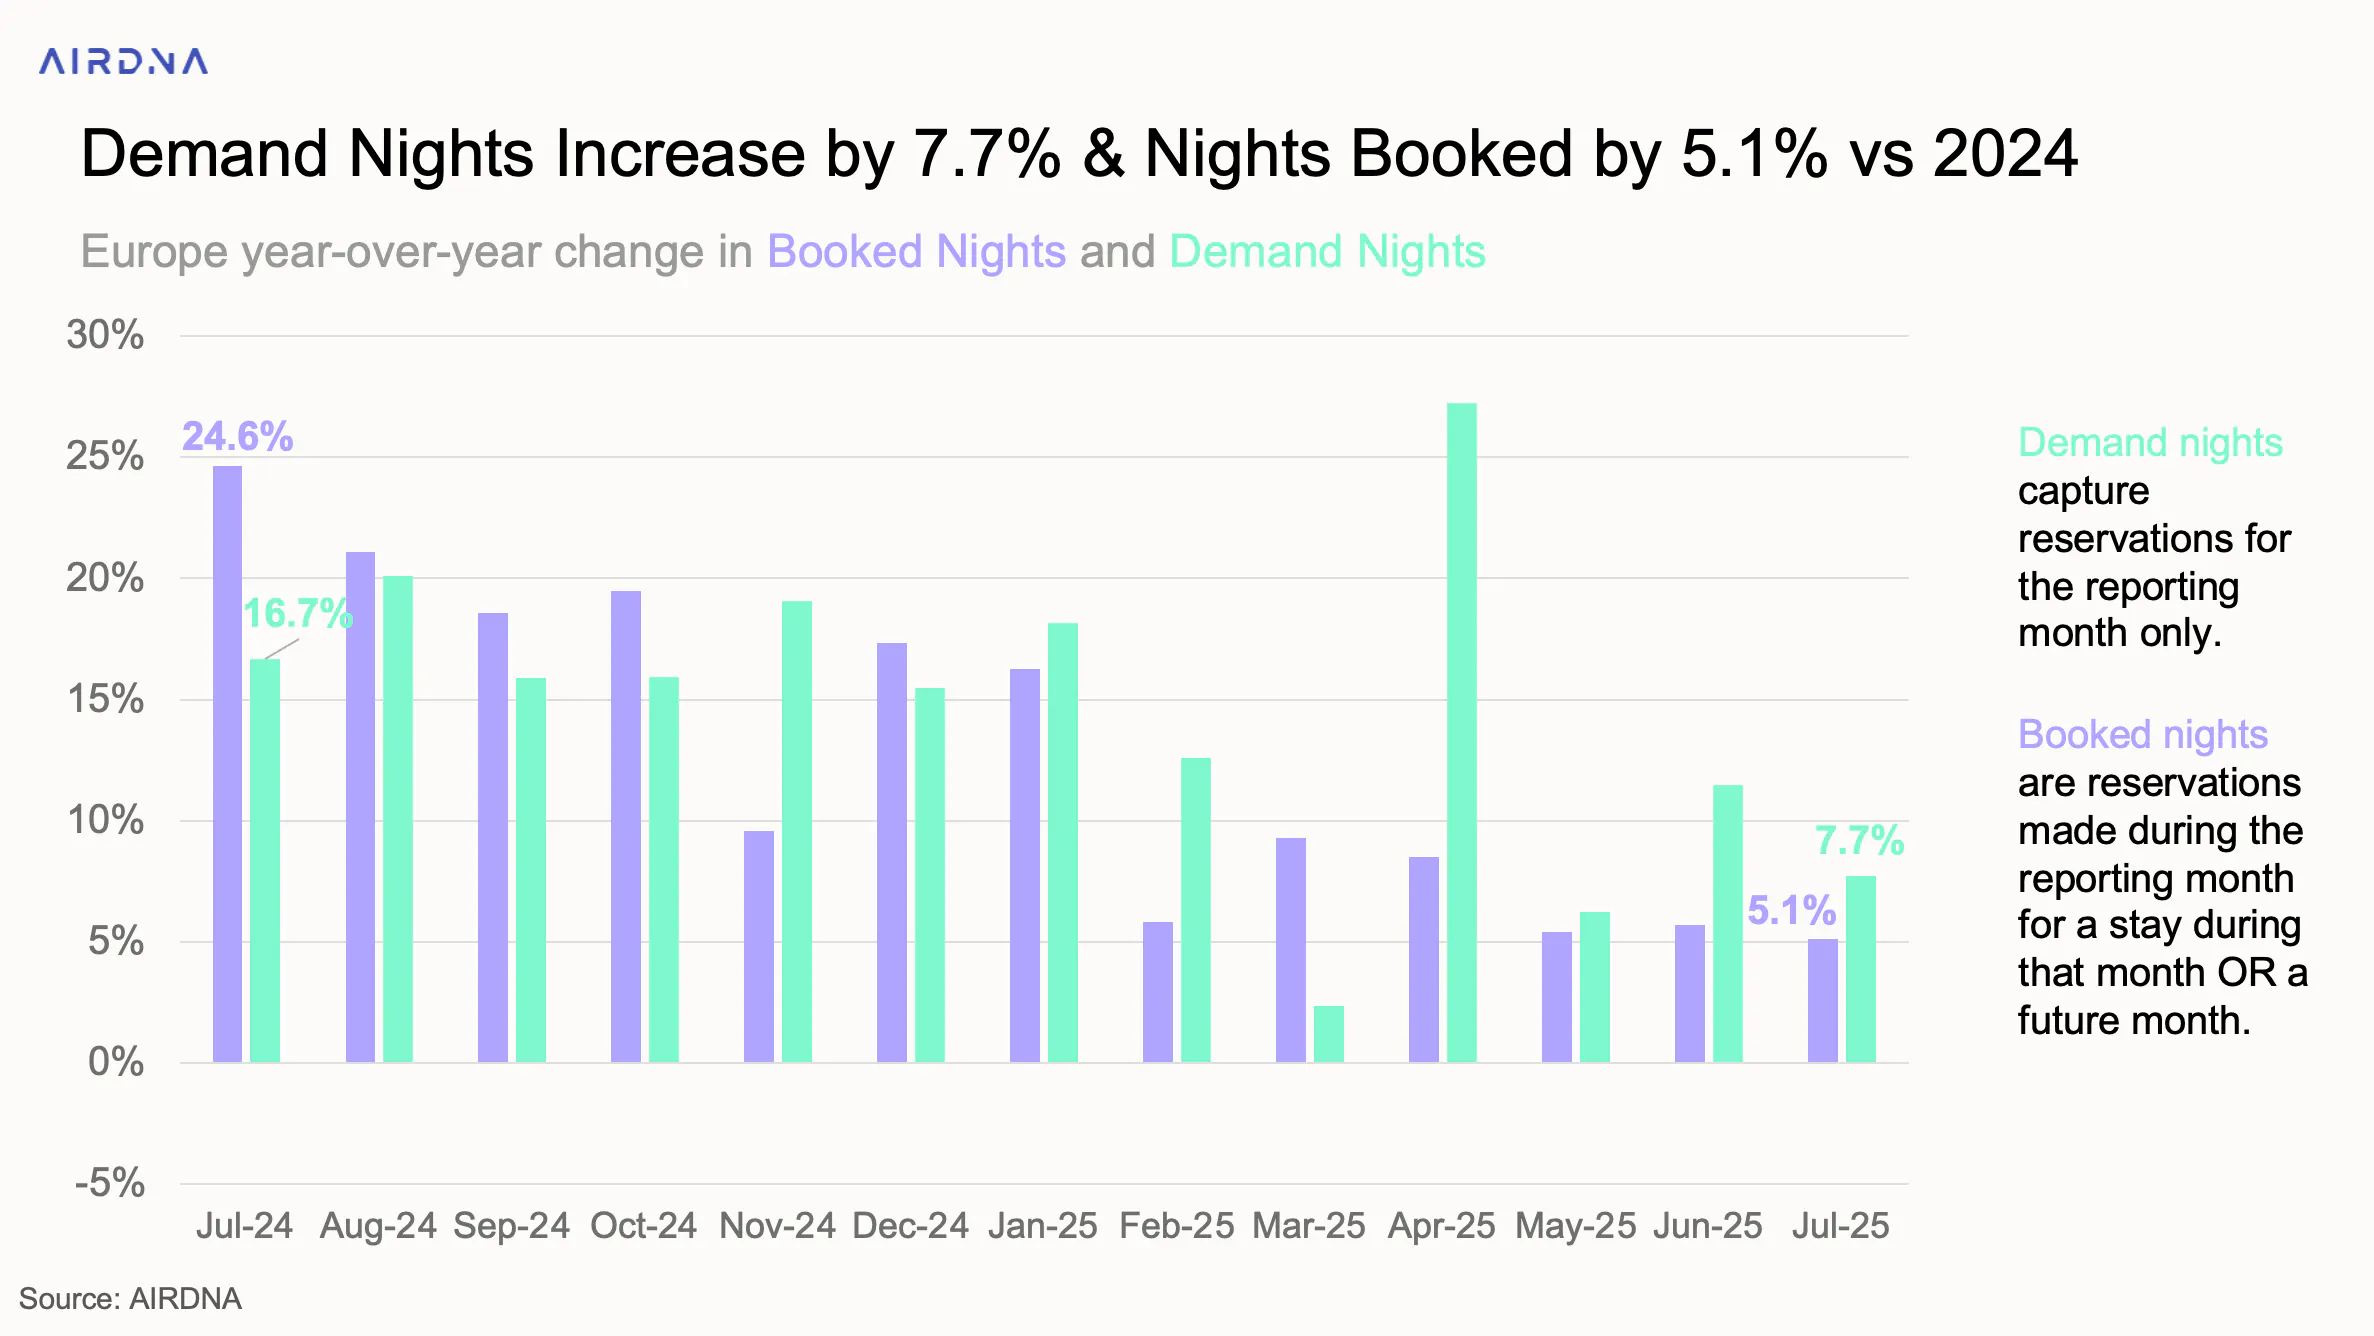
Demand Nights (bookings for stays during July) rose 7.7% year-over-year, signaling continued strength in guest activity across Europe. Nights Booked, which includes future reservations made during July, increased 5.1%, reflecting renewed confidence among travelers to plan ahead.
After a few slower months, this rebound in the booking pipeline suggests that while shorter lead times persist, travelers are increasingly comfortable committing to future stays. The growth in both metrics points to sustained demand, even amid regulatory shifts and macroeconomic headwinds.
Additionally, shifting seasonality patterns may be shaping booking behavior, with July and August no longer the sole focus of peak travel. Adding credence to this theory, we see steady growth emerging in shoulder months such as September and October.
Luxury listings saw a 14% YoY increase, with upscale properties up 9%. Midscale rentals followed at +6%, while growth in budget (+2%) and economy (+4%) segments remained modest. This tilt toward premium offerings suggests that higher-income travelers are still willing to spend, even as the broader market cools slightly.
Fifteen of the top 20 markets posted double-digit increases in luxury listings. While mature markets, including Italy, Spain, the UK, and France, showed smaller gains (and still represent 63% of supply), emerging markets led the charge. Norway, Denmark, and Switzerland, which together made up just 5% of July’s listings, recorded the strongest YoY growth in the luxury category, underscoring the rise of less saturated destinations.
Occupancy Holds Strong Across Key Markets
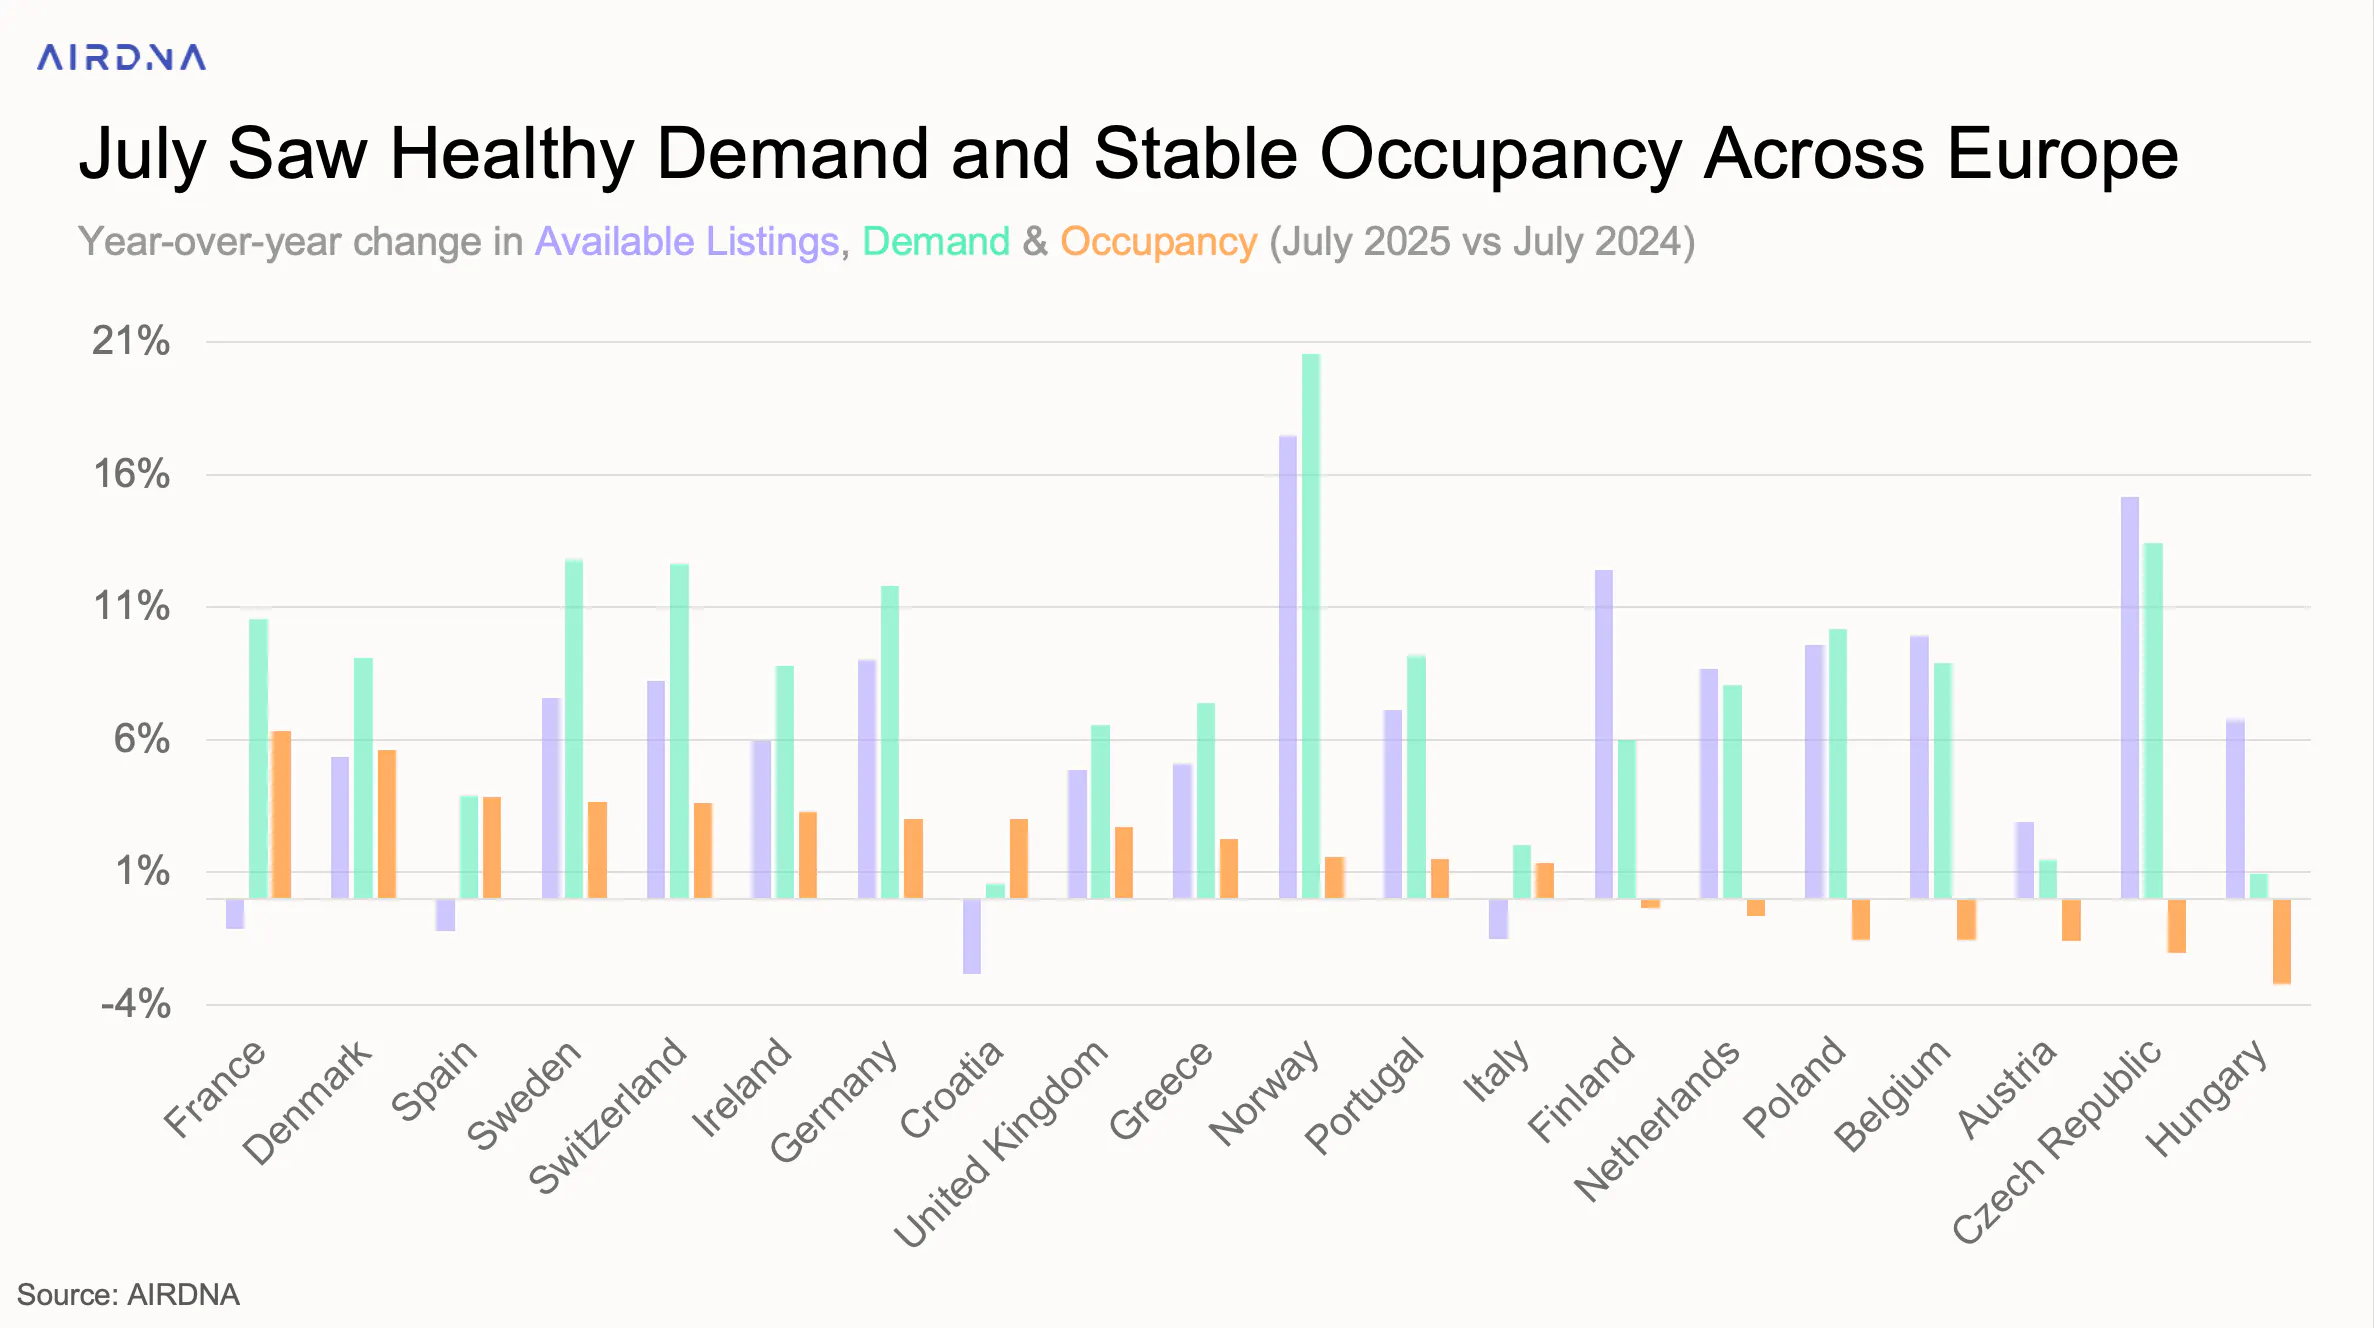
Occupancy either held steady or climbed across much of Europe in July 2025, with several countries posting strong year-over-year gains. France and Denmark led with +6% growth, followed by Spain, Sweden, and Switzerland at +4%. Ireland, Germany, Croatia, and the UK each rose +3%, while Greece, Norway, and Portugal saw +2%, and Italy ticked up 1%.
Even in markets where listings contracted, such as France (-1%), Spain (-1%), Italy (-2%), and Croatia (-3%), occupancy stayed stable or increased, highlighting the resilience of guest demand.
By contrast, markets with faster supply growth, such as the Netherlands, Poland, Belgium, Austria, the Czech Republic, and Hungary, saw occupancy dip as new inventory outpaced demand. Still, the overall supply-demand balance in July supported strong occupancy across much of the region.
France’s performance stood out. With demand up 11% and supply slightly down, occupancy rose 6% year-over-year, even without a major event like the 2024 Paris Olympics. In a tightly regulated, mature market, that kind of growth highlights both operational efficiency and the continued appeal of France’s tourism economy.
Consistent with the trend seen so far this year, listing growth remained muted in June for Italy, Spain, the UK, and France, staying below 5% in all four markets. However, this slower pace of listing growth meant less inventory to meet rising demand, resulting in occupancy gains across the board.
The top occupancy performers were Croatia, Poland, and the Czech Republic, each topping 6% YoY growth. Croatia saw a 0.8% dip in listings but an 11.7% rise in demand, lifting occupancy by 10.6%. Poland and the Czech Republic recorded even stronger demand (both above 15% YoY), which translated into sharp occupancy gains.
Other markets with notable demand growth in June included Norway, Belgium, and the Netherlands. Norway remains a leader in demand growth with a 27% year-over-year increase in June, translating to a 3% occupancy boost. Belgium and the Netherlands saw demand rise by 20.7% and 18.5%, respectively, each recording a 4% occupancy increase for the month.
ADR and RevPAR Rebound After Q2 Dip
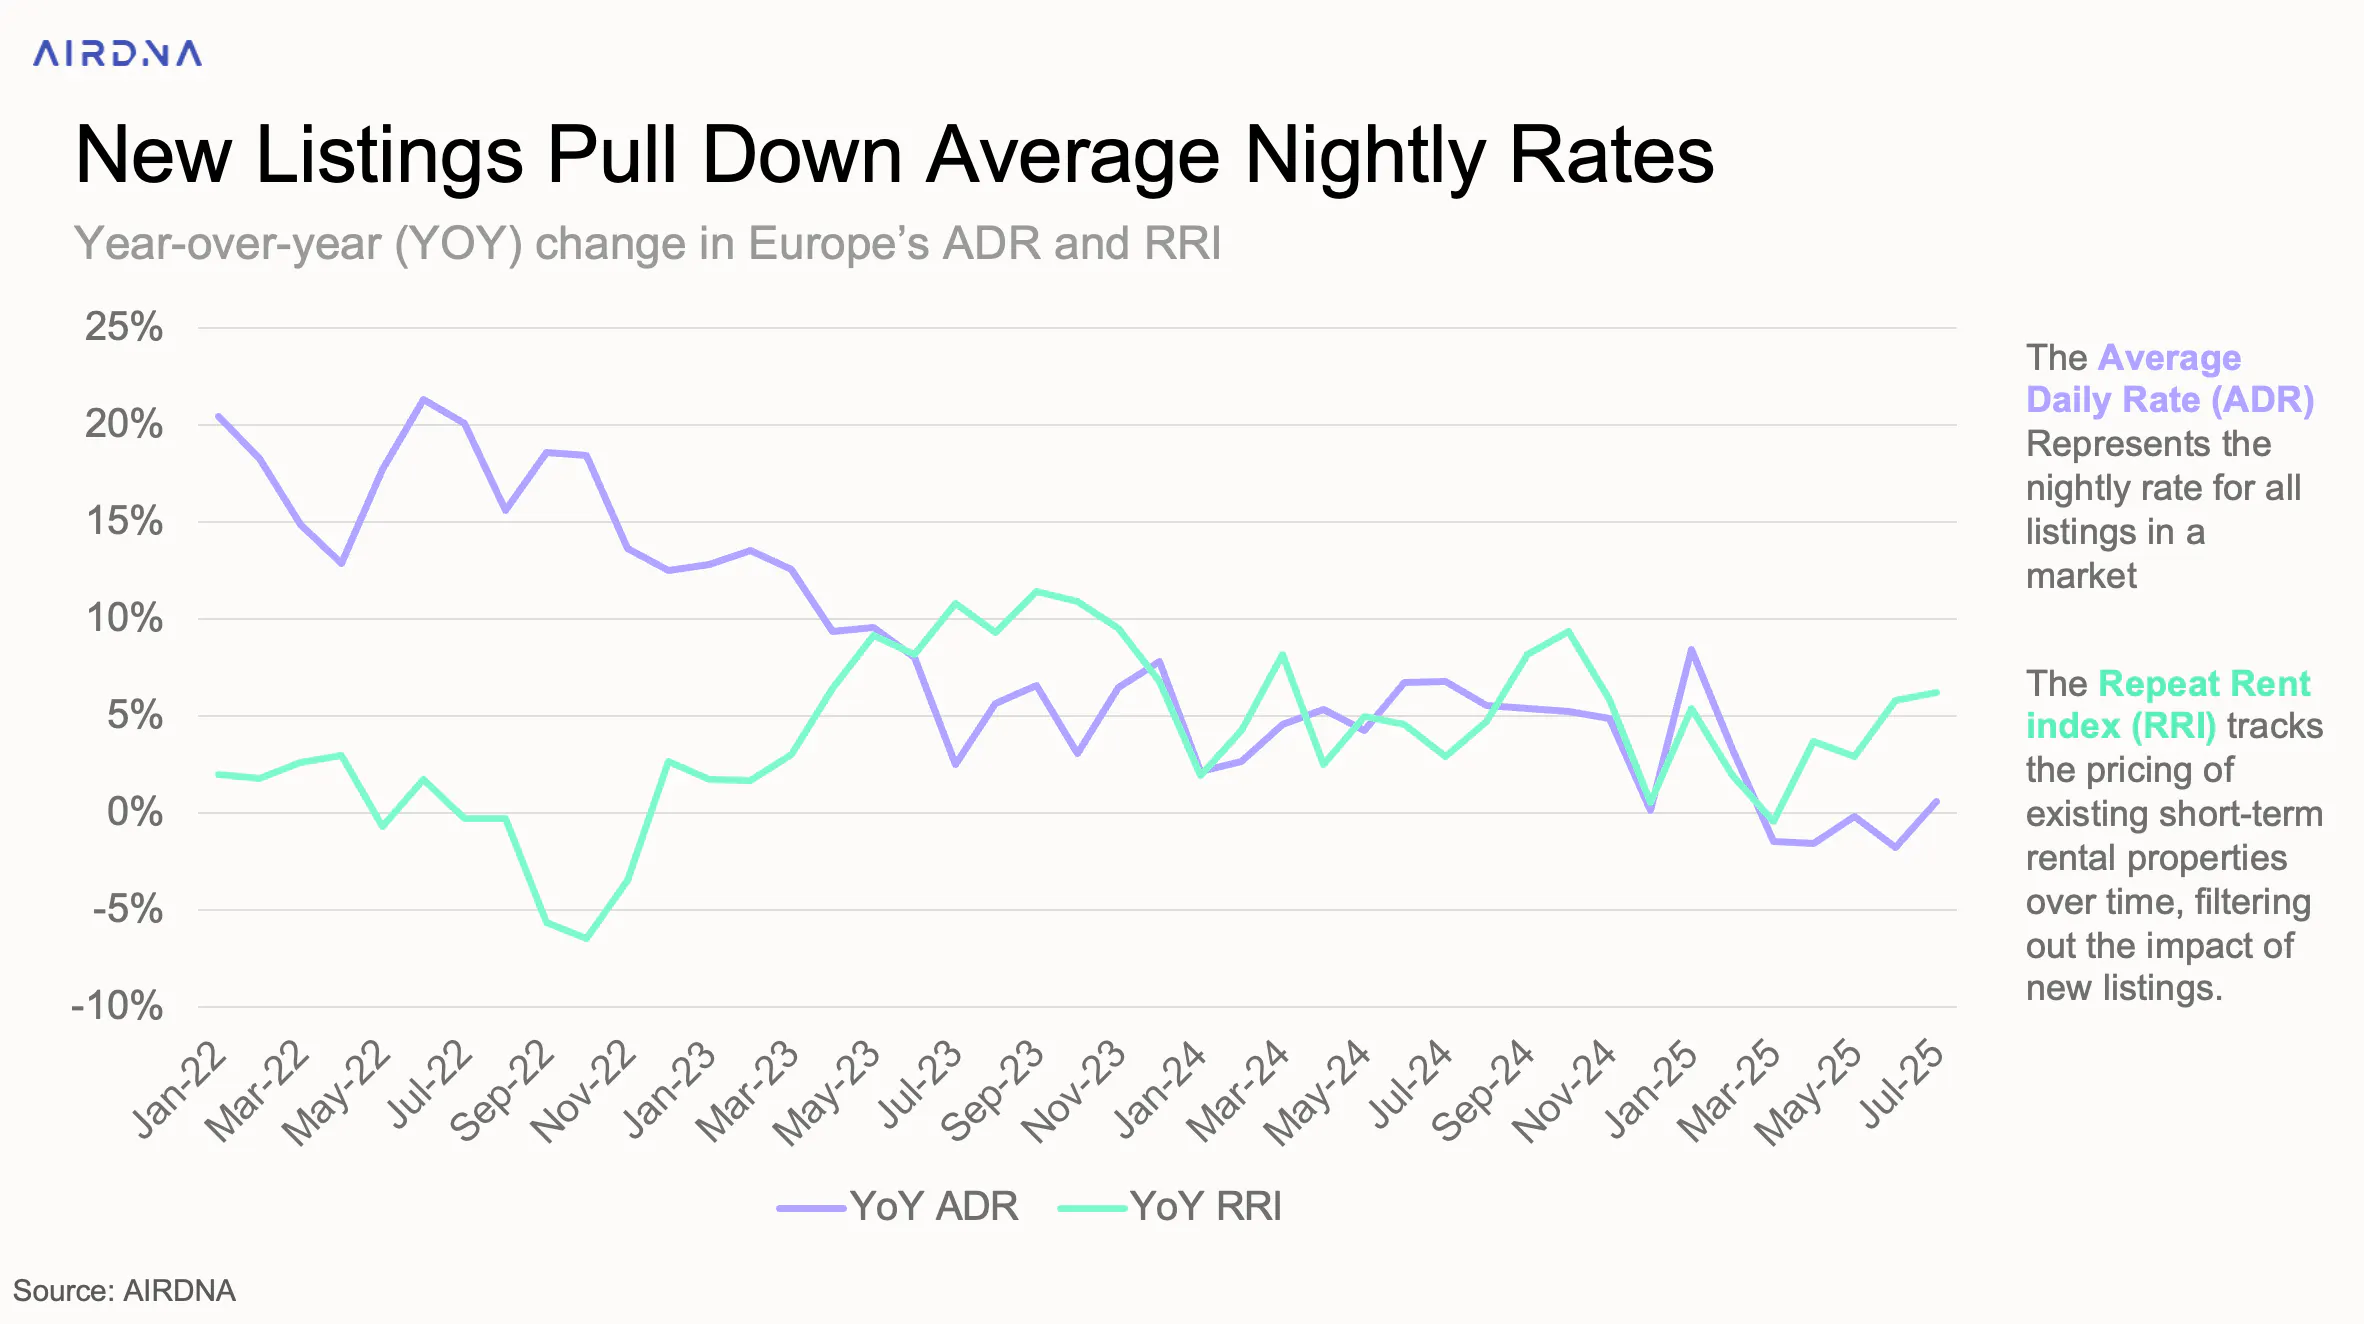
After a slow second quarter, average daily rates (ADR) returned to positive territory in July, rising 0.6% year-over-year. Though still below Europe’s inflation rate, this modest gain marks a shift in momentum following several months of flat or negative growth.
The AirDNA Repeat Rent Index (RRI) (which tracks rate changes for existing listings only) rose 6.2% YoY. The gap between ADR and RRI suggests that new listings are entering the market at lower price points, pulling down the overall average.
This divergence also marks a break from the pattern seen last year, when ADR and RRI growth were closely aligned. The shift may reflect a change in traveler preferences, with more guests booking lower-priced or value-focused properties. It’s the first time this kind of multi-month gap between ADR and RRI has appeared since late 2023.
Combined with a 3% increase in occupancy, the modest ADR growth helped push RevPAR up 3.6% across Europe — an improvement over June’s 1.7% and a notable rebound from May’s -2.6%. With inflation and interest rates holding steady and fewer external shocks on the horizon, there’s cautious optimism that revenue momentum may continue in the months ahead.
Shoulder Season Strengthens as Autumn Bookings Rise
As of August 13th, 2025, forward bookings for early autumn remained strong across Europe. September demand was up 10% year-over-year, while October led with a 13% increase. In contrast, November showed signs of slowing, with bookings rising just 2% YoY.
Although November has historically seen steady growth, this year’s softer performance may point to shifting travel behavior or broader economic caution later in the year. Meanwhile, the strong gains in September and October suggest an ongoing trend toward shoulder-season travel, as these months take up a larger share of annual demand.
ARTICLE SUMMARY
July 2025 saw record demand and occupancy in Europe’s STR market, led by growth in emerging destinations. While listing expansion slowed in major markets, rising rates and steady forward bookings helped sustain overall momentum..
Linda Rollins
Senior Research Analyst
Linda Rollins is a Senior Research Analyst at AirDNA and a self-managing short-term rental host, which means she understands the market as both an analyst and an operator. She writes research and blogs for AirDNA and for Adapt, its revenue management tool, making her work a go-to resource for investors trying to find and size up the right opportunities, and for operators looking to understand changing market dynamics and find concrete ways to improve occupancy, rates, and guest experience. Her data is regularly cited in major news outlets, and she has a knack for bringing both the numbers and the story behind them. In her free time, Linda enjoys spending time with her family, traveling, and looking for good eats.