European Review February 2025: Easter Travel Surges & the Beyoncé-Effect Hits Paris
Published: March 20, 2025
Jamie Zhang
Key Takeaways
- February short-term rental (STR) demand surged 12.1% year-over-year (YOY), driving occupancy growth across Europe.
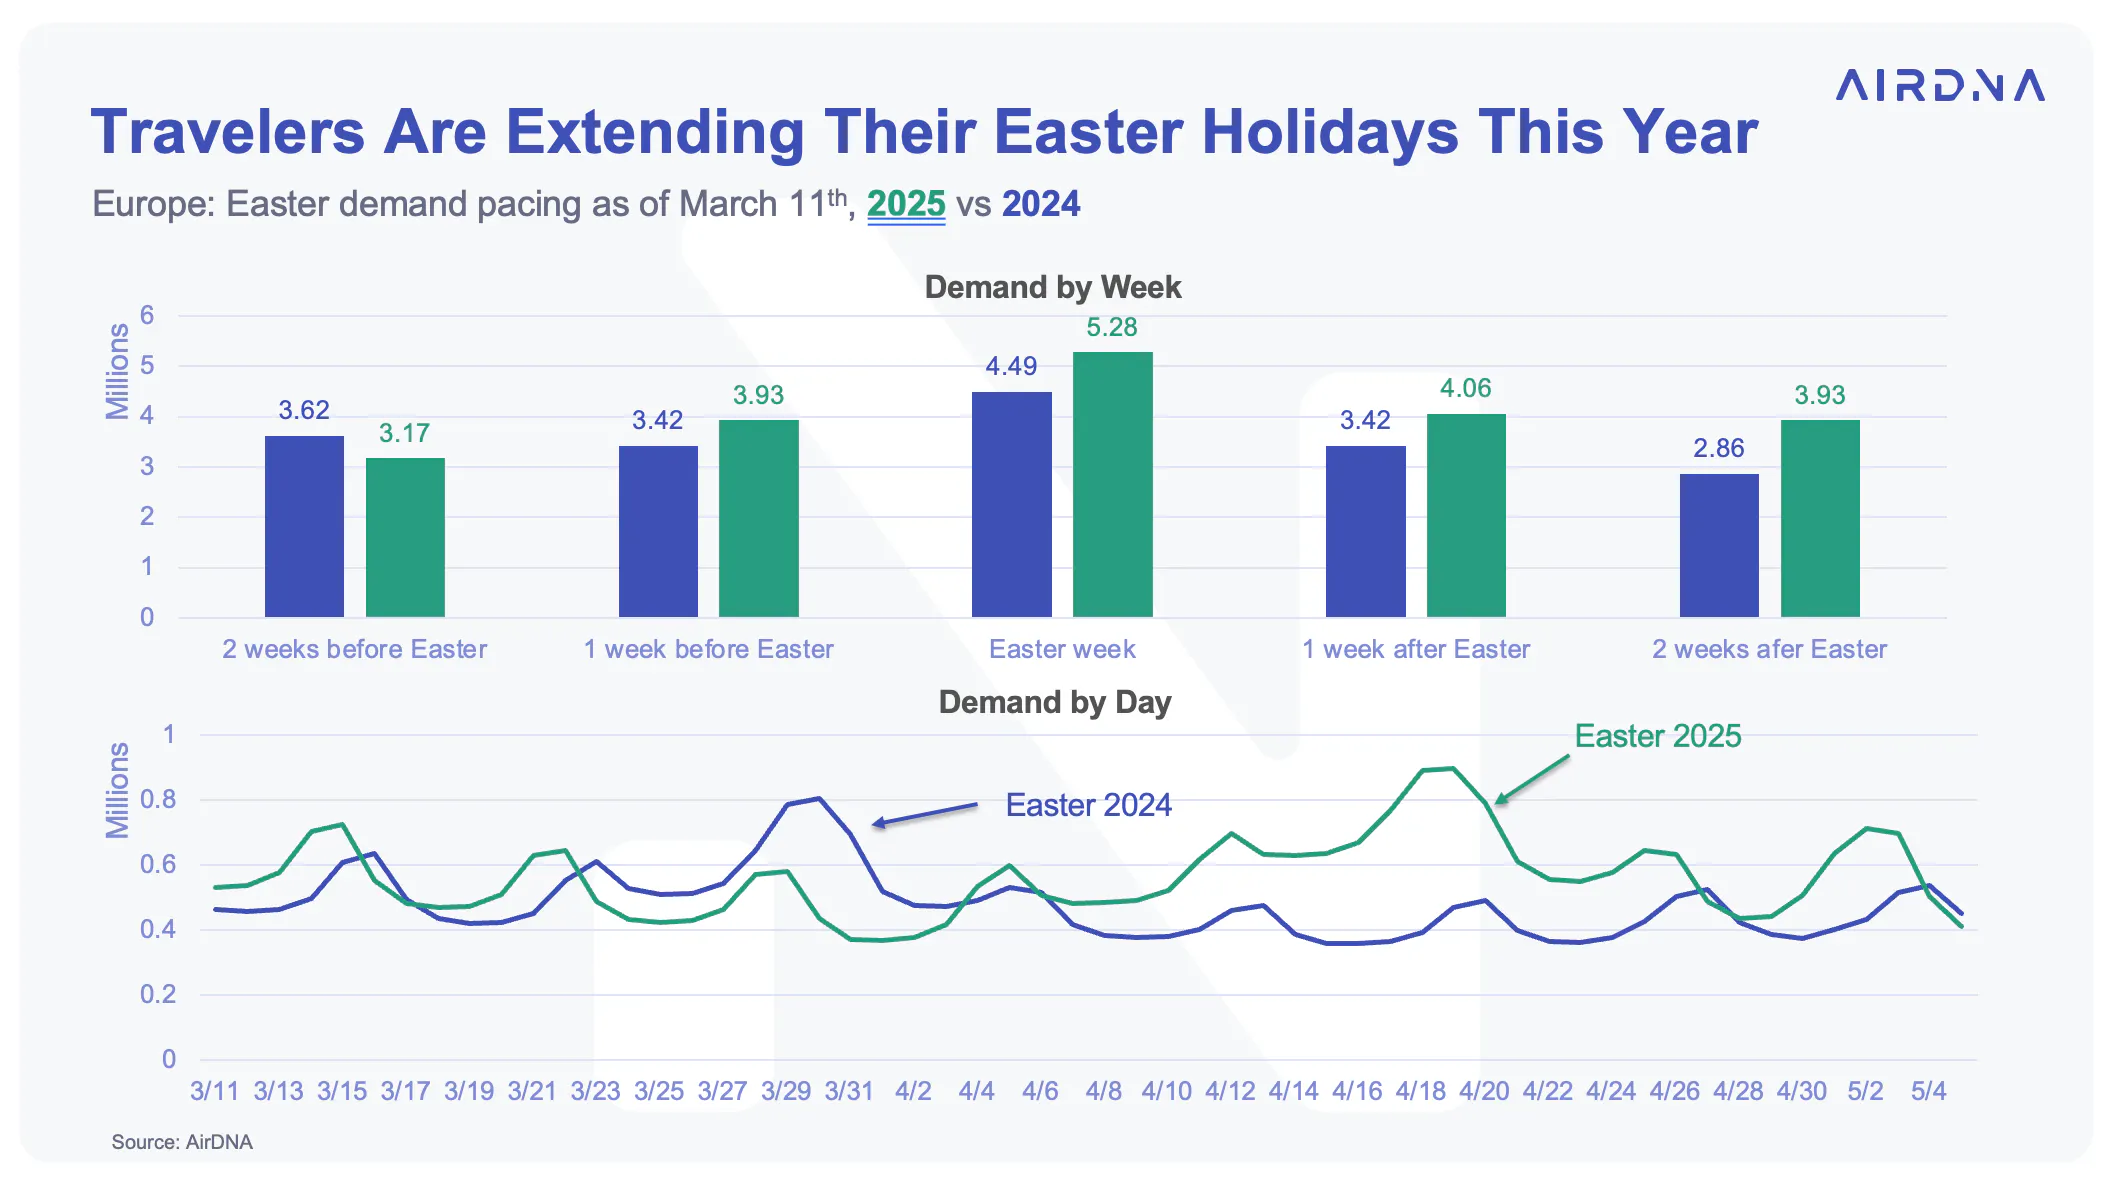
- Easter week bookings jumped 67% compared to two weeks prior, outpacing last year’s 24% increase, as travelers sought warmer destinations.
- Munich and Cologne, Germany, still offer last-minute Easter getaway deals, despite strong spring break demand across most of Europe.
February 2025 continued the strong momentum in Europe's short-term rental (STR) market.
While the first quarter is typically the slowest one for STR demand in Europe, total demand nights in Feb almost reached 24 million—an impressive 12% increase year-over-year (YoY). Listing growth also remained robust, rising 7.7% YoY to 3.1 million available listings.
With travelers favoring warmer weather and spring break getaways, Easter bookings spiked, and key markets like Italy and Greece saw exceptional performance. Here’s a deep dive into February’s trends and what’s ahead.
At a Glance: February 2025 STR Performance in Europe
- Available listings totaled 3.1 million, up 7.7% year-over-year (YoY)
- Demand nights reached 24 million, an increase of 12.1% YoY
- Average daily rates (ADR) averaged €158, up 0.9% YoY
- Average occupancy rate was 54%, up 3% YoY and 4.9% compared to 2019
- Revenue per Available Rental Night (RevPAR) increased 4.3% YoY to €89
- Booked nights increased 13.7% YoY
The State of the European Economy
The EU economy continued its steady growth in February 2025, with GDP projected to expand by 1.0%, according to OECD and Vanguard—a sign of economic resilience despite global uncertainties.
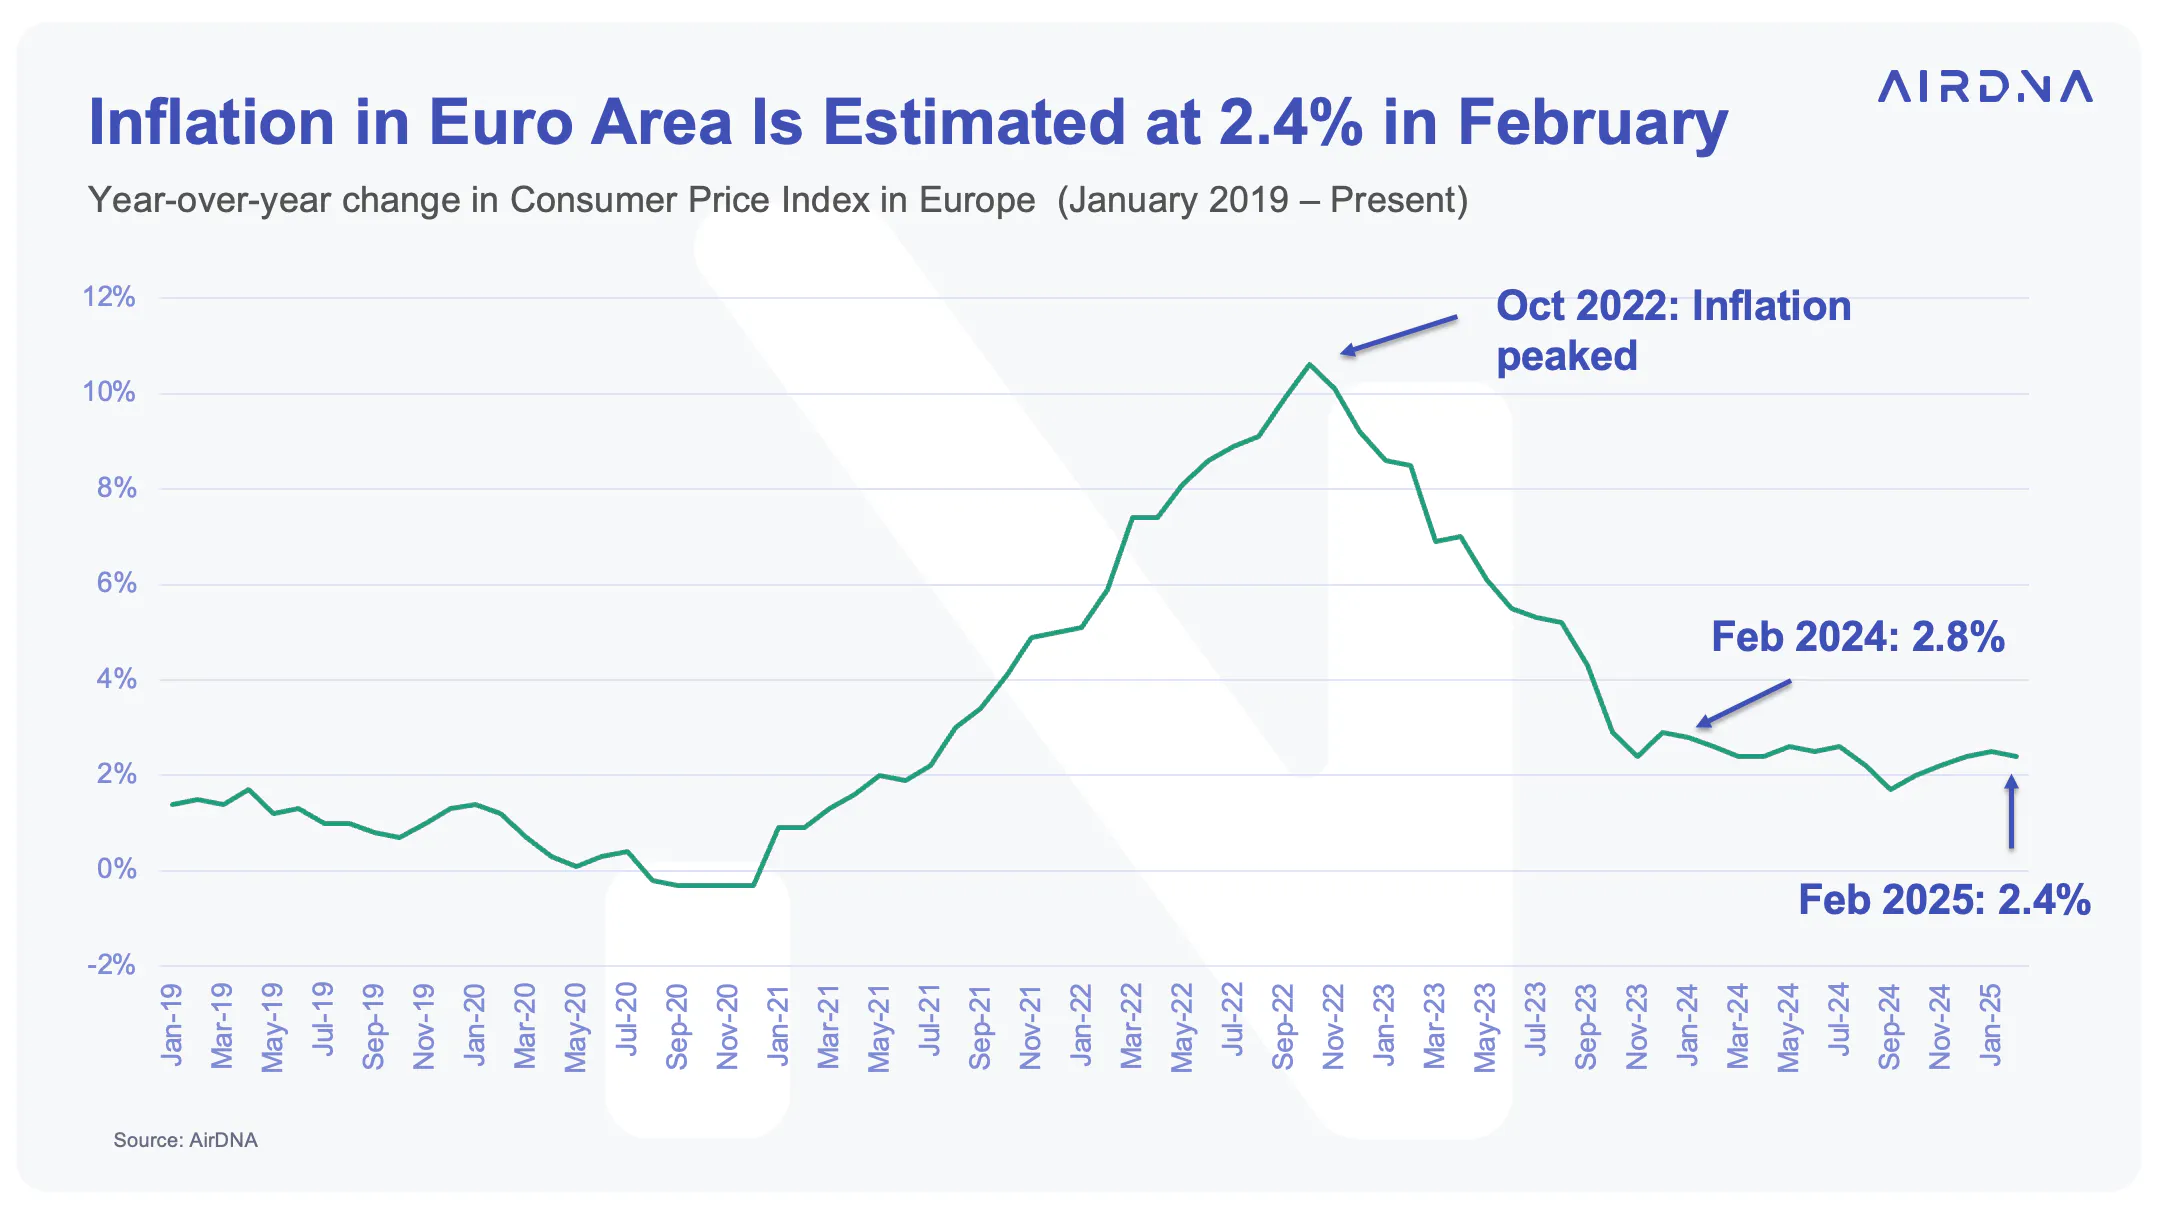
Inflation eased to 2.4% YoY, down from 2.5% in January and 2.8% a year ago, moving closer to the ECB’s 2% target. In response, the ECB lowered its main interest rate to 2.5% in early March, marking its sixth rate cut since June, further loosening monetary policy.
Meanwhile, unemployment stabilized at 6.2% in January, down from 6.5% a year earlier, reinforcing a strengthening labor market. With easing inflation and lower borrowing costs, consumer confidence may rise, boosting discretionary spending—including travel.
One potential headwind is the euro’s appreciation against the US dollar, which could dampen demand from non-EU travelers. However, solid GDP growth and stable employment levels are likely to support continued strong domestic travel demand within the euro area.
February Bookings Continued to Grow Meaningfully
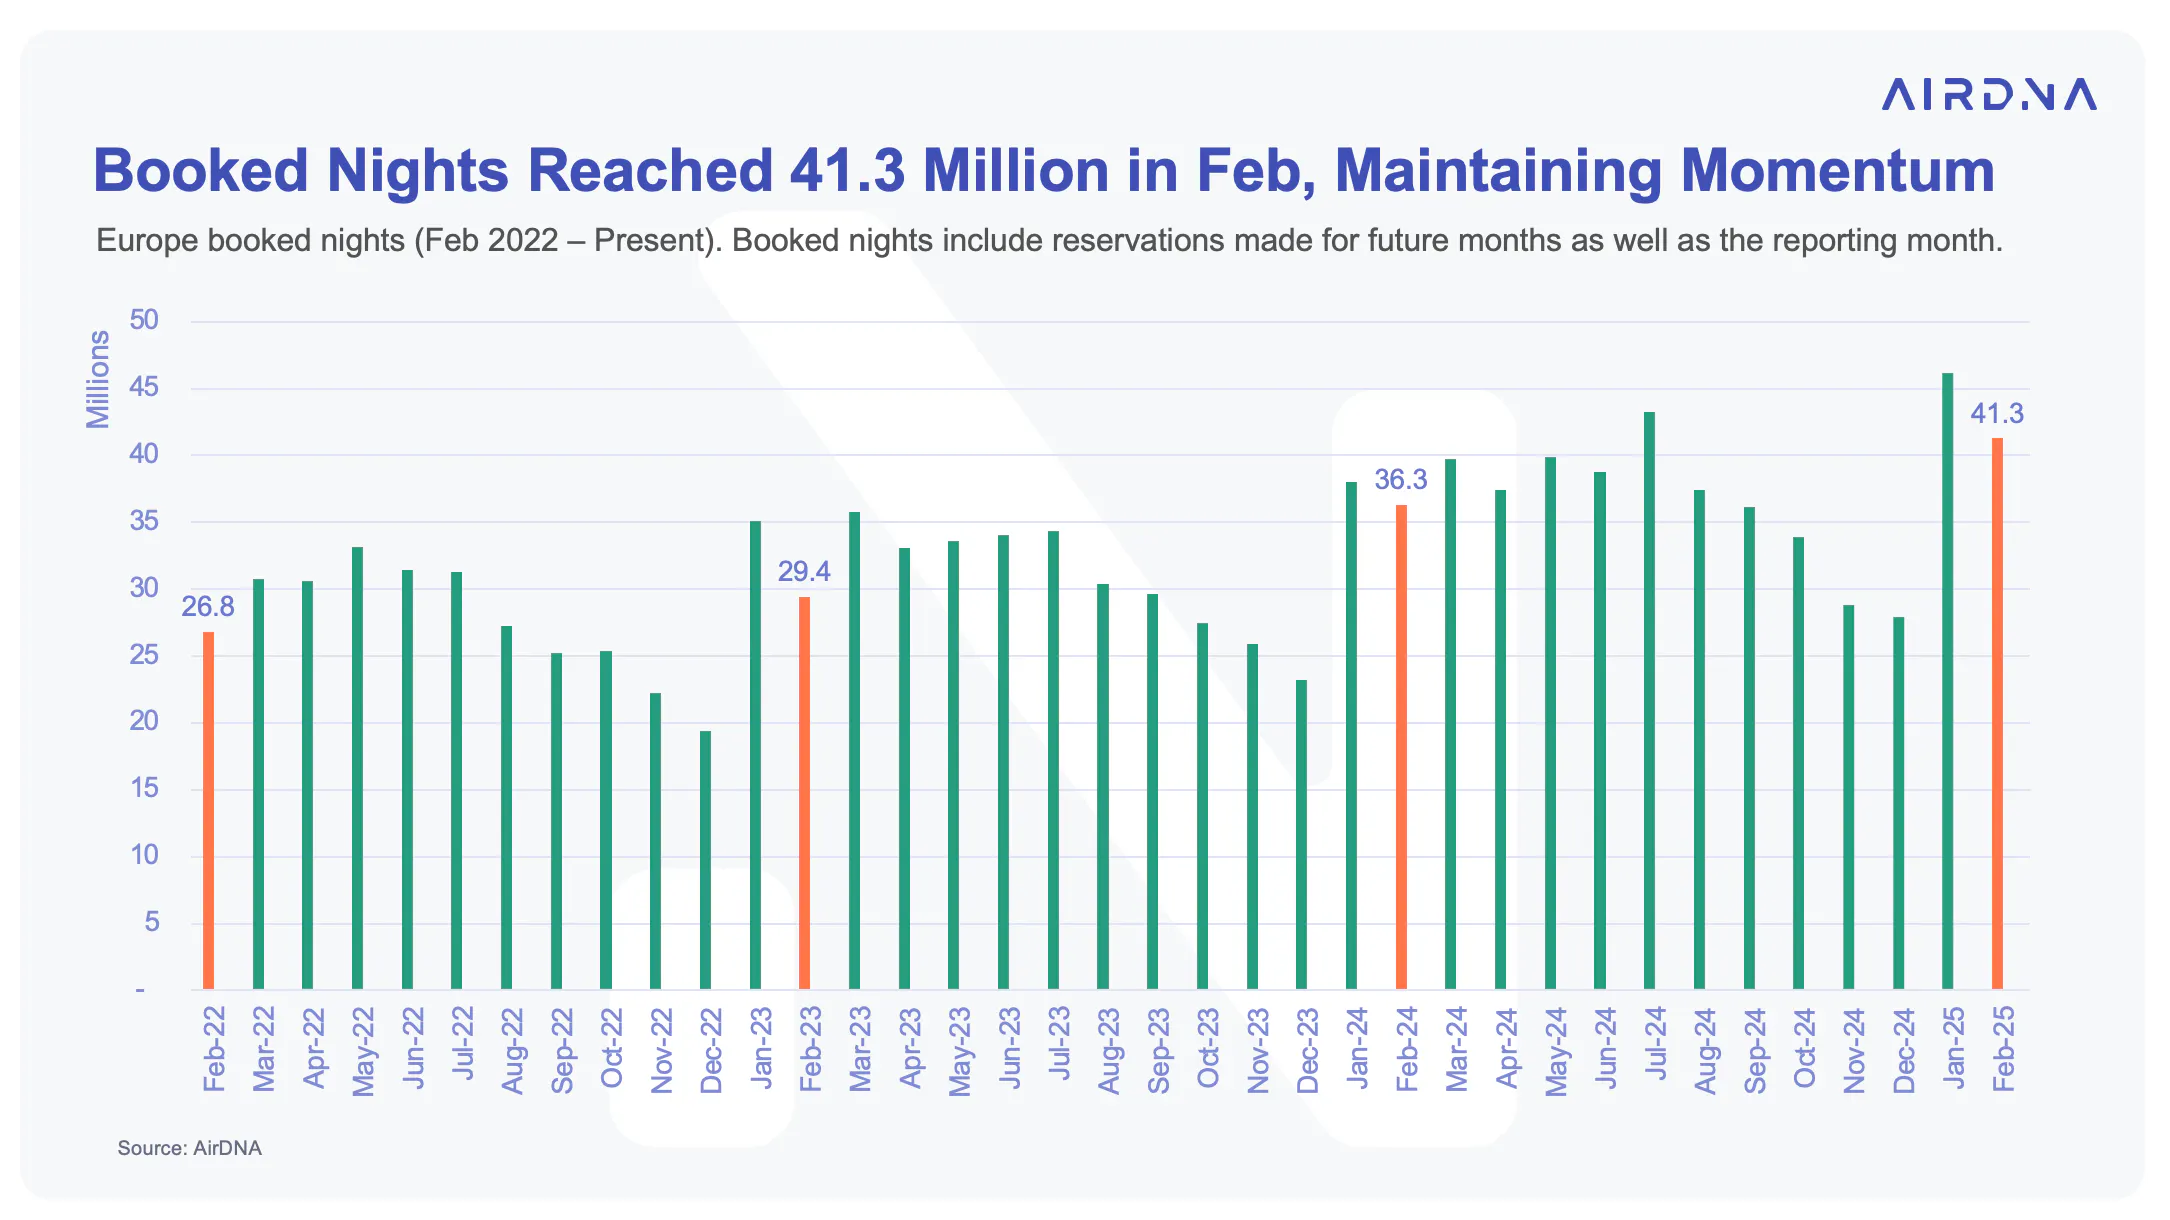
Last month, Europe set a new record for demand nights stayed in February, while also reaching a historic high for booked nights during the month.
Booked nights—reservations made in February for stays in the same month or future months—are a key leading indicator of short-term rental demand. In February, future reservations across Europe surged 13.7% YoY, extending January’s record-breaking momentum and setting the stage for a strong start to the year.
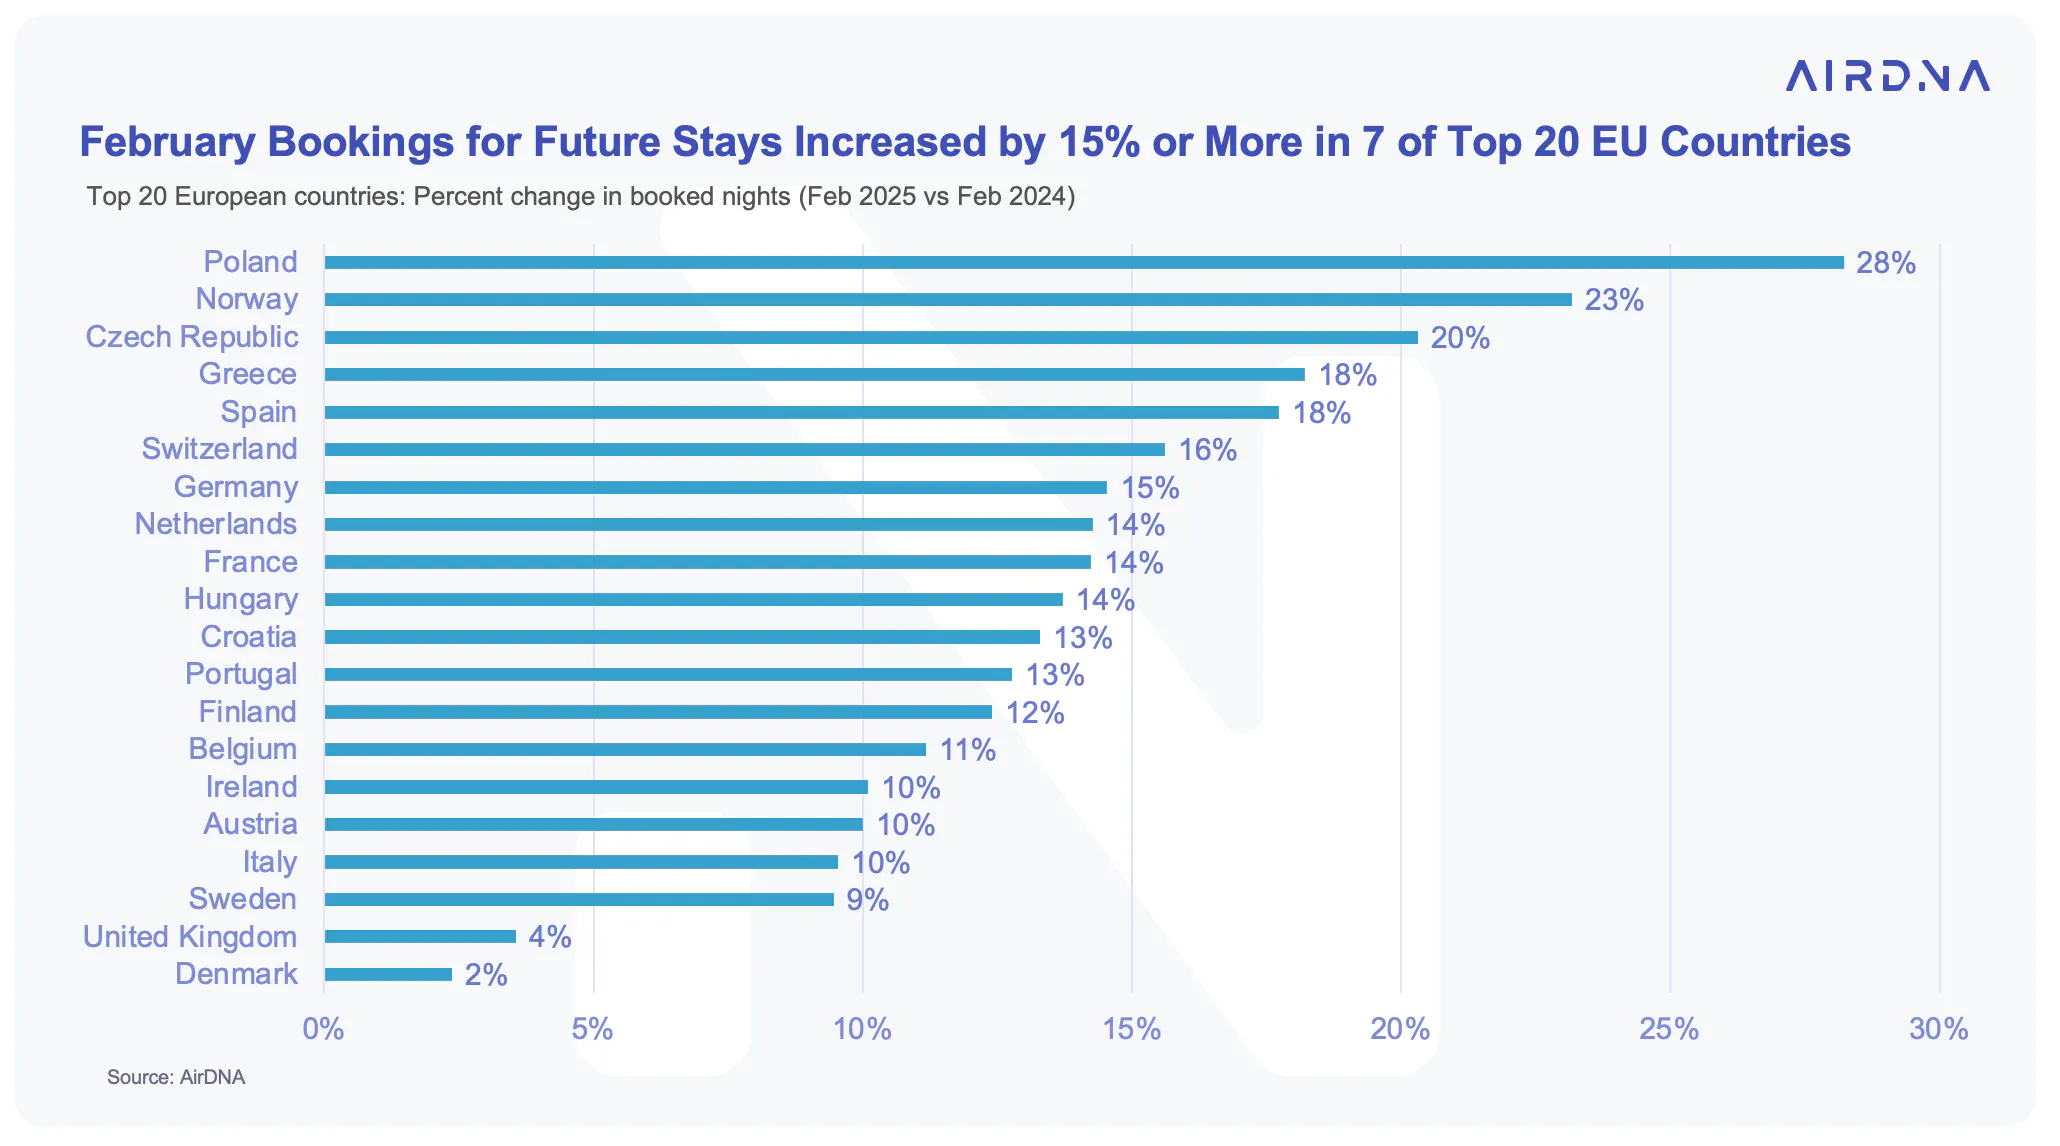
Breaking down booking growth among the largest STR countries in Europe, here are the top five countries that saw the biggest YoY growth in February bookings for future stays.
- Poland (+28% YoY)
- Norway (+23% YoY)
- Czech Republic (+20% YoY)
- Greece (+18% YoY)
- Spain (+18% YoY)
The 5 of the top 20 countries with the slowest booking growth for future stays are:
- Denmark (+2% YoY)
- United Kingdom (+4% YoY)
- Sweden (+9% YoY)
- Italy (+10% YoY)
- Austria (+10% YoY)
Robust Demand Fueled Double-Digit Growth in Nights Stayed
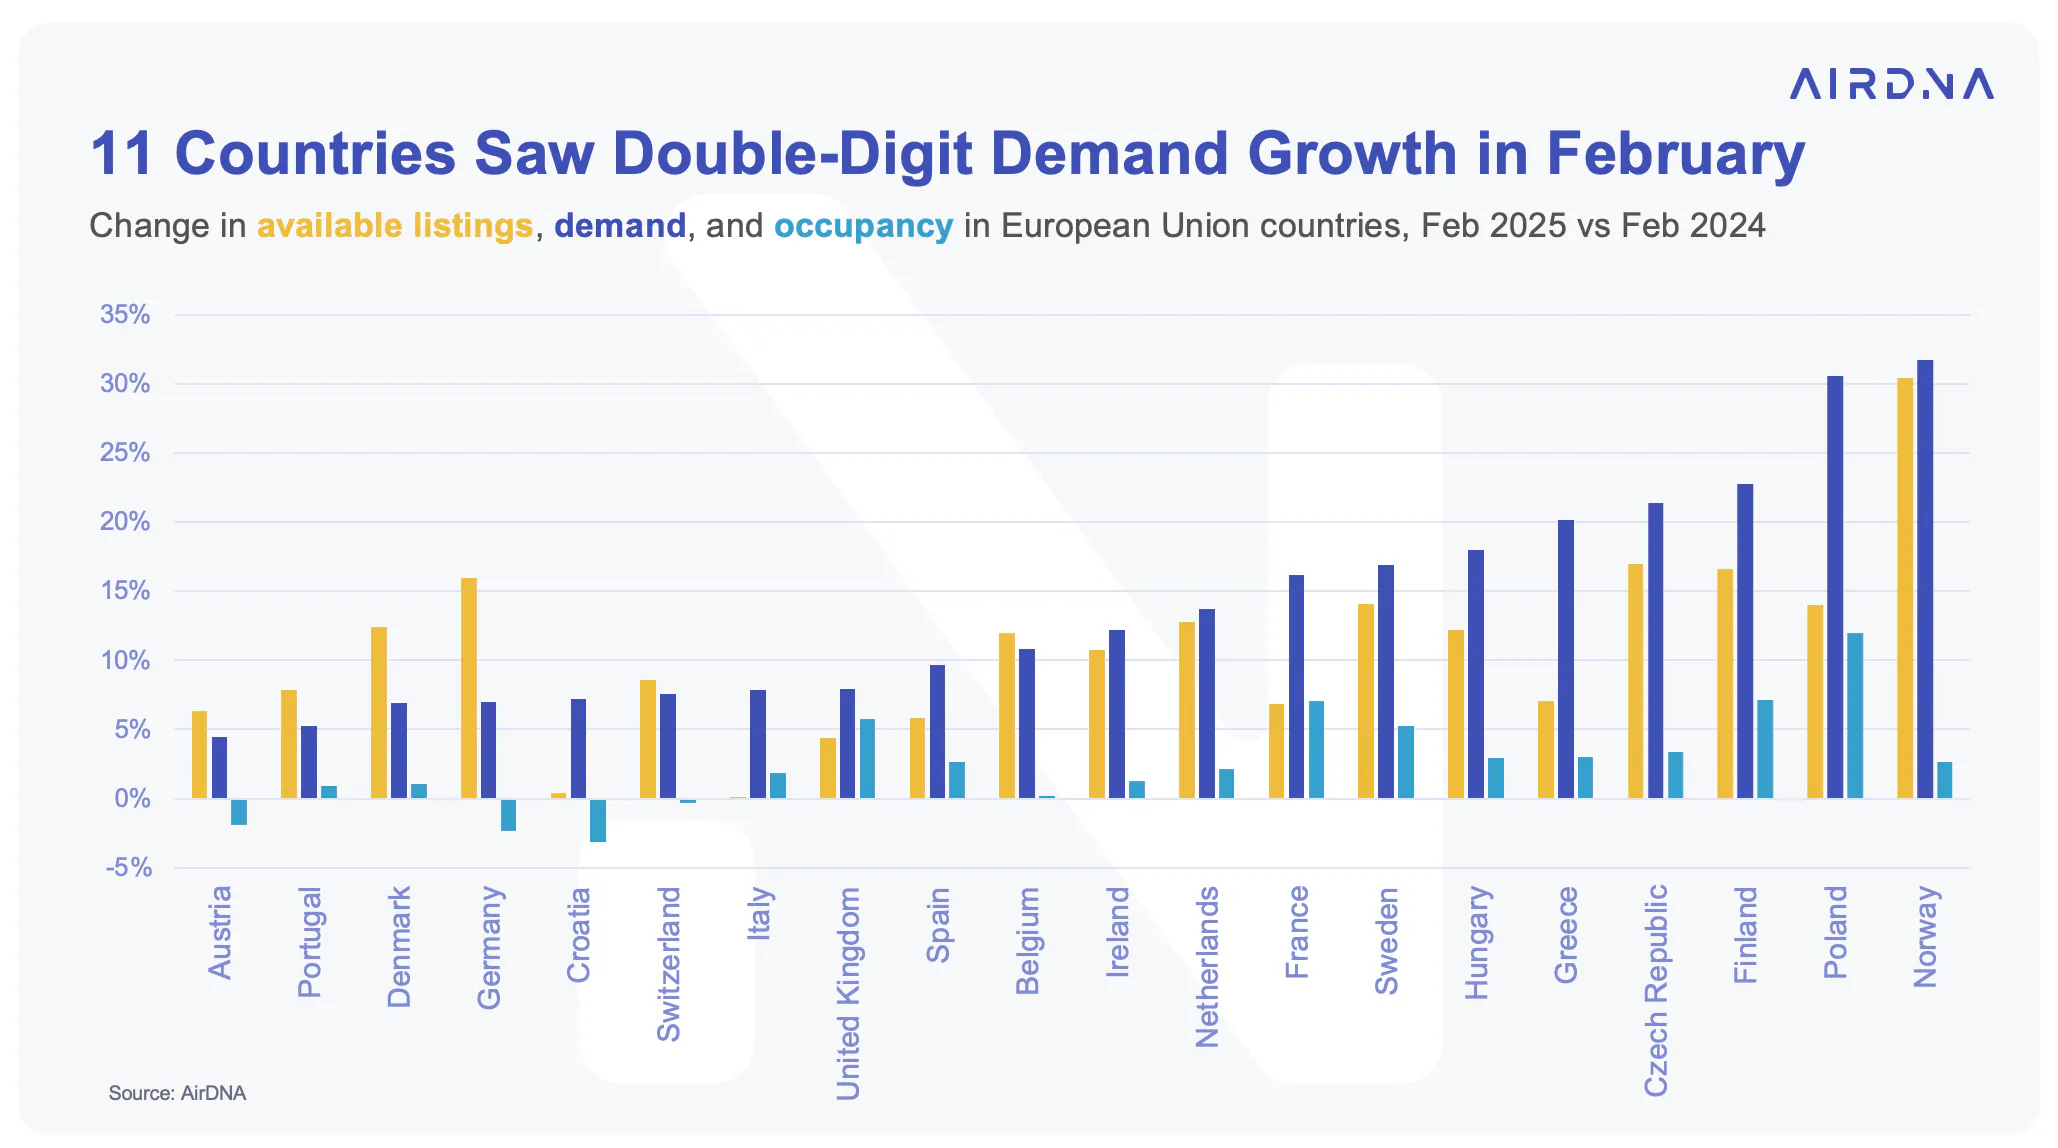
Turning to demand performance among the top 20 largest European countries, 11 of the top 20 countries saw double-digit growth in night stayed for February. The leading countries saw more than 20% YoY growth in nights stayed:
- Norway (+31.7% YoY)
- Poland (+30.6% YoY)
- Finland (+22.7% YoY)
- Czech Republic (+21.4% YoY)
- Greece (+20.1% YoY)
Listing growth did not keep up with demand and occupancy rates in 4 of the top-performing countries jumped more than 3% YoY, except for Norway (+2.6%).
The bottom 5 countries that lagged behind for growth in nights stayed were:
- Austria (+4.5% YoY)
- Portugal (+5.2% YoY)
- Denmark (+6.9% YoY)
- Germany (+7.0% YoY)
- Croatia (+7.2% YoY)
Of the bottom 5 countries’ occupancy, Croatia (-3.2% YoY), Germany (-2.3% YoY) and Austria (-2.0% YoY) experienced a decline in February.
Last-Minute Spring Break Deals in Europe
Easter demand has been exceptionally strong this year, influencing February booking patterns.
With warmer weather this Easter compared to last year—when the holiday fell in late March—more travelers are extending their stays beyond Easter week to enjoy the spring blossom season. This shift is evident in sustained booking demand, which remains elevated for up to two weeks after Easter.
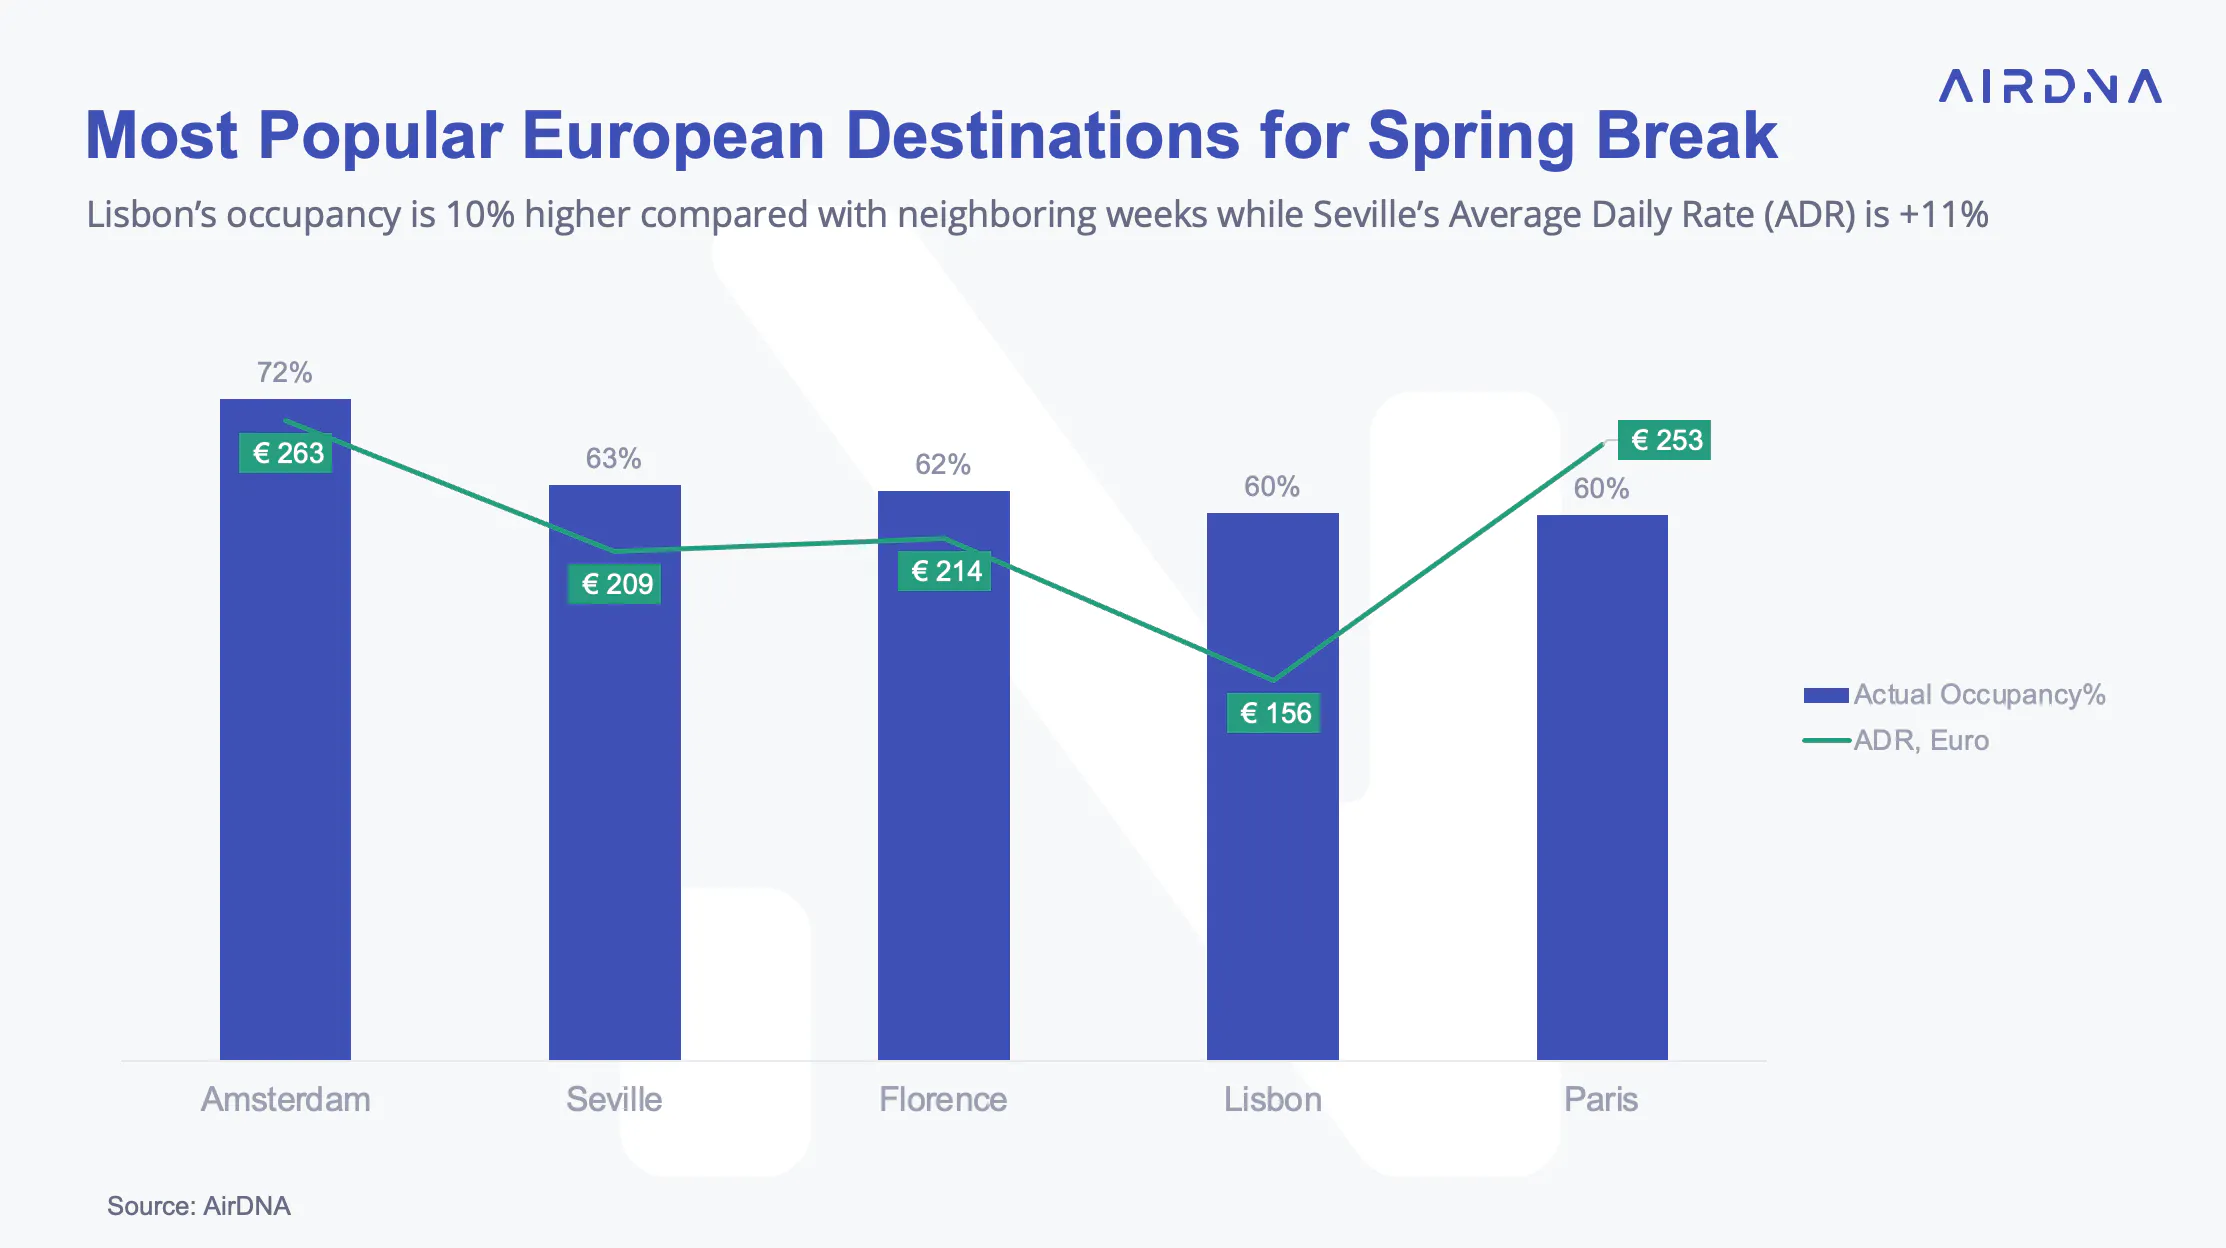
As of early March, some cities have already exceeded 60% occupancy with the current on-the-books demand. With one month until Easter, these cities are set to be highly popular, with ADRs among the highest in Europe.
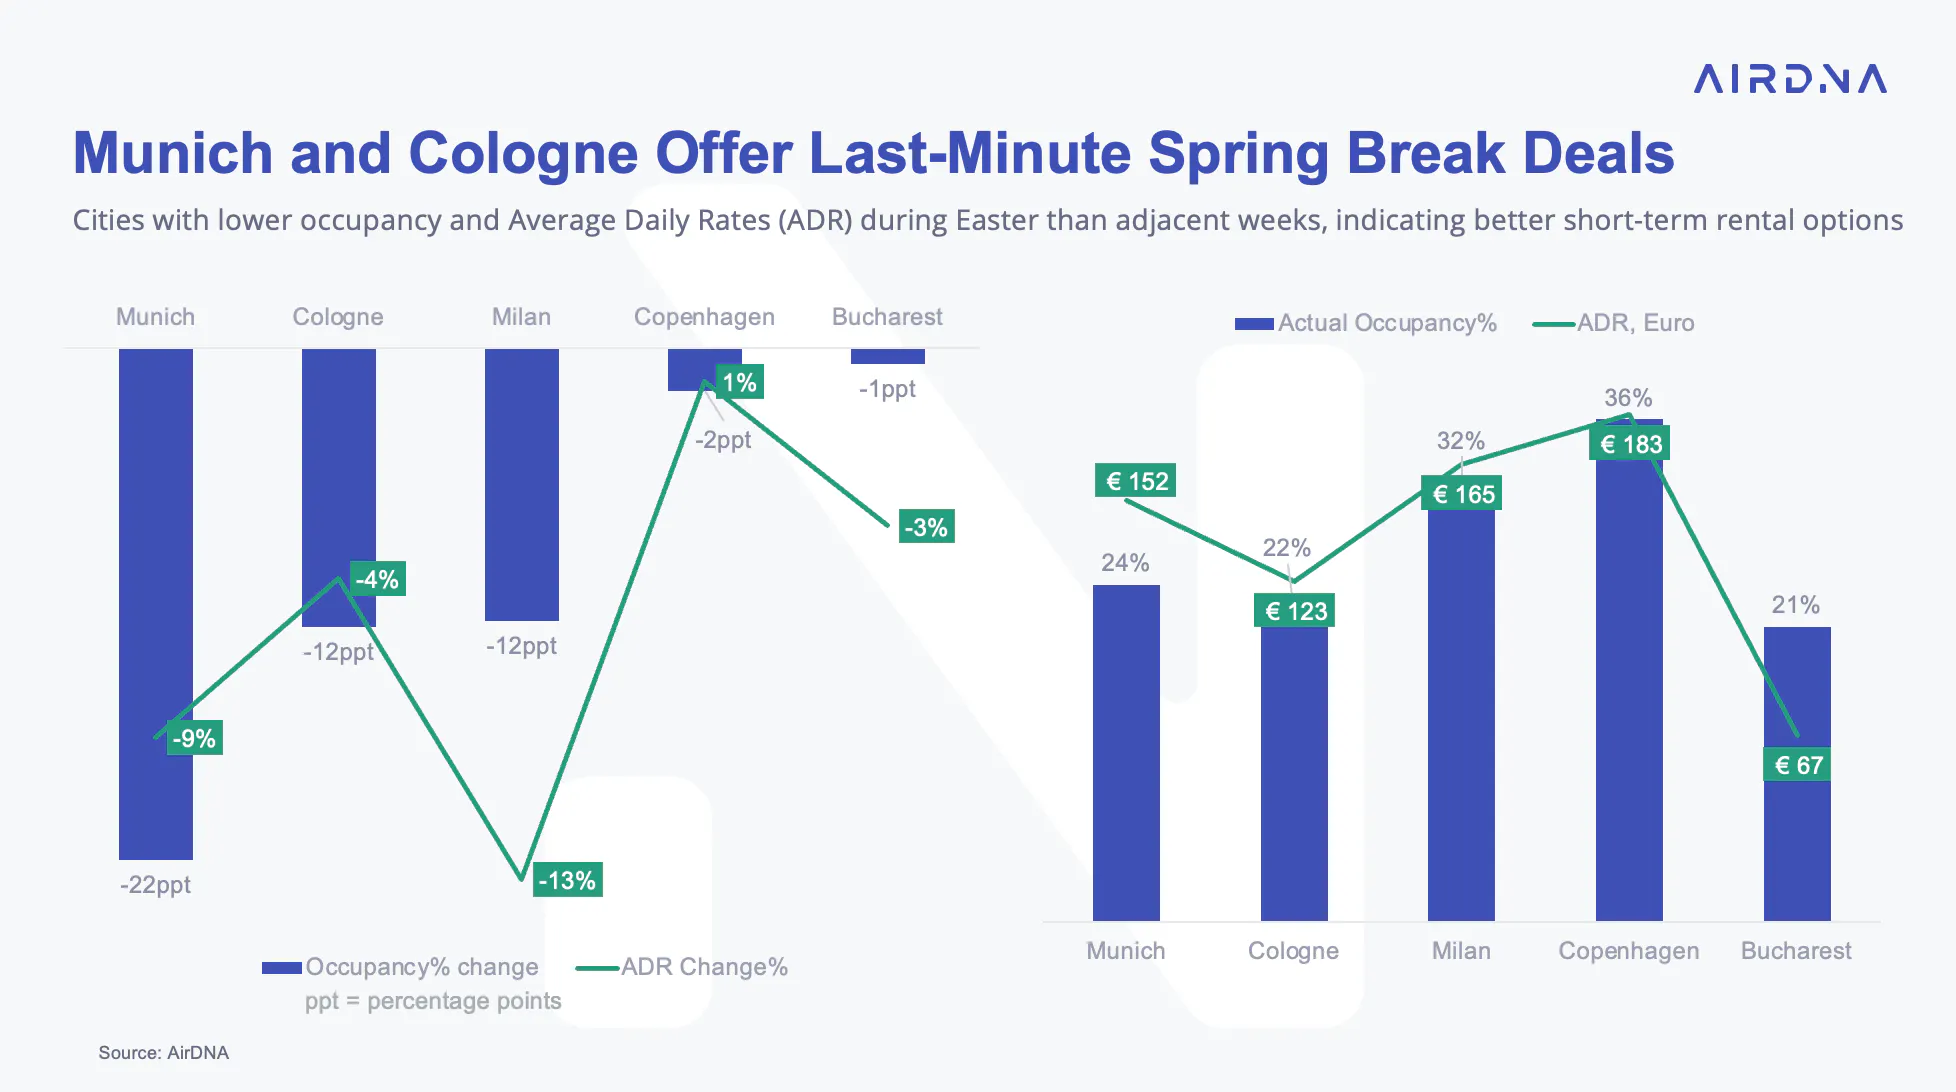
While most of the popular destinations have witnessed a strong momentum during Easter week, a few exceptions remain, offering good options for last-minute deals.
For those traveling exclusively during Easter week, Munich and Cologne, Germany have lower occupancy and ADR compared to adjacent weeks.
Jubilee Impact Makes Italy A Popular Destination
Italy stands out as the top destination this year, largely driven by the Jubilee Year effect, a special Catholic celebration held every 25 years that draws millions of pilgrims to Rome and other religious sites.
With both 2024 and 2025 Easter falling on March 11, demand for Italian short-term rentals began rising two weeks before Easter week. The combination of religious tourism and seasonal travel trends has fueled strong bookings, with demand expected to grow further in the coming weeks.
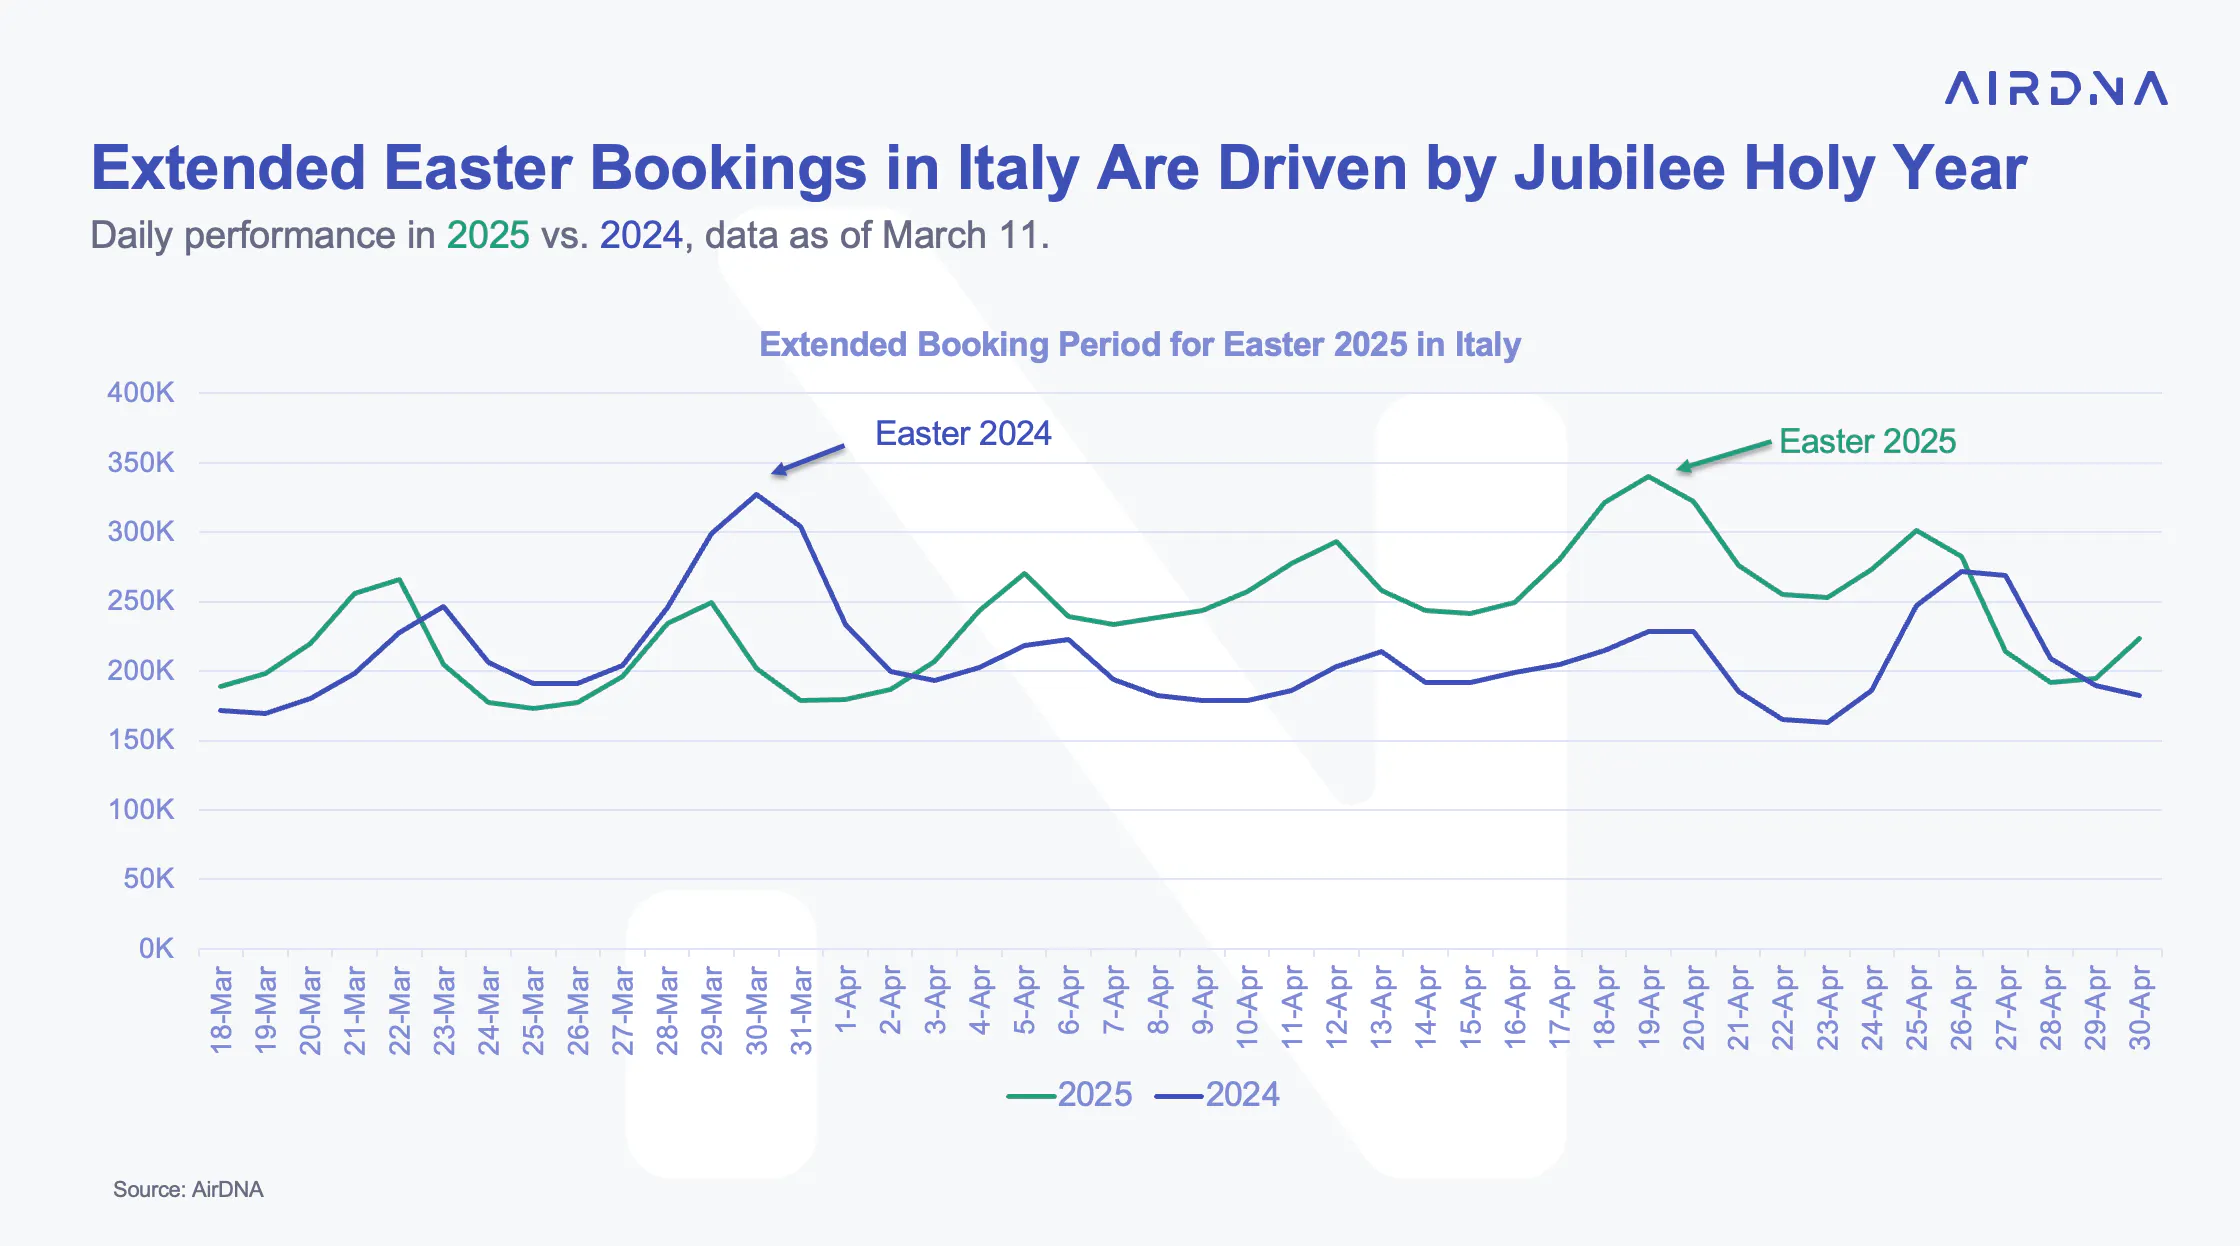
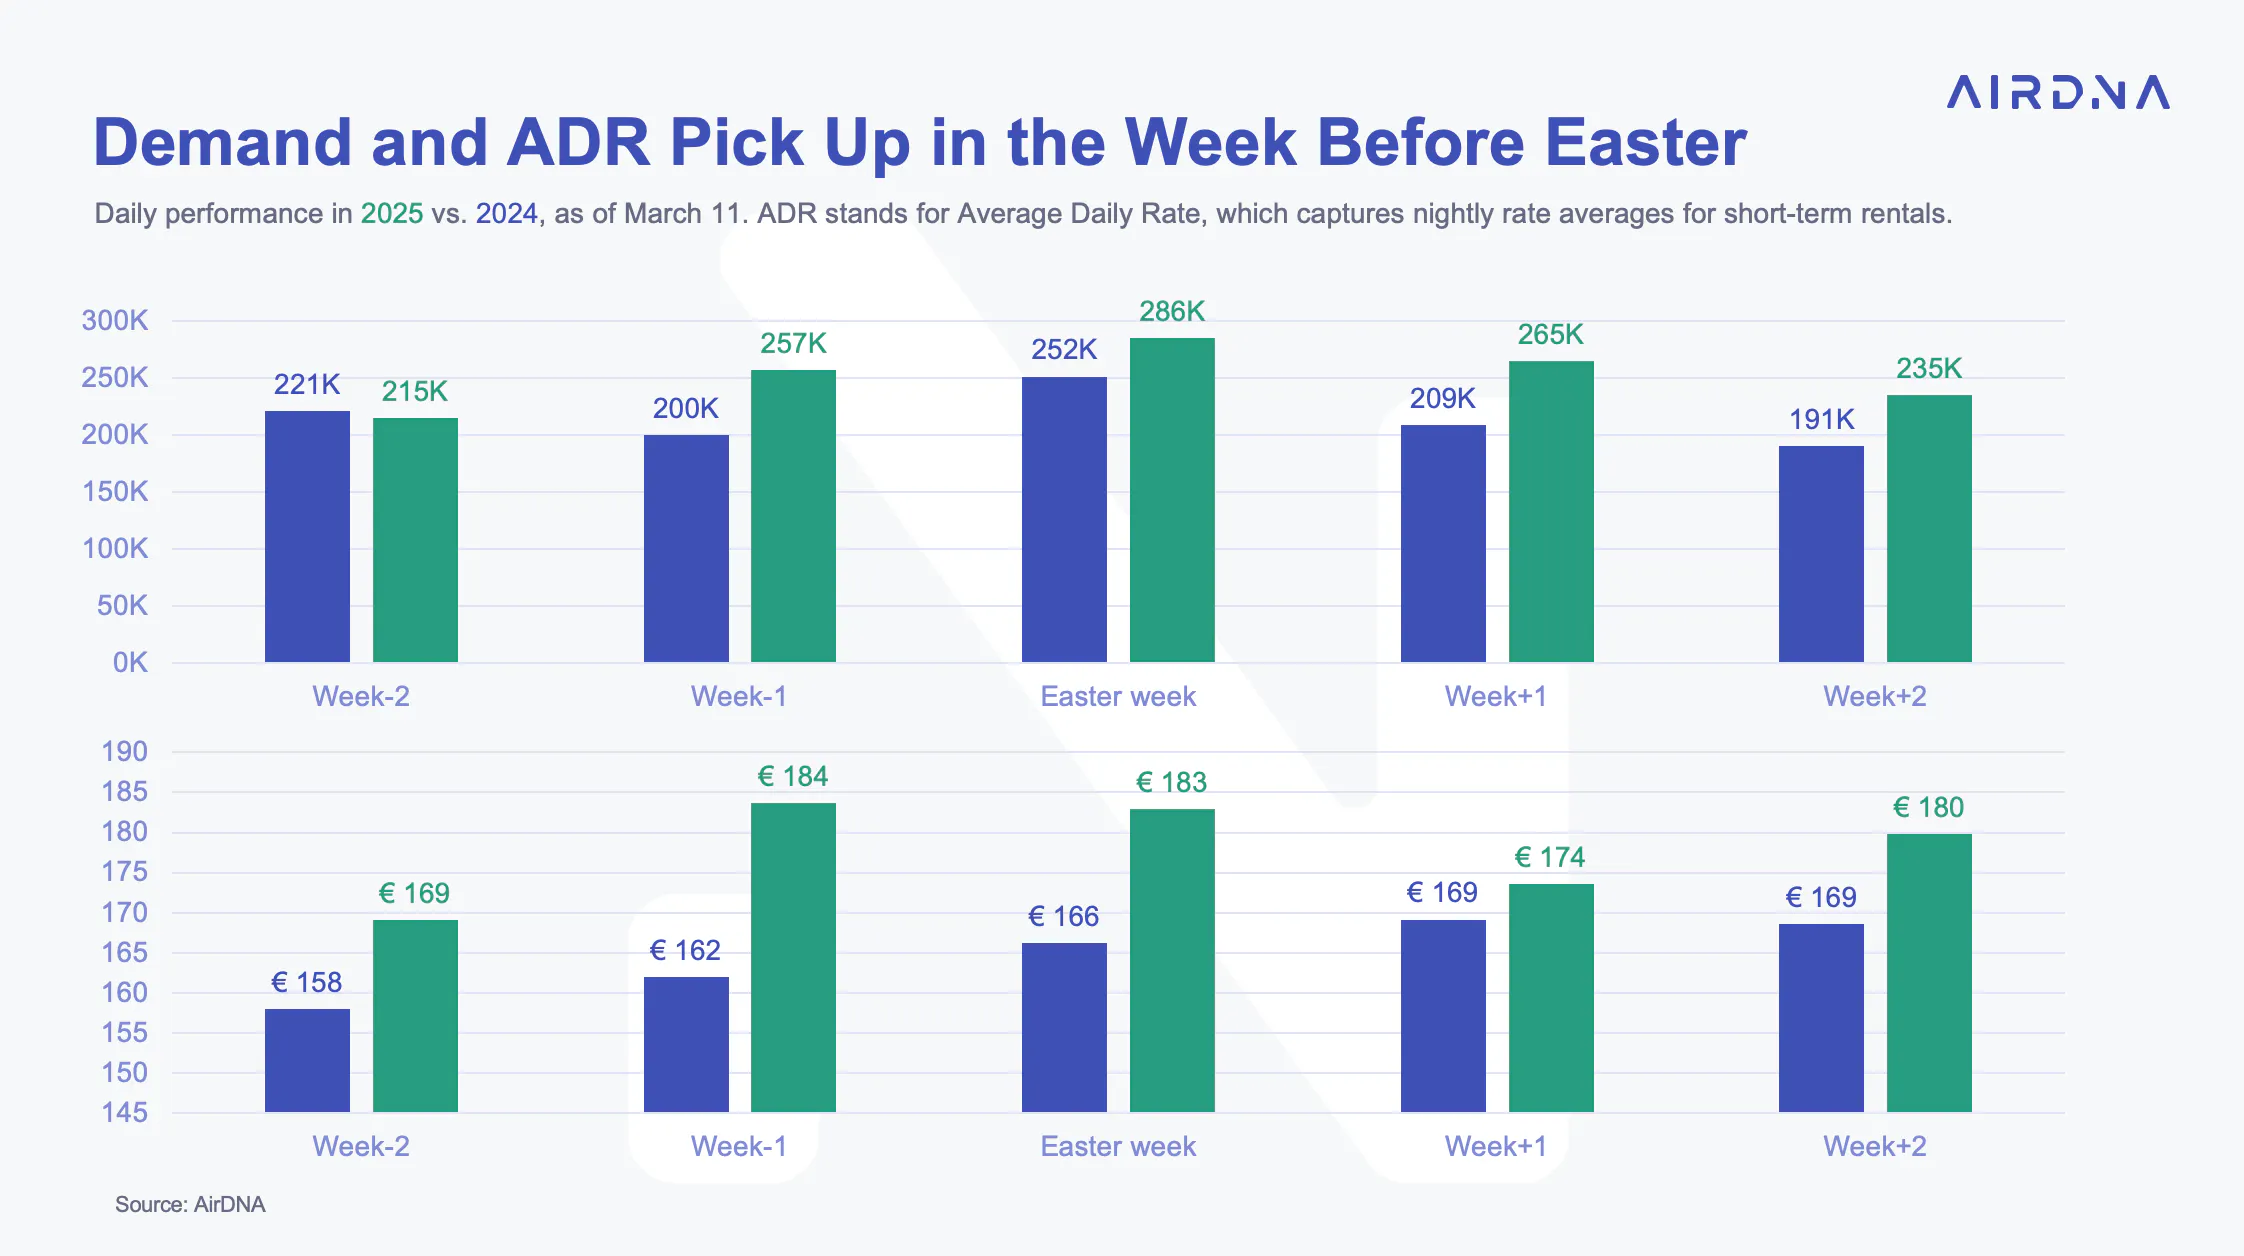
Weekly comparisons confirm strong demand growth in Italy. The average daily booked nights for the week before Easter 2025 have already surpassed Easter week demand in 2024. This growth is evident across the entire week, not just during peak days.
Pricing trends reinforce this shift, with ADR reaching €184—Easter week levels—one week before the holiday. This suggests that travelers are booking earlier and gearing up for Easter celebrations in Italy.
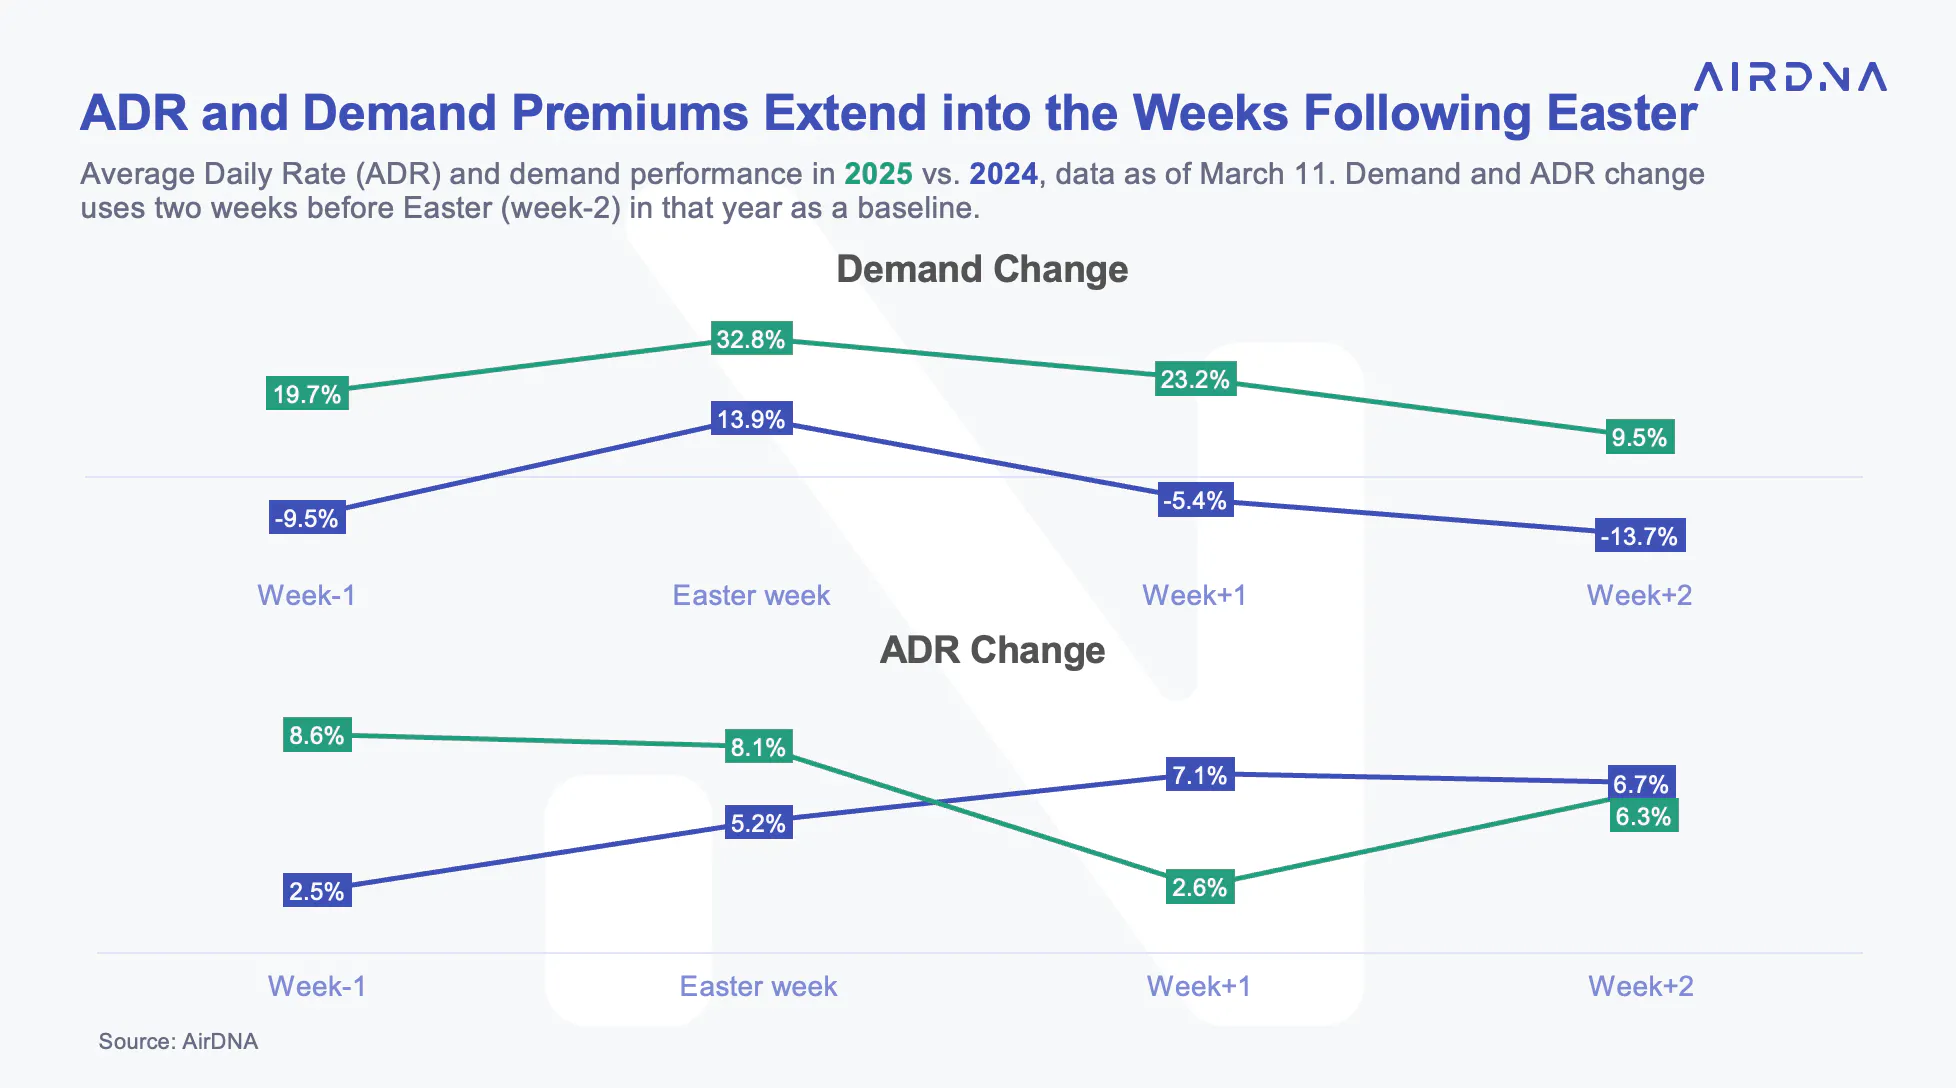
The data reflects a similar trend, with demand in 2025 remaining strong for four weeks after Easter. Bookings peak during Easter week at a +33% premium over the two-week period before Easter, compared to +14% premium in 2024.
ADR premiums have also increased in the following weeks, except for the week after Easter, where ADR is only +3% higher than two weeks prior. This could create an opportunity for budget-conscious travelers. AirDNA’s insights help hosts track booking patterns, allowing them to adjust pricing strategies and stay competitive throughout the season.
Greek Short-Term Rentals At A Glance
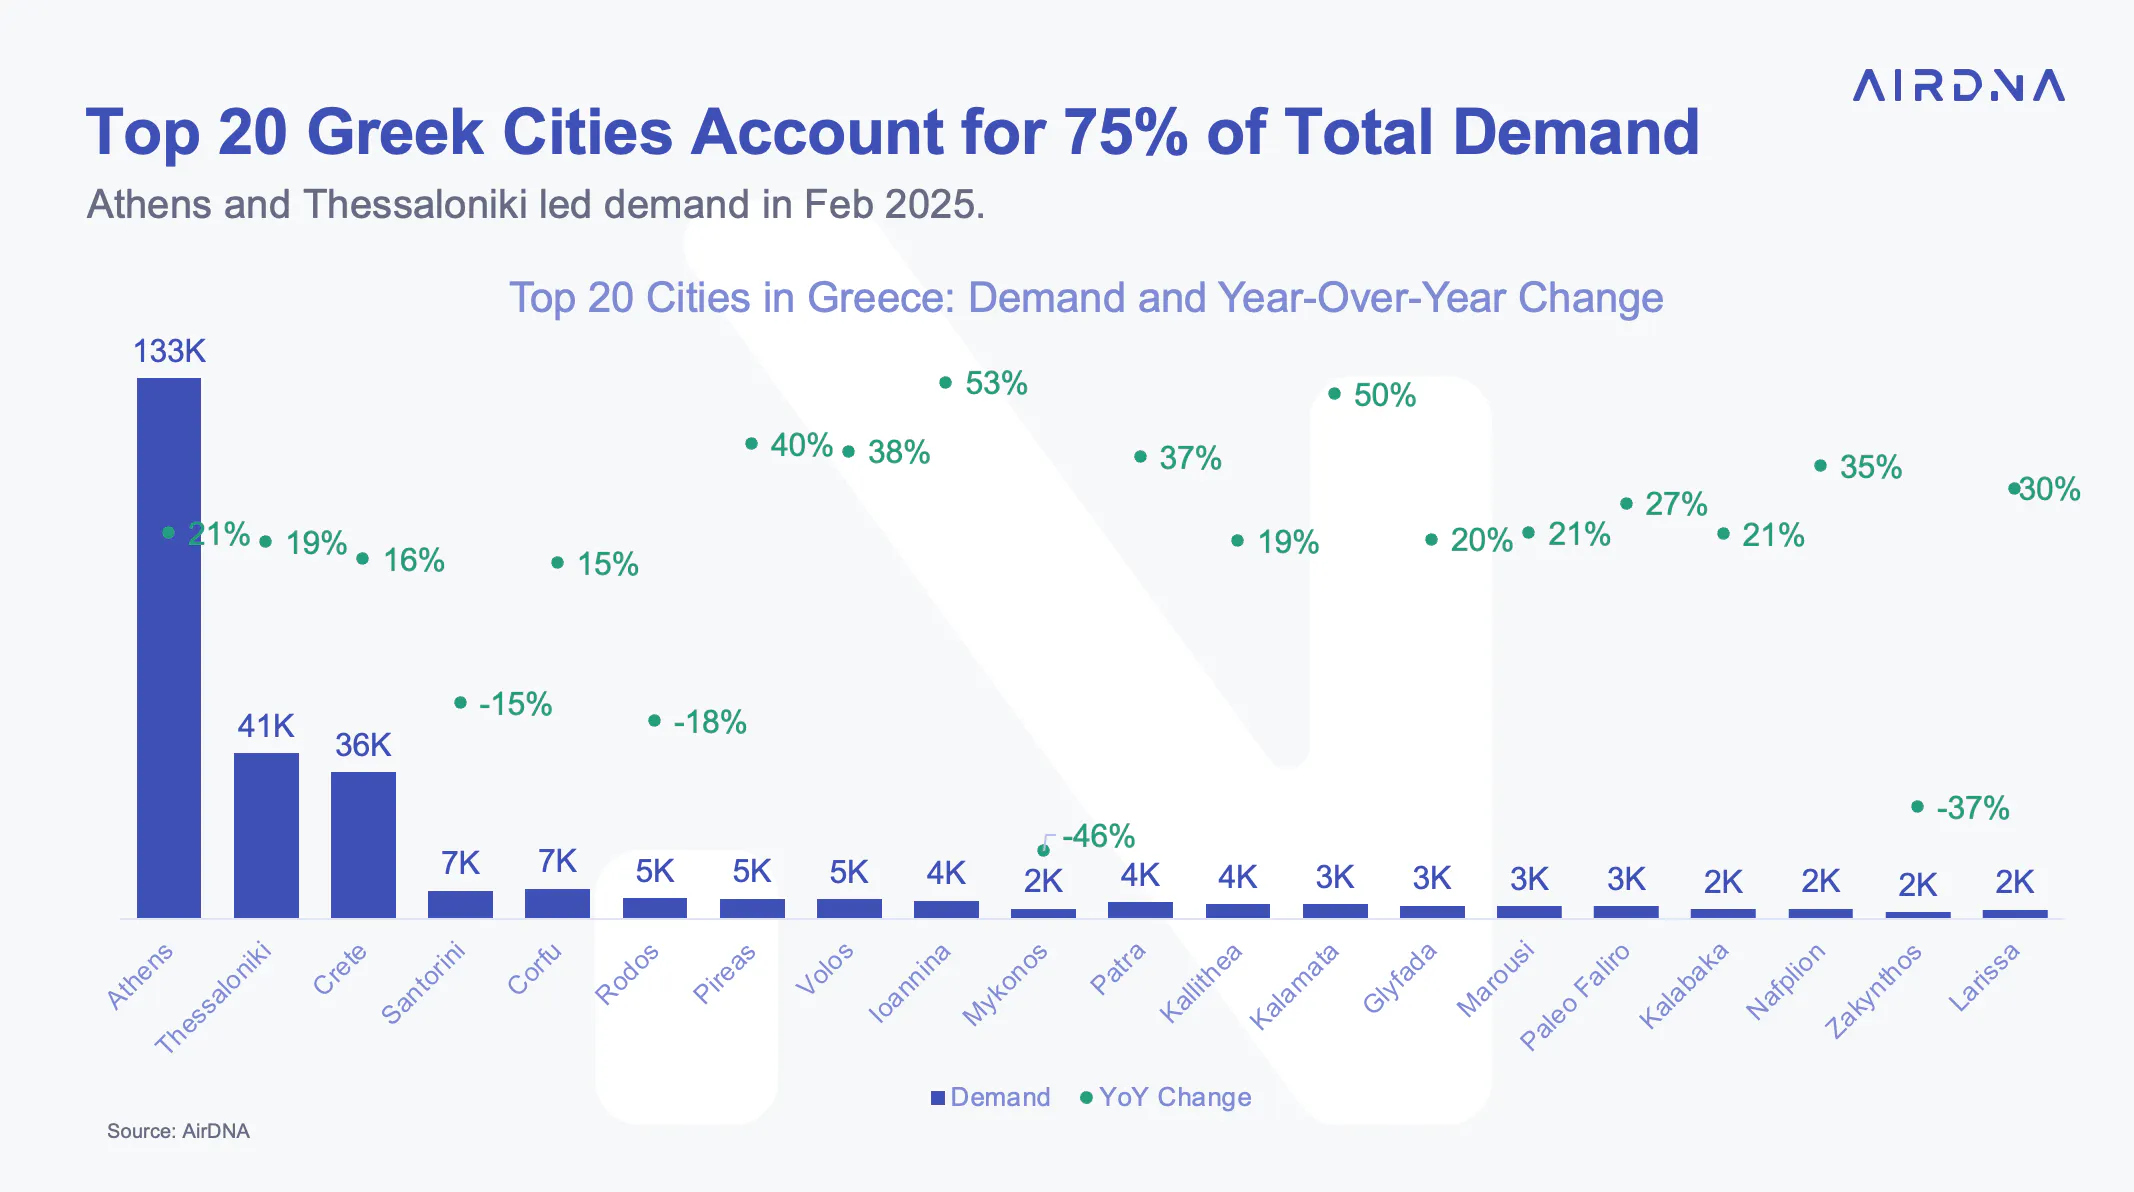
Greece remains one of Europe’s top travel destinations, with February demand surging 20% YOY from 2024 to 2025. This growth has outpaced supply expansion (+7%), driving higher occupancy rates across the country.
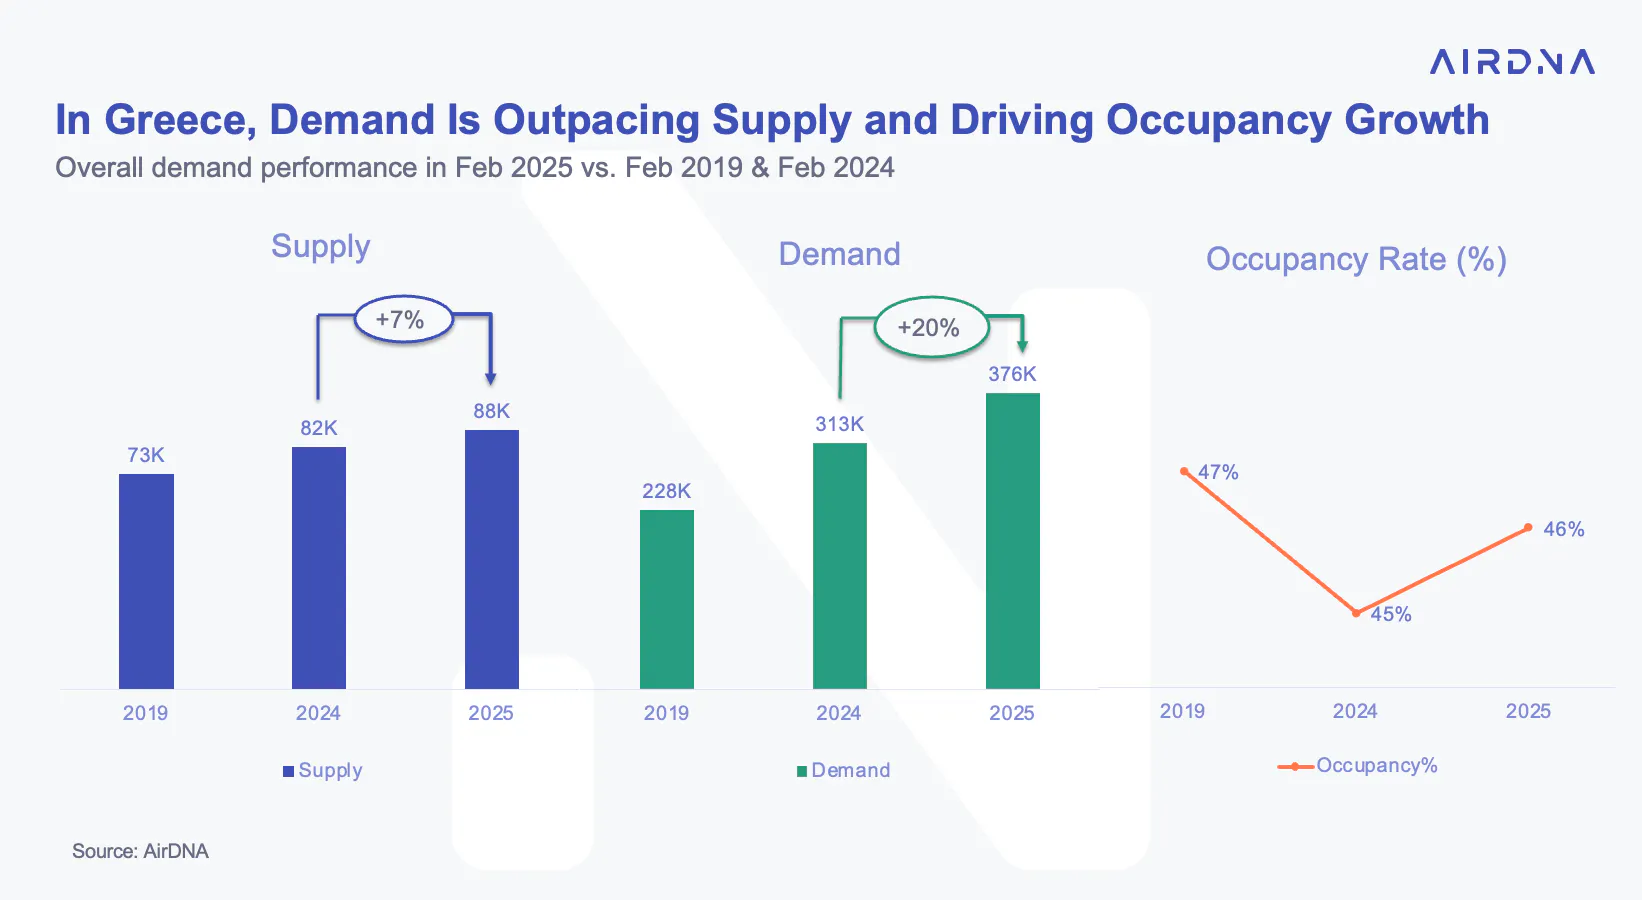
Athens, Thessaloniki, and Crete took the top 3 places among destinations within Greece, with demand in these destinations growing at a strong double-digit rate in Feb 2025.
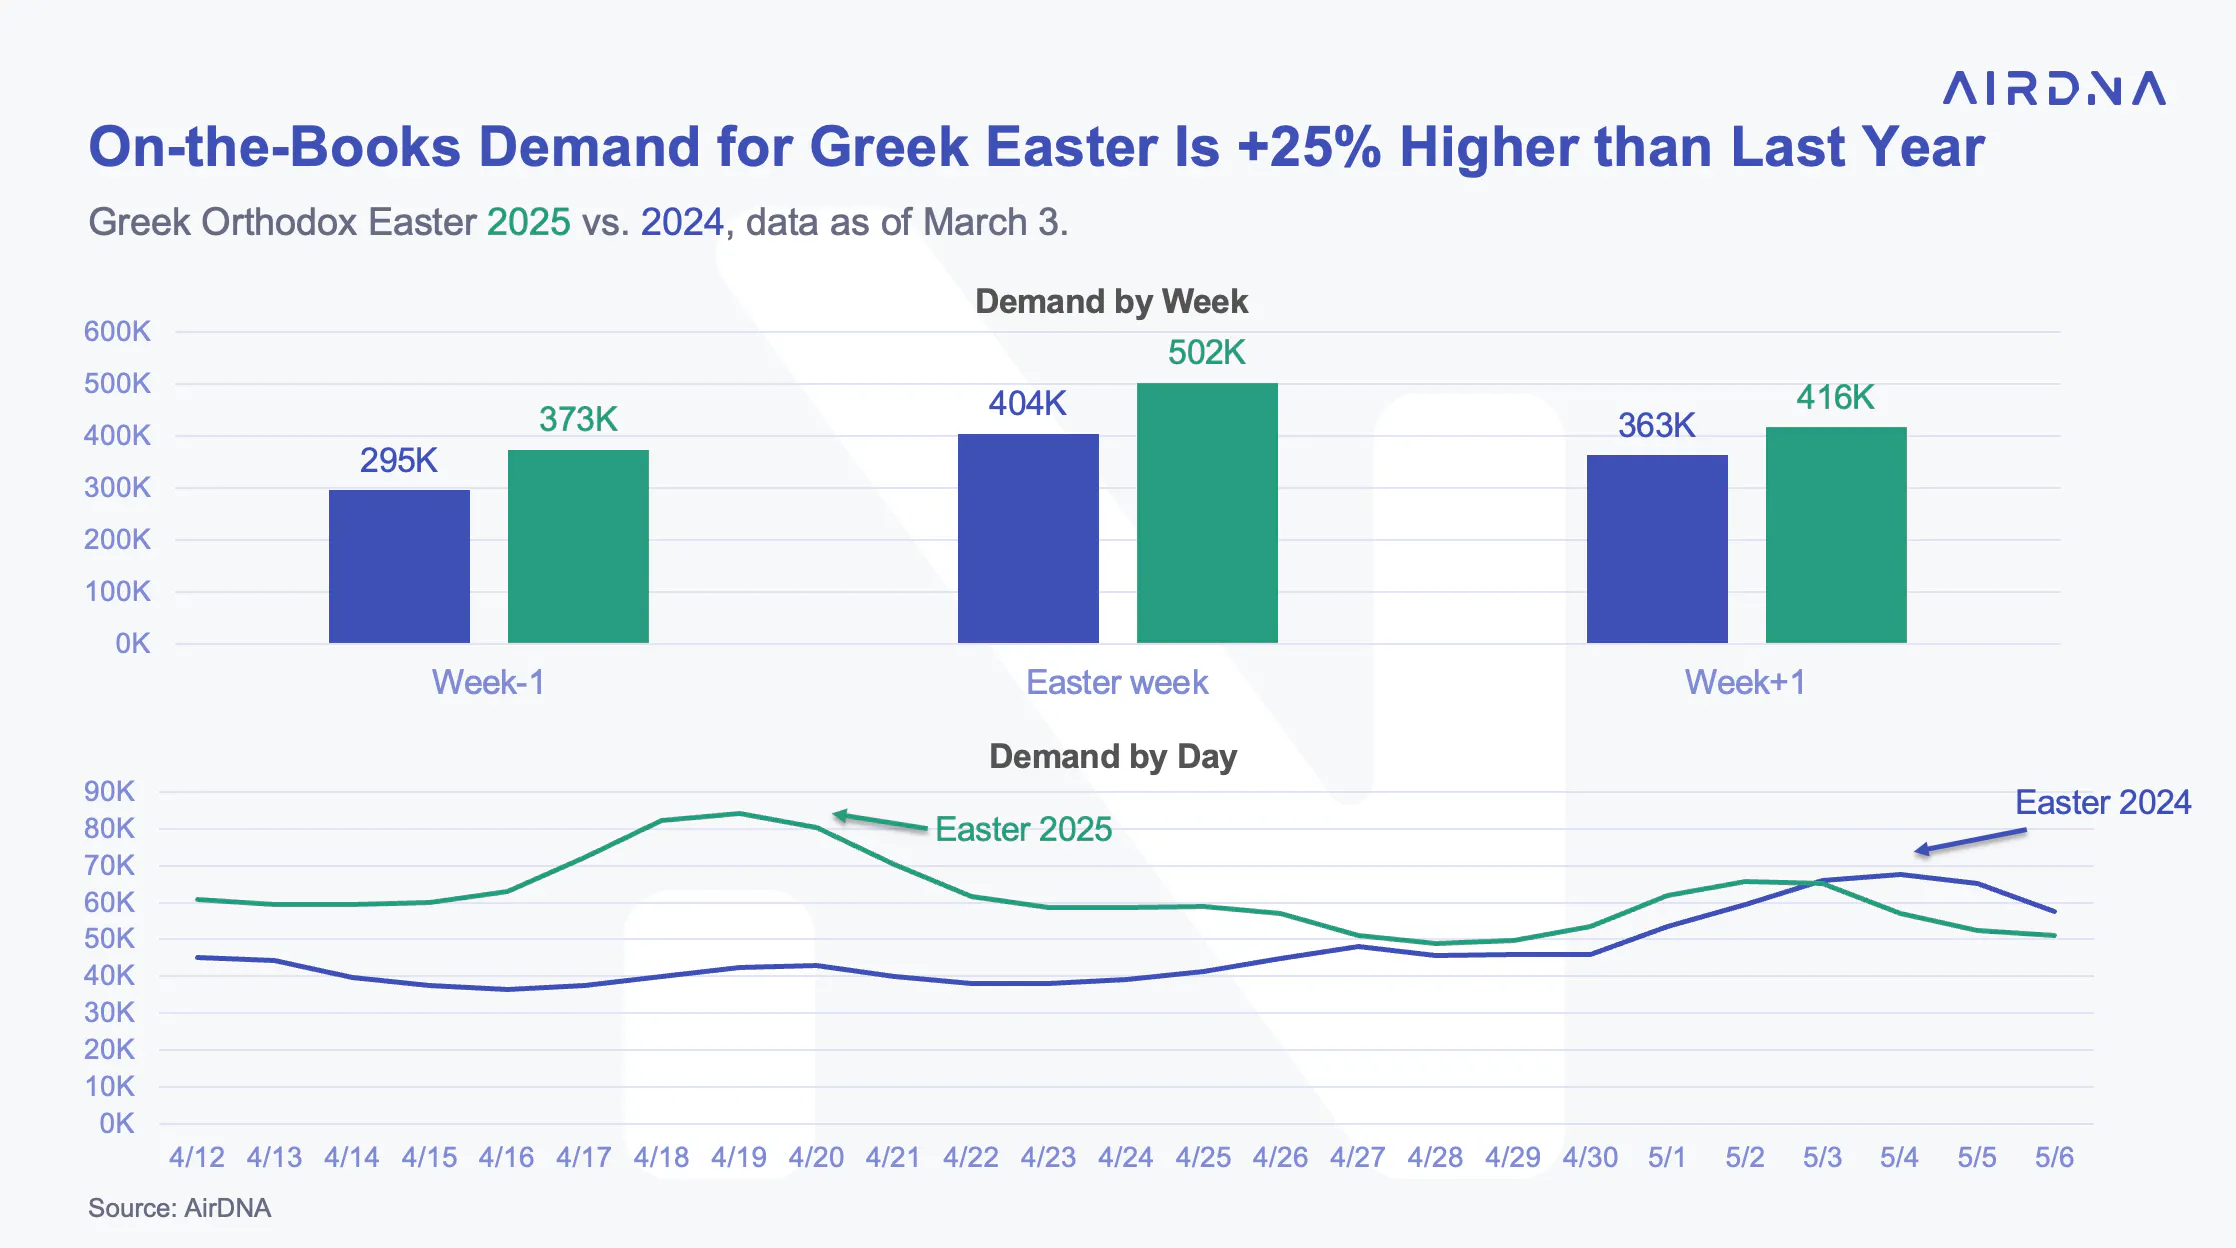
This year, Greek Orthodox Easter falls on April 20, the same date as Catholic Easter, unlike 2024, when it was on May 5. As a result, Easter week bookings have picked up earlier. Current reservations have already matched 2024’s Easter week levels, signaling strong demand for travel to Greece.
Beyoncé’s Concerts Launched Demand in Paris
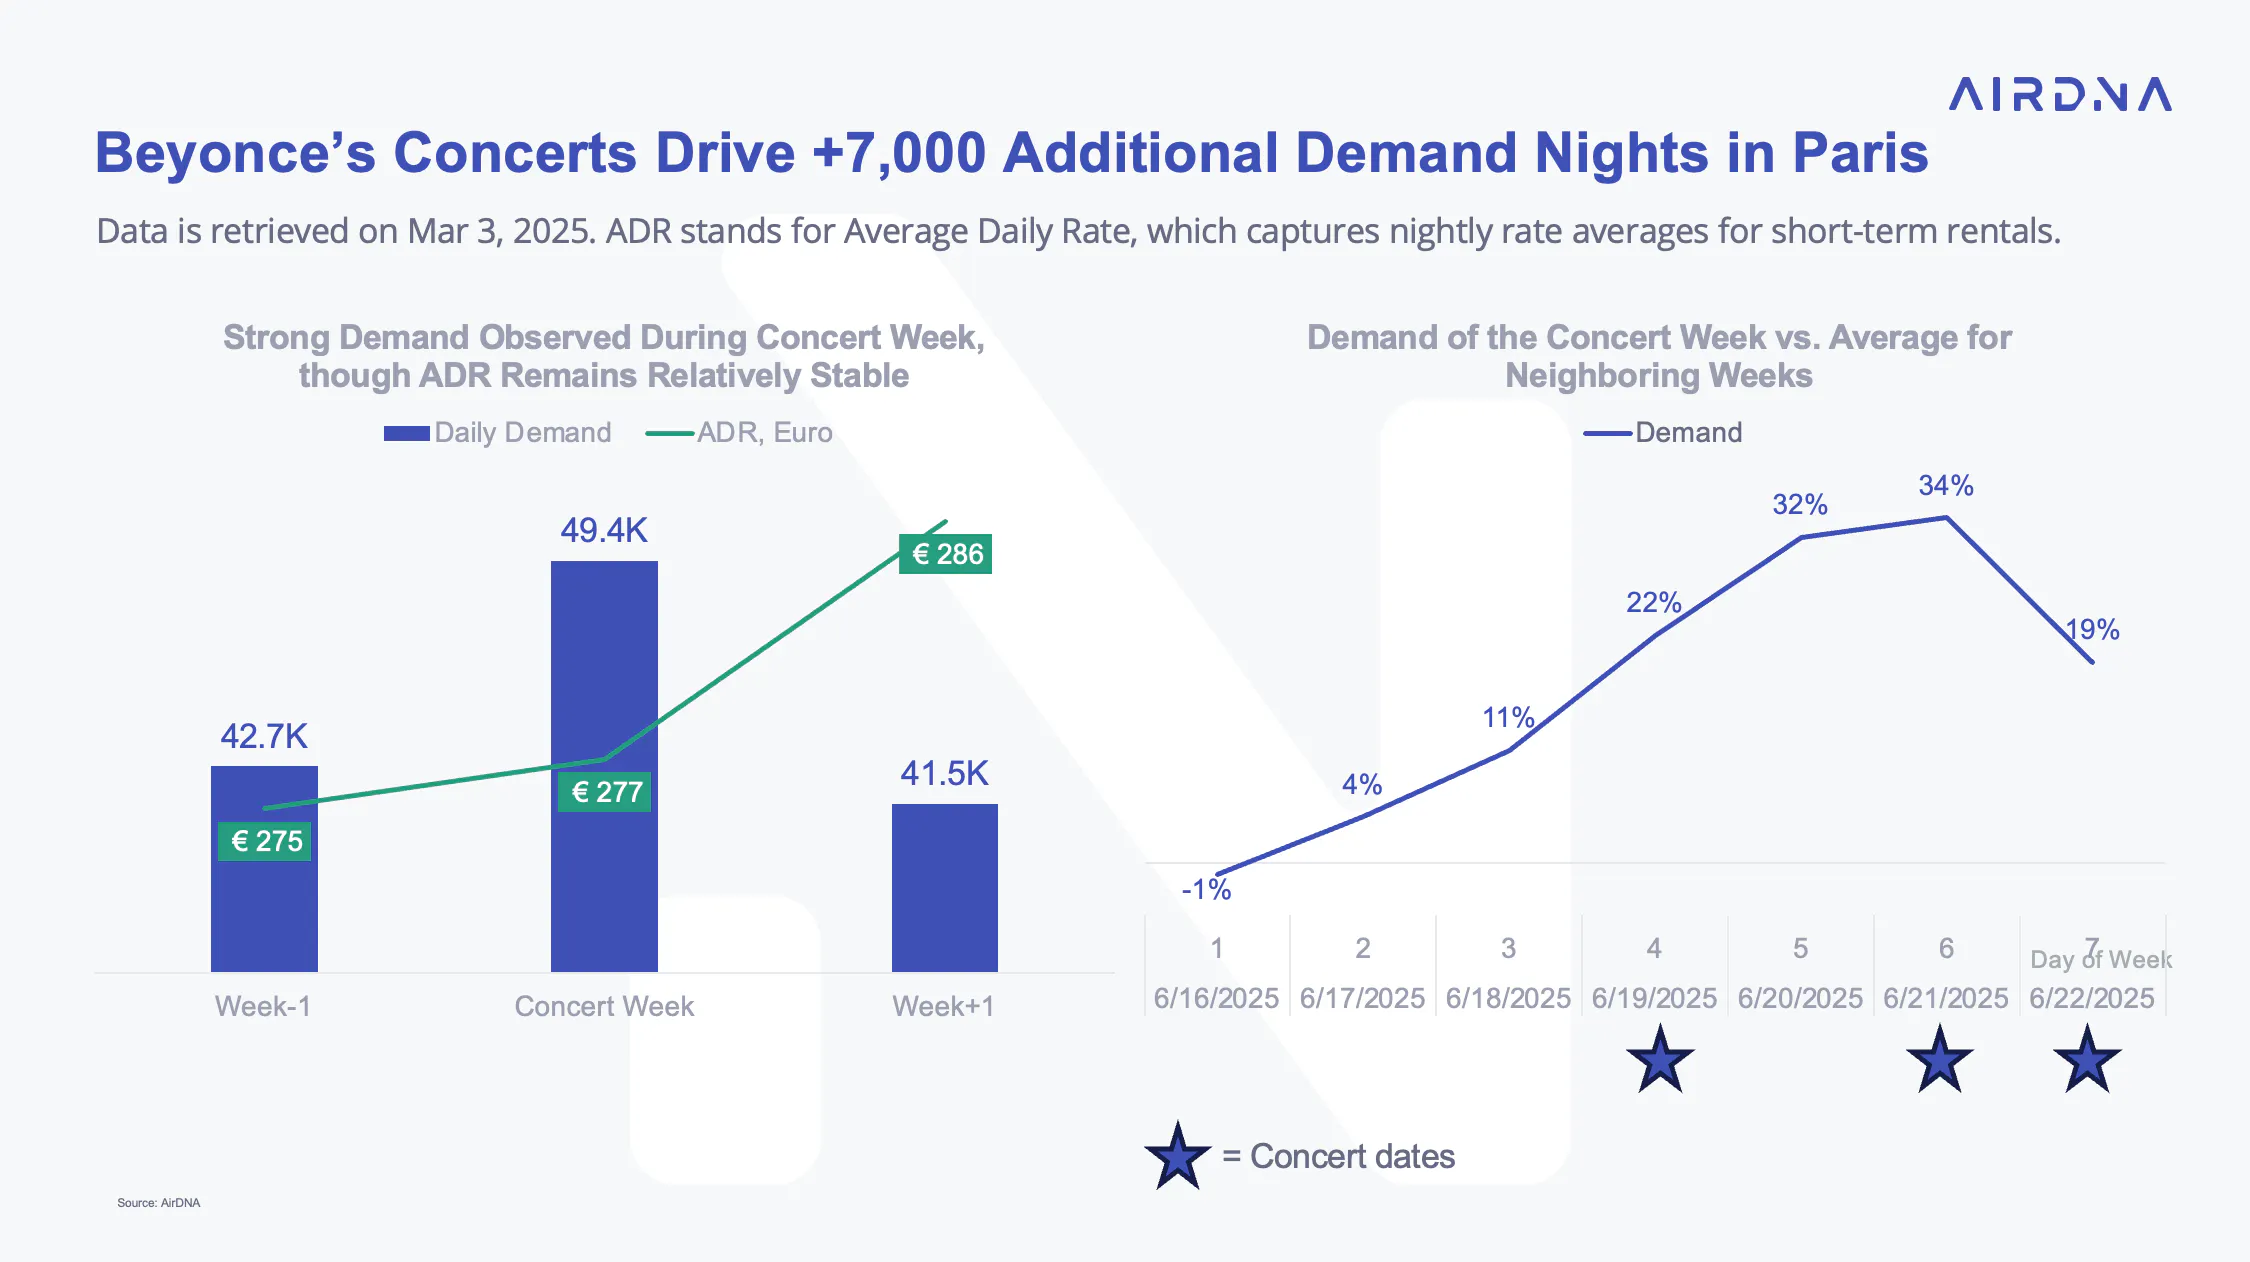
Beyoncé's mid-June concert tour in Paris has driven strong ticket sales and a surge in short-term rental bookings, reflecting the importance of factoring in upcoming events to an Airbnb pricing strategy. In Paris, daily demand for concert week has already reached 49.4K bookings per day, up from 42.7K the week before.
The biggest spikes are on June 19 (Thursday) and June 22 (Sunday), with demand up 20% compared to surrounding weeks. Friday and Saturday (June 20 and 21) show an even bigger increase, exceeding 30%, highlighting the strong draw of the event.
ARTICLE SUMMARY
February 2025 saw strong short-term rental (STR) demand, solid booking growth, and rising occupancy. Bookings for Easter travel surged with Italy as one of the hot destinations.
Jamie Zhang
AirDNA Data Analyst
Jamie Zhang is a Data Analyst at AirDNA, leveraging her background in data science and analytics to uncover key trends in the short-term rental industry. Before joining AirDNA, she worked as a data analyst at Shanghai Disney, where she specialized in revenue forecasting and financial planning . She holds a Master’s degree in International Economics and International Relations from Johns Hopkins. Jamie enjoys cycling to explore different corners of the city.